Benioff Makes use of Salesforce’s Greatest Product Launch in Years to Problem Microsoft
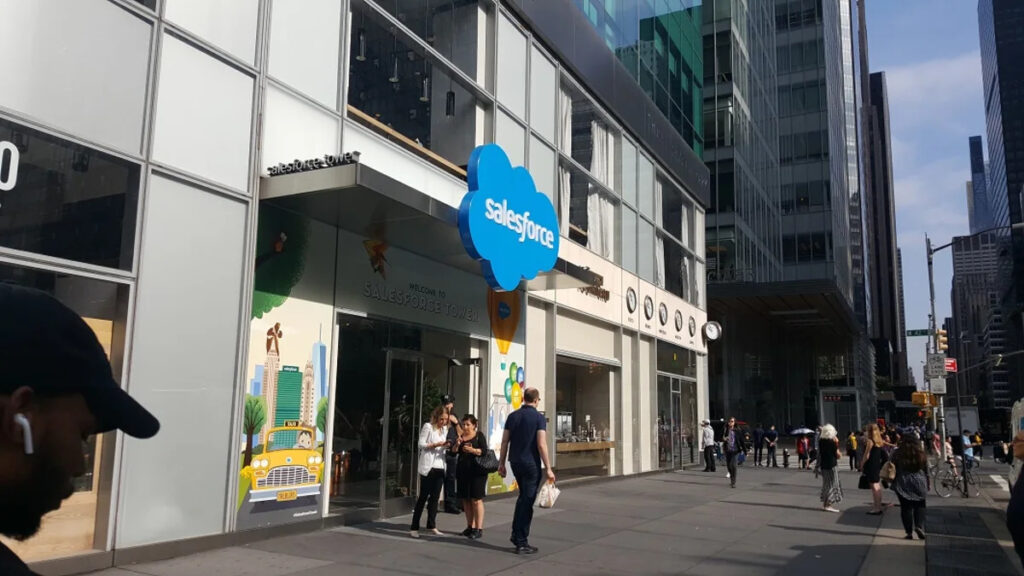

Marc Benioff isn’t one to go up an opportunity to take a jab at Microsoft Corporation (NASDAQ:MSFT), and Dreamforce 2026 was no completely different. The Salesforce CEO used the corporate’s flagship annual convention in San Francisco to announce AIforce, the largest product launch Salesforce, Inc. (NYSE:CRM) has made in years, and to as soon as once more discuss with Microsoft’s Copilot as “the brand new Clippy,” doubling down on a dig he made two years in the past.
What AIforce Actually Does
Salesforce is positioning AIforce as an open, provider-agnostic layer slightly than a single proprietary assistant. It’s supposed to work throughout a number of AI programs, together with Anthropic’s Claude, through a particular integration known as Claudeforce, which Salesforce claims ensures zero information retention by the mannequin supplier, in addition to ChatGPT, Slack, and different environments. Salesforce, Inc. (NYSE:CRM) made the announcement alongside a further strategic marker: a fiscal 2030 income goal of $63 billion, which administration reiterated at Dreamforce.
A Rivalry That Goes Back To 2024
Benioff portrayed AIforce as the answer to what he calls the “Fantasyland” drawback, arguing that competing AI options, together with Copilot, lack the reliable, managed business-data layer required to persistently run enterprise operations. It’s a continuation of a public feud that is been happening since at the least Dreamforce 2024, when Benioff first in contrast Copilot to Clippy, Microsoft’s extensively mocked, uninvited desktop assistant from the late Nineteen Nineties, saying, “We all know now that Microsoft Copilot is principally the brand new Microsoft Clippy, that prospects haven’t gotten worth from it.” He’s returned to that theme a number of occasions since, together with at Davos, in an October 2024 written critique saying that Microsoft “lacks the info, metadata, and enterprise safety fashions to create actual company intelligence,” and on a podcast the place he labeled Copilot a “great disservice” to the AI sector.
Favorable Analyst Response
Salesforce, Inc. (NYSE:CRM) shares closed at $255.65 on September 15, after an almost 34% rally within the earlier month following a tough begin to 2026 that noticed the inventory tumble as a lot as 37%. That momentum was fueled by Salesforce’s most up-to-date quarterly outcomes, which featured $11.35 billion in income, exceeding Wall Street’s projections on each the highest and backside strains. Analyst response to the Dreamforce bulletins was additionally favorable, with Stifel elevating its value goal for Salesforce, Inc. (NYSE:CRM) to $300 from $275 whereas reaffirming a Buy score, citing six distinct income channels laid out by the corporate for monetizing its new AI stack, together with further core licenses, premium SKU upgrades, Agentforce spending, Data 360, Agent Fabric and Guardian, and APIs, MCPs and associated transport systems.