Yields prime 5 %: American Equity says it is time for this underappreciated portfolio decide
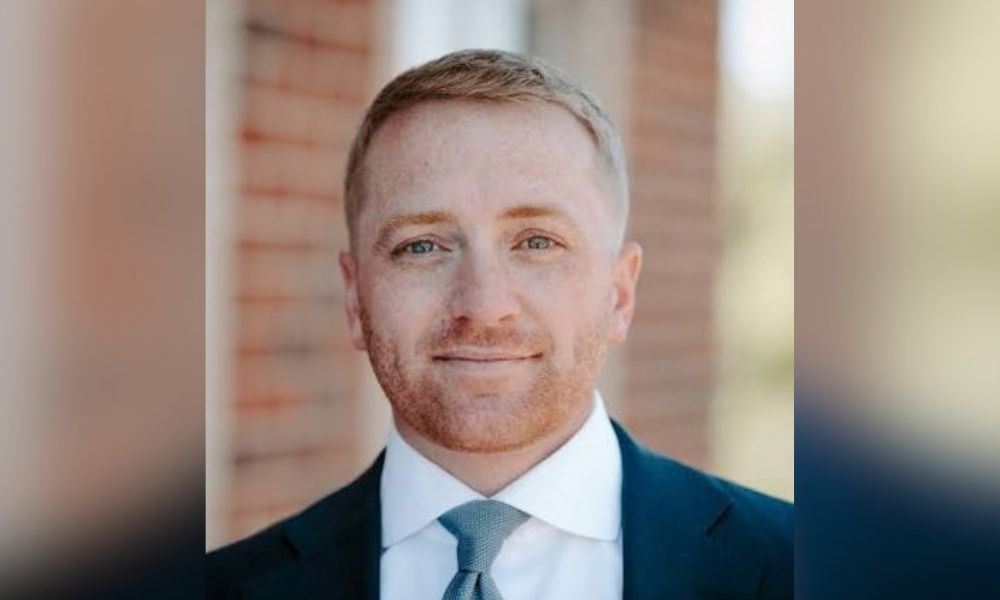
Daniel Biagini, senior vice chairman and head of unbiased gross sales, American Equity
American Equity’s Daniel Biagini, ART e-book, says rising charges make fastened index annuities extra aggressive than ever, and unlock capital for shoppers’ development portfolios
On Sept. 14, 2026, the U.S. 10-year Treasury yield broke 5% for the primary time since 2023, and on Sept. 30 held close to 5.23% for the primary time since 2007; the recent bond market, paired with excessive and undeterred fairness valuations, have garnished uncommon skepticism upon defaulting to inventory investments.
American Equity Investment Life Insurance Company sees this Treasury second as another excuse, amongst others, for advisors to revisit assured retirement earnings with a recent outlook.
Daniel Biagini, senior vice chairman and head of unbiased gross sales on the Des Moines, Iowa-based provider, stated he understands that annuities – buying and selling entry to wealth for longevity of wealth – usually are not on the desk for nearly each investor. “If you could have a consumer that’s extraordinarily averse to locking their cash up, or a portion of it… in the event that they need to be 100% liquid… an annuity shouldn’t be for them,” he stated.
But for shoppers who can settle for much less entry to their cash, Biagini stated immediately’s Treasury market features a distinctive benefit. Using the 10-year yield as an annuity worth benchmark, he reads its climb previous 5% as a transparent signal of alternative – the upper that yield rises, the extra upside carriers can construct into the earnings and development options they provide patrons. That dynamic makes annuity pricing run reverse to most shopper finance – whereas falling charges reward owners who refinance a mortgage, charges anticipated to rise reward retirees who convert savings into income.
“When rates of interest rise, our merchandise get extra aggressive and provide you with extra upside,” Biagini stated. “So, you nearly need to refinance your retirement.”
The Federal Reserve kicked off a mountaineering cycle in mid-September, and swaps merchants now worth in almost a full share level of additional will increase over the approaching yr. Buyers already spent a report $464.1 billion on annuities in 2025, together with $127.9 billion on fastened index annuities (FIAs), in keeping with LIMRA’s U.S. Individual Annuity Sales Survey.
Additionally, annuities supply three extra traits shares can not – they pay a assured earnings for so long as the consumer lives, so the consumer can not outlive it. Market losses can not cut back the principal in a set or fastened index annuity. And as a result of the annuity covers a part of the consumer’s earnings, the consumer can preserve the remainder of the portfolio available in the market for development – and even take extra danger with it.
“There hasn’t been a greater time in my lifetime within the annuity market to get into these merchandise due to the upside that they are offering, given the interest rate surroundings we’re in,” Biagini stated.
How the ART framework kinds retirement danger, amid the social safety surroundings
American Equity, which sells solely fastened and glued index annuities (FIAs), constructed its 2026 e-book for monetary professionals, The ART of managing earnings danger, round three decisions: Avoid, Retain or Transfer danger. According to their research: shoppers who keep away from danger maintain Treasurys and certificates of deposit (CDs); shoppers who retain danger maintain diversified portfolios and draw down at a protected withdrawal fee; shoppers who switch danger hand a part of it to an insurer via an annuity that ensures earnings.
Biagini stated that the center highway, the retain bucket, alone can not deal with the danger retirees concern most. “When you take a look at a portfolio holistically, most portfolios can diversify away from market danger. But what most portfolios cannot do is diversify away from longevity danger,” he stated. “We’re actually making an attempt to give attention to that idea, that retirement’s now not an asset allocation drawback; it is an earnings design drawback.”
Only 15% of personal business staff had entry to a pension as of 2024, in keeping with US Bureau of Labor Statistics knowledge. The 2026 Social Security Trustees Report tasks that the mixed trust funds will pay simply 83% of scheduled advantages as soon as reserves run dry in 2034, except Congress acts.
Withdrawal math provides little extra consolation: Morningstar‘s 2026 State of Retirement Income analysis places the very best protected beginning withdrawal fee at 3.9%, with a 90% probability that the portfolio of property will final 30 years. By means of analogy: instructed an airplane would have a 90% probability of touchdown safely, Biagini stated he would get off of that airplane; given the instructed odds of the belief fund’s success, he calls withdrawals past these 30 years “hope cash.”
“Would you moderately hope or know?” he stated. “With an annuity, you may know that you simply’re not going to expire of cash.”
Transferring danger frees capital for development
To generate $15,000 a yr at age 65, a consumer who avoids danger wants $333,333 in a 10-year Treasury yielding 4.5%; a consumer who retains danger wants $375,000 in a diversified portfolio drawing 4%. A hypothetical FIA with a ten% easy roll-up earnings rider wants $209,790 after a one-year deferral, or $141,844 after 5 years. By American Equity’s calculation, the one-year switch route leaves $165,210 {that a} consumer can reinvest to combat inflation.
Those figures assume a 4.5% Treasury yield, and better charges assist the keep away from bucket too: at 5.17%, a Treasury wants roughly $290,000 to supply the identical $15,000, by InvestmentInformation’ calculation.
The e-book’s hypothetical 64-year-old retiree, “Kristen”, applies the identical logic to a $1 million portfolio. Shifting $400,000 of fastened earnings into an FIA cuts her fairness withdrawal fee to 2.73% and raises her projected chance of success from 66% to 99%. Biagini stated that assured slice offers shoppers room to take extra danger with the remainder of their investments.
Planning software program brings annuities to fee-based advisors
Carriers initially designed their annuities merchandise for insurance coverage brokers. But since about 2016, broker-dealer representatives and fee-based advisors have taken a rising share of the trade. Biagini stated the fintech planning software most advisors run now fashions annuities contained in the consumer portfolio. That change places the burden on carriers to get their merchandise onto the platforms and to show them precisely. Investors arrive higher knowledgeable too: Biagini stated AI tools like ChatGPT now point do-it-yourself savers towards assured earnings with higher frequency than typical knowledge-holders. American Equity pairs its e-book with an Income Quick Quote Calculator, which fashions a consumer’s assured earnings by age and premium.
Biagini names the trade-offs plainly. “The catch could also be a charge. Not at all times, however perhaps,” he stated. Most FIAs enable 10% in free withdrawals annually, he added; American Equities e-book retiree, Kristen, assumes a 1.20% annual charge for the lifetime earnings rider.
Yet with equities close to all-time highs on the AI growth and yields at a 19-year excessive, Biagini urges advisors to lock a part of shoppers’ market good points into assured earnings earlier than the market turns.
“It is likely to be a good suggestion to take some cash off the desk and shield it if and when the market modifications route,” he stated.