Is the AI-fueled bull market taking its last breaths?
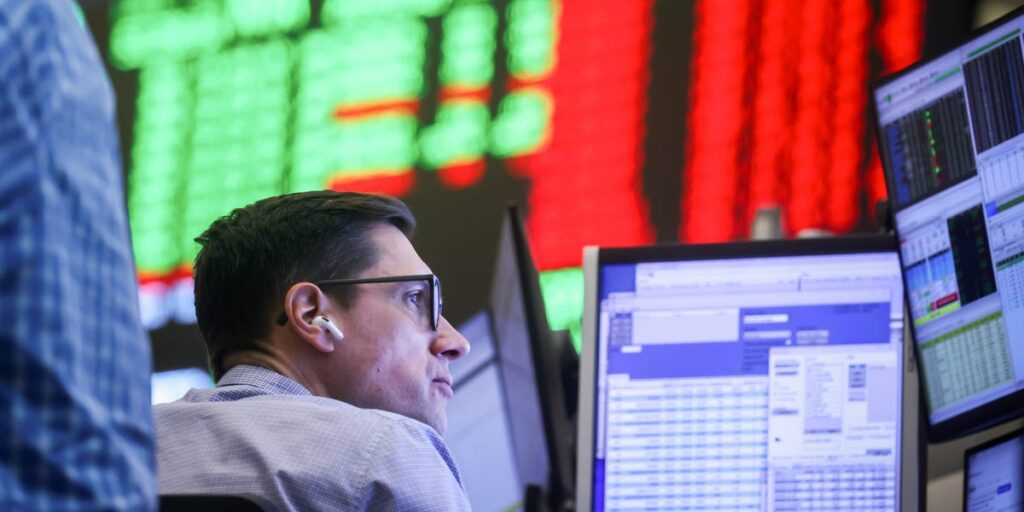
That’s the question on investors’ minds after the Nasdaq 100 plunged on Thursday, falling 6% and entering into a technical correction.
The decline marks one of the most painful sell-offs investors have seen in over a year, with investors dumping AI names and fleeing tech broadly as concerns grow about AI capex and whether the data center boom will hold up when Democrats take power in Congress and across the US next year.
The Nasdaq 100 briefly slipped into a correction on Monday, having fallen 10% below its early October peak. The index is now down 14% from its high in early October.
(function(){function e(){window.addEventListener(`message`,function(e){if(e.data[`datawrapper-height`]!==void 0){var t=document.querySelectorAll(`iframe`);for(var n in e.data[`datawrapper-height`])for(var r=0,i;i=t[r];r++)if(i.contentWindow===e.source){var a=e.data[`datawrapper-height`][n]+`px`;i.style.height=a}}})}e()})();
It marks the Nasdaq 100’s third correction of 2026. Most of the pain was concentrated in areas related to AI infrastructure, including neoclouds, semiconductors, and data center operators. The iShares Semiconductor ETF, notably, was on track for its worst day since 2020.
In recent weeks, the risk-off narrative appears to have splintered in a few directions, with markets simultaneously concerned about too little AI spend, too much AI spend, and whether the hype around AI will prevail given uncertain demand and how high valuations have climbed this year.
Here’s what smart people in markets are saying about the correction.
"Not a buying opportunity by any means"
A television broadcasts Texas Senate election results on the floor of the New York Stock Exchange
Michael Nagle/Bloomberg via Getty Images
David Bahnsen, the chief investment officer of The Bahnsen Group, said the latest decline in stocks shouldn’t be taken as an invitation for investors to buy at a discount.
In a note, Bahnsen said his firm is looking to avoid the tech sector completely and pile into defensive areas of the market like consumer staples and energy.
“This tech-led correction is driven by valuations that became completely disconnected from reality,” Bahnsen, whose firm manages $11 billion in assets, said. “Even with the Nasdaq correction, valuations in the tech sector still remain way too high, and this is not a buying opportunity by any means.”
AI bubble popping would entail at least a 30% stock crash, TS Lombard says
Dario Perkins, a strategist at TS Lombard, outlined what the forecasting firm believed was the most likely chain of events if the AI bubble pops. Should the AI trade collapse, it would entail a market crash of at least 30% in the US, Perkins wrote in a client note as the tech sell-off accelerated.
Here are the firm’s other predictions, assuming a scenario where the AI bubble bursts:
The US market loses around $20 trillion in market cap.
The crash produces “significant ramifications” in debt markets and private credit, producing as much as $200 billion in losses.
Credit spreads widen, resulting in a wave of defaults in teh tech sector. “The weakest players in the AI ecosystem,” which include neocloud firms and Oracle, would be faced with “acute distress.”
The US inevitably enters a cyclical downturn as capex spending craters.
The construction sector, which has been supported amid the AI boom, woud see “sizeable job losses,” though the US economy overall will likely recover quickly, Perkins said.
The sell-off has been partly triggered by economic concerns: David Rosenberg
Investors fear that the Democratic sweep could impact the data center boom.
Jon Cherry/Getty Images
Top economist David Rosenberg said the sell-off in markets this week is being partly fueled by anxiety that the US economy could also be hurt if data center investment slows. Rosenberg, a prominent market bear, has expressed skepticism about US economic growth in recent quarters, noting that much of the GDP growth was driven by data center construction.
“The question becomes the economic impact as we see, at the least, a pause in the data center construction mania,” he wrote in a note to clients on Thursday.
Earlier this week, Rosenberg said correction was “probably inevitable” given the huge volume of capital pouring into “any company claiming to have an AI angle.”
The former chief North American economist at Merrill Lynch said that “both sides of the AI trade are faltering at once.” The likes of Microsoft and Alphabet have sold off because they’re spending too much and eroding their cash flows, he continued, while their suppliers have sold off because “spending isn’t speeding up.”
“The overriding theme is that investors stopped rewarding the AI buildout and started asking when it pays back,” Rosenberg added.
KPMG eyeing a bear market
Diane Swonk, the chief economist at KPMG, said her team was working on two projections for the US economy over the last week. The first scenario is one where financial markets “wobble” without a larger crisis. The second scenario is a bear market that leads to the burst of the AI bubble, she wrote in a post on X amid the tech sell-off Thursday.
“The bear market scenario triggers a faster & deeper recession than the dot com bust in 2001. It derails inflation & the Fed cuts more aggressively to mitigate the pain. Consumer spend is hit harder than investment initially,” Swonk wrote, adding that it’s been an “ugly month” for equities.
US stocks ended October bearing deep losses. The Nasdaq 100 fell nearly 7% to end the month. The index, though, remains a long way from bear market territory, which is defined as a 20% drop from a recent peak.
The S&P 500 is flashing a rare omen
Michael Nagle/Bloomberg via Getty Images
Ned Davis Research flagged a rare signal flashing in the S&P 500 in the last week amid the tech sell-off: The index’s price-to-forward earnings ratio, a valuation metric that measures the price of the S&P 500 relative to the 12-month forward earnings expectations for companies in the index, has dropped sharply, falling by 4.4 points in the year through October, NDR wrote in a note to clients.
A decline of that magnitude is rare, having only occurred six times since 1983, Ed Clissold, NDR’s chief US strategist, said.
Though the index was up over the next year in five out of the six instances, the S&P 500’s average median drawdown in the year that followed was around 18%, implying that stocks tend to see “some pain along the way” after the forward P/E plunges, he said.
“History suggests that if an AI slowdown leads to a recession, the recent drop in the P/E may not prevent significant drawdowns,” NDR wrote.
Questions swirling around the strength of the US economy, Mohamed El-Erian says
Top economist Mohamed El-Erian raised concerns about how a slowdown in AI capex could impact economic growth. Data centers have accounted for a large share of GDP growth and job growth in the last year, while other sectors of the economy have been more lackluster.
“What I’m less sure about is can the rest of the economy prosper if AI gets a real hit? We are really levered on AI right now,” the Allianz chief economic advisor said, speaking to CNBC on Thursday.
The sell-off also appears to be a “timely warning” about the dangers of turning away from globalization, El-Erian said, referring to how much of economic growth recently has been fueled by US data center construction.
“I am completely bullish on the tech sector, on what AI will do for the economy. But I do think we needed to course-correct a little bit, how it was being pursued,” El-Erian.
Look next at the S&P 500's 200-day moving average: Andrea Lisi
Michael Nagle/Bloomberg via Getty Images
Andrea Lisi, a strategist and the founder of Lisi Quant Analysis, said she was eyeing if the S&P 500 breached its 200-day moving average of 7,320. The 200-day moving average is a key technical level in markets that, if breached, suggests stocks are seeing severe downside momentum.
“That’s the line to watch from here,” Lisi wrote in a post on X about the Nasdaq’s correction this week.
Investors are reducing exposure to AI trade
Fund managers are “just reducing overall exposure” to the AI trade as it’s turned “ugly,” Neil Wilson, investor strategist at Saxo UK, told Business Insider by email on Tuesday.
Wilson pointed to Morgan Stanley data through late October showing that equity long/short hedge funds experienced their biggest gross-flow drawdown since the investment bank started tracking them in 2016.
He said there’s “definitely a lot more scrutiny” on returns from AI investments, flagging that some recent hyperscaler earnings showed negative cash flows due to heavy spending on AI equipment.
Political gridlock is weighing on sentiment: The Kobeissi Letter
The correction in tech stocks reflects not just concerns about AI spending hurting profits, but investors “pricing in two years of political gridlock,” The Kobeissi Letter, an industry commentary, said in an X post on Monday.
The newsletter pointed to President Trump vowing to be “Mr. Veto” if Republicans cede control of the House and Senate.
A stock sell-off could become a bigger economic problem
Stephanie Keith/Bloomberg/Getty Images
A sustained decline in stocks could erode household wealth and weigh on consumer spending, compounding economic pressures from higher oil prices, weak real income growth, and rising bond yields, BMI Research warned.
“The risk is that the sell-off morphs into something much more aggressive which would put significant downside pressure on the global economy,” wrote Cedric Chehab, the chief economist, at BMI, in a Friday report.
So far, the stock market sell-off has had limited impact on other financial markets. However, further declines could lead to greater stress in credit markets and a stronger dollar, increasing risks to the broader economy, Chehab wrote.
Slower AI spending could actually be good for the boom
A slowdown in AI infrastructure spending could make the investment boom more sustainable rather than bring it to an end, according to James Thorne, the chief market strategist at Wellington-Altus.
Thorne sees the sharp sell-off as more a reflection of deteriorating investor sentiment and excessive leverage than evidence of collapsing AI demand.
A more measured pace of data center construction could ease pressure on credit markets, electricity prices, and inflation, while improving cash flow for major technology companies, he wrote on X.
“Even slower capital spending would not invalidate the investment case. It could improve it,” Thorne wrote.
A correction, not the end of the bull market
The sharp stock market sell-off may be a correction in a longer bull market rather than the end of the AI investment boom, according to John Woods, chief investment officer for Asia at Lombard Odier.
“I think this is more positional than fundamental,” Woods told Bloomberg TV.
“I ask myself, is the AI story over, and I can’t get a firm sense that it is,” he added.
Uncertainty over potential Democratic restrictions on data center development is also weighing on sentiment. However, Woods believes the severity of the sell-off could prompt policymakers to soften their proposals.
AI could change the world and still be a bad investment
AI’s transformative potential doesn’t necessarily mean companies pouring billions into the technology will deliver strong returns for investors, according to David Allen, head of long/short strategies at Plato Investment Management.
Allen drew a parallel with the airline industry, which transformed travel but historically struggled to deliver strong investment returns. Like airlines, AI infrastructure requires enormous capital spending and faces significant regulatory risks.
“The big hyperscalers have been locked in an existential battle from their perspective. Each of them thinks they need to outspend the other, just to survive, but I think the market’s really testing the limits of that now,” Allen told Bloomberg TV.