Trump Accounts face midterm take a look at as guidelines shift, warns Focus exec
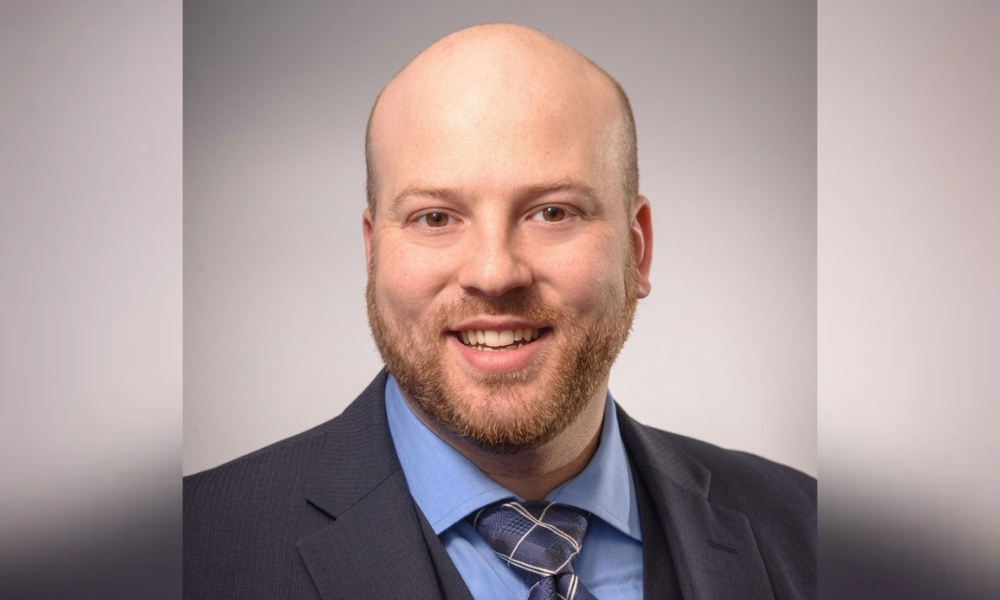
Focus Partners Wealth’s Jeffrey Levine says a Democratic House or Senate would make new laws on Trump Accounts a lot more durable to cross
Trump Accounts are drawing sturdy shopper curiosity, however households saving for school ought to nonetheless lean on 529 plans, in accordance with Jeffrey Levine, chief planning officer at Focus Partners Wealth.
The Treasury Department just lately mentioned it had completed automatic enrollment for Trump Accounts, giving each eligible youngster below 18 with a sound Social Security quantity an account. Parents should nonetheless declare it via Treasury’s app earlier than including cash, and households of youngsters born from 2025 via 2028 should individually elect the $1,000 federal seed.
On Oct. 7, the Trump administration’s mentioned roughly 70 million children are actually enrolled. Temporary Treasury laws issued in late September 2026 additionally opened the door to donations of publicly traded U.S. inventory to teams of not less than 5,000 youngsters, with the shares held for 5 years.
Focus Partners Wealth is a part of Focus Financial Partners, which stories greater than $500 billion in collective shopper belongings, 6,300-plus group members and 300-plus accomplished M&A transactions.
Levine mentioned the free cash is the draw, however the funding mechanics confuse purchasers – notably as rules for employer contributions of up to $2,500 a year are finalized.
“But there’s been loads of confusion, particularly in regards to the contributions to those accounts, as a result of there’s about 5 completely different contributions. You can have your personal contributions, employer contributions, the government-sponsored contribution of $1,000, and even contributions from charities,” Levine told InvestmentNews.
JPMorgan Chase, Intel, and Steak ‘n Shake, Robinhood and Schwab are among the many main corporations to decide to matching contributions to Trump accounts for his or her staff. The most typical query, Levine mentioned, is how Trump Accounts fit alongside 529 college savings plans.
“The school funding problem continues to be higher solved normally by the 529 as a result of it supplies for these tax-free distributions for greater training bills. Distributions from these Trump Accounts, whereas they could be obtainable as soon as the kid turns 18, they’re nonetheless going to be taxable normally,” Levine mentioned.
Levine , and administrative motion can hinder on upcoming election outcomes.
“The administration has completed loads of finagling proper now, even on simply administrative rulings. For occasion, they weren’t presupposed to have shares, however now corporations can contribute shares, and folks will even have to carry them of their accounts in the event that they obtain them. So I feel a few of it will likely be completed administratively,” mentioned Levine. “The different a part of that is going to depend on what occurs within the election, as a result of if Democrats find yourself taking both the House or the Senate or each of these, then it’s going to be loads more durable to cross laws associated to Trump Accounts just because I don’t assume Democrats will play a lot ball there.”
Even so, he urged purchasers to not reposition portfolios across the November 2026 midterms. “Your long-term plan needs to be your long-term plan, it doesn’t matter what,” he mentioned.
For year-end 2026, Levine is checking for tax-loss harvesting, Roth conversions, earnings dips relative to subsequent 12 months and last-minute charitable presents.
“So a lot of tax planning is about push and pull, push and pull of earnings, push and pull of deductions,” he mentioned, noting that purchasers can pull gadgets ahead or push them into 2027. “At the tip of the sport, it’s the one that pays the bottom lifetime taxes that wins the sport, not essentially simply the bottom tax invoice this 12 months,”