The monetary trade has a saving downside
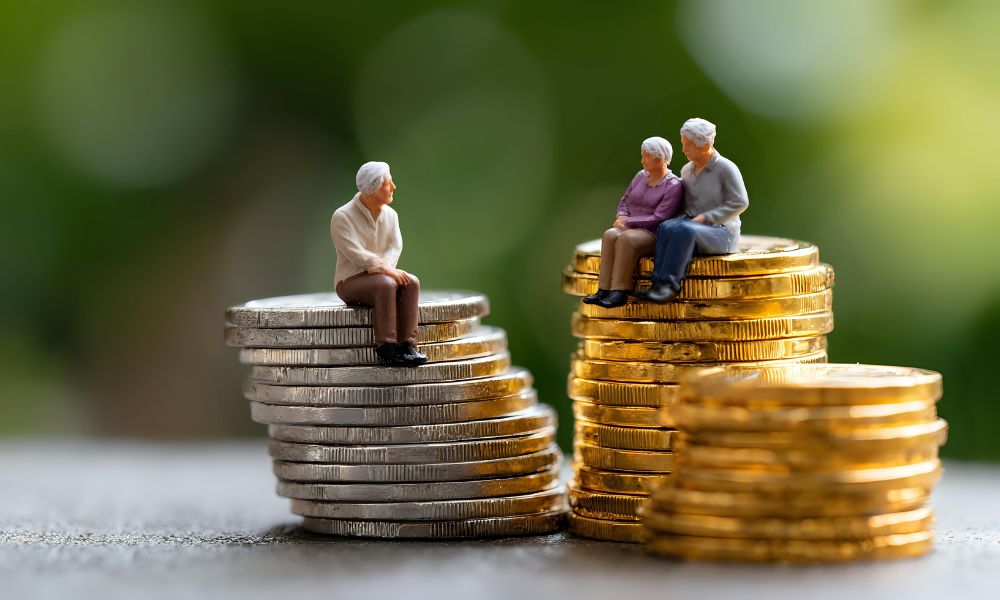

After years of encouraging sacrifice and delayed gratification, advisors need to do the subsequent emotional raise: serving to shoppers let go of a doubtlessly dangerous shortage mindset.
Early in my profession, I seen one thing that has by no means stopped bothering me. I might sit throughout from shoppers who had carried out every thing proper. Just just lately, a consumer instructed me, “I would like you to indicate me that I can spend.” She had spent her total life saving as a result of that is what she was taught to do. She had greater than sufficient cash to help her life-style, however the concept of spending it on herself nonetheless felt mistaken.
Not as a result of they have been careless. Because each advisor that they had ever labored with had instructed them the identical factor, save extra.
The monetary companies trade has largely been constructed round that one message. Save extra for retirement, for healthcare, for your loved ones, for uncertainty. Some of that recommendation is completely crucial. The Federal Reserve discovered that solely 35% of non-retirees imagine their retirement financial savings are on observe. Disciplined saving issues.
But for households who’ve already constructed vital wealth, that very same message begins doing actual harm. For many individuals, that worry turns into most obvious at retirement, when the lifelong behavior of incomes and saving all of the sudden shifts to spending from property they labored many years to construct. They have loads. They simply can not deliver themselves to make use of it.
I see this particularly amongst industry homeowners and households whose wealth was constructed by means of sacrifice and delayed gratification. People who poured every thing into constructing an organization, a winery, a medical observe, or a household enterprise. They grew to become conditioned to imagine that monetary success meant preserving wealth in any respect prices. The result’s a shortage mindset that persists lengthy after shortage is not the truth.
Behavioral economists have long documented that folks expertise monetary losses way more intensely than features, even when objectively safe. So, they postpone experiences they’ll already afford. They delay journey, time with kids and grandchildren, and selections that will genuinely enhance their lives. Recently, I labored with a widow in her 80s who was contemplating a transfer to a retirement group she beloved. She might comfortably afford it, however struggled with the thought of spending that a lot on herself. Her problem wasn’t monetary. It was emotional.
I’ve labored with households navigating sudden sickness, sudden deaths, and main liquidity occasions. One lesson turns into painfully clear. That tomorrow isn’t assured, and too many individuals await a future they assume will at all times be there. Recent retirement research discovered that retirees usually spend solely about half of what they may safely withdraw.
However, that doesn’t imply that we should always all be spending recklessly. There’s a possibility for people to spend confidently once they have a transparent plan. Often, which means serving to shoppers perceive the tradeoffs. We mannequin totally different spending eventualities, establish what they wish to depart behind for household or charitable causes, and set up guardrails that enable them to take pleasure in their wealth whereas nonetheless assembly these objectives. In many circumstances, shoppers uncover they’ll spend excess of they thought and nonetheless depart a significant legacy.
When shoppers can see how their investments, taxes, property planning, money circulation, and long-term objectives match collectively, their relationship with cash modifications. The query shifts from “Can I afford this?” to “Does this help the life I really wish to construct?” That means taking the household journey now as a substitute of ready one other decade or serving to kids purchase their first house whereas mother and father are alive to see it.
In Napa Valley, the place a lot of my work facilities on households with illiquid wealth tied to vineyards, land, or intently held corporations, these conversations are particularly emotional.
Their industry is extra than simply an asset. It’s their identification, their household historical past, and their life’s work. I more and more see households wrestling with whether or not the subsequent technology even needs that life, and that realization forces a deeper query about what the wealth was really meant to perform.
After practically thirty years on this industry, I can let you know that shoppers hardly ever look again wishing that they had saved barely extra. What I hear extra usually is that they want they hadn’t waited. Waiting to journey. Waiting to decelerate. Waiting to spend time with the folks they love. Waiting for permission to benefit from the life they spent many years constructing.
The greatest monetary plans mustn’t merely defend wealth. They ought to assist folks stay extra totally due to it.
George McCuen, CFP, CPWA, joined The Mather Group as a wealth advisor in November 2025 following the merger of Napa Wealth Management. A Napa native, he has spent practically three many years working with prosperous households, industry homeowners, and multi-generational households.
The Mather Group, LLC (TMG) is registered underneath the Investment Advisers Act of 1940 as a Registered Investment Adviser with the Securities and Exchange Commission (SEC). Registration as an financial backing adviser doesn’t suggest a sure degree of ability or coaching. For an in depth dialogue of TMG and its financial backing advisory companies and charges, see the agency’s Form ADV on file with the SEC at www.adviserinfo.sec.gov, or on the agency’s web site at www.themathergroup.com. The opinions expressed, and materials offered are for normal info and shouldn’t be thought of a solicitation for the acquisition or sale of any safety. The opinions and recommendation expressed on this communication are primarily based on TMG’s analysis {and professional} expertise and are expressed as of the publishing date of this communication. The info and knowledge on this communication doesn’t represent authorized, tax, accounting, financial backing, or different skilled recommendation.