A pair retiring at 62 with $1.4 million paid near-zero federal taxes for 8 years by sequencing taxable, IRA, and Roth accounts strategically.
Converting between $60,000 and $70,000 yearly to Roth whereas staying contained in the 12% bracket saved their tax invoice within the single-digit 1000’s and maximized tax-free development.
Delaying Social Security to 70 added 8% per 12 months to their lifetime profit whereas the Roth conversions prevented Medicare IRMAA surcharges above $218,000 MAGI.
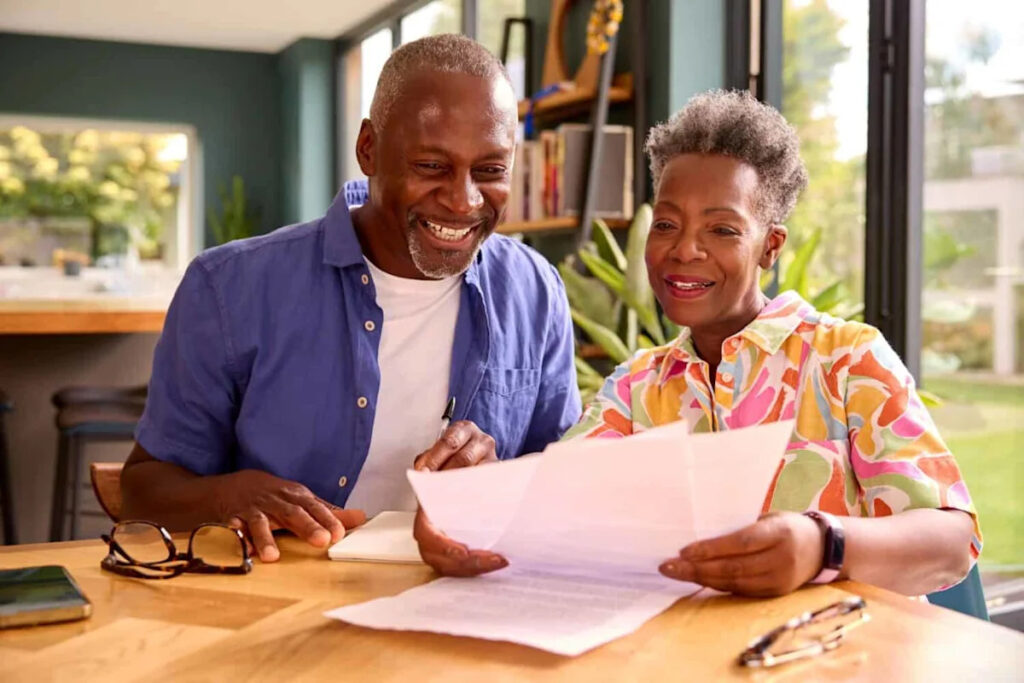
A Bogleheads thread final spring described a pair who retired at 62 in 2018 with roughly $1.4 million cut up throughout a taxable brokerage, a standard 401(ok), and a small Roth. Eight years later, that they had paid nearly no federal revenue tax, transformed a big share of the 401(ok) to Roth, and had been about to file for Social Security at 70 with a maxed-out profit. The trick was a deliberate sequencing technique constructed across the hole years between retirement and required minimal distributions.
Monkey Business Images / Shutterstock.com
Why the 62-to-70 Window Is the Most Valuable Tax Real Estate You Will Ever Own
Once Social Security and RMDs each swap on, atypical revenue turns into largely involuntary. Before they do, a retired couple controls nearly each greenback that hits their 1040. That management is what makes the eight years between early retirement and age 70 the only most vital tax-planning window in a saver’s life (we sized up that quiet window, and use it, in a free Roth information right here: The Roth Window).
For a married couple submitting collectively, the 12% bracket runs from $23,851 to $96,950 of taxable revenue in 2025, with the 22% bracket kicking in at $96,951. Stack the usual deduction on prime and a pair can acknowledge roughly $120,000 of gross revenue earlier than touching the 22% fee. That headroom is the uncooked materials for the technique.
Learn 7 Secret Wealth Tips High Net Worth Investors Use
How do you proceed to develop a seven-figure portfolio in retirement? The last item you need is to expire of cash, you need your cash to generate lasting revenue whilst you get pleasure from your life.
Their $1.4 million was cut up roughly $600,000 in a taxable brokerage with a low value foundation, $700,000 in a standard 401(ok) rolled to an IRA, and $100,000 in a Roth. Each 12 months from 62 to 70 they did three issues in sequence.
Spent from the taxable account first. Long-term capital good points sit in a separate fee schedule. A married couple with taxable revenue beneath roughly $96,000 pays 0% on certified dividends and long-term good points. Selling appreciated shares to fund $60,000 of residing bills generated nearly no federal tax as a result of the realized achieve fell contained in the 0% bracket.
Ran a Roth conversion ladder to the highest of the 12% bracket. With no wages and no Social Security, they transformed roughly $60,000 to $70,000 a 12 months from the standard IRA to the Roth, maintaining whole taxable revenue just below the $96,950 prime of the 12% bracket. Federal tax on the conversion ran within the single-digit 1000’s, and each transformed greenback grew tax-free thereafter.
Delayed Social Security to 70. Each 12 months of delay previous full retirement age provides 8% to the profit for all times, and the delayed profit compounds with the annual COLA. The 2027 COLA is at present monitoring towards 3.3%, which lifts the eventual examine even earlier than they declare.
How They Sidestepped the IRMAA Trap
Roth conversions are the piece most retirees botch, as a result of Medicare makes use of a two-year lookback on modified adjusted gross revenue. In 2026, a joint filer with MAGI at or under $218,000 pays the usual Part B premium of $202.90 a month, whereas crossing that first threshold pushes the entire to $284.10. Higher tiers escalate rapidly, reaching $689.90 a month per particular person at $750,000 of joint MAGI. By capping conversions contained in the 12% bracket, the couple stayed a number of tiers under the primary IRMAA cliff after they lastly enrolled in Medicare at 65.
What the Cash Buffer Looked Like
The plan solely works in the event you don’t have to promote shares in a foul 12 months to eat. They held roughly two years of spending in short-duration Treasuries and CDs. That is simpler to construct immediately than it was a decade in the past: the 10-year Treasury yield is round 5%, and even the FDIC nationwide common 12-month CD sits at 1.73%, with prime on-line banks paying a number of occasions that.
Three Moves to Copy Before Year-End
Model your bracket, not your stability. Pull your projected 2026 taxable revenue and calculate what number of {dollars} of Roth conversion match beneath the $96,950 prime of the 12% bracket for joint filers. That quantity is your annual conversion goal.
Separate your good points out of your conversions. Do capital-gain harvesting in years you skip the conversion, and vice versa. Stacking each in the identical 12 months can push you into the 22% bracket and the 15% capital-gains bracket concurrently.
Watch the IRMAA lookback beginning at 63. Any MAGI within the 12 months you flip 63 units your Medicare premium at 65. If your projected joint MAGI is inside $10,000 of $218,000, shrink the conversion. The premium soar prices greater than the conversion saves.
Learn 7 Secret Wealth Tips High Net Worth Investors Use
How do you proceed to develop a seven-figure portfolio in retirement? The last item you need is to expire of cash, you need your cash to generate lasting revenue whilst you get pleasure from your life.