Split Your Direct Deposit – Pay Savings First and Let Checking Take the Rest
Just the Tip:
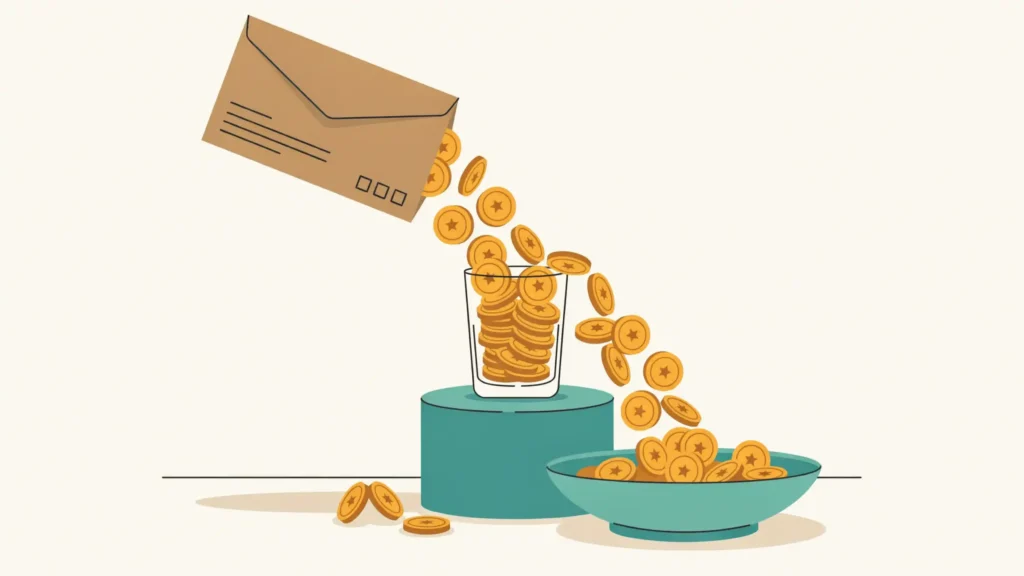
If your employer allows it, set up a split direct deposit that sends a fixed amount of every paycheck to savings and the rest to checking. Most payroll systems pay the fixed amount first, so savings gets funded before you can spend it, and a short paycheck shrinks your spending money instead of your savings.
Saving whatever is left at the end of the month rarely works, because money in checking gets spent, so automating your savings with a transfer the day after payday does better. But that transfer draws on the same balance as your rent and card payments, so in a tight month it’s the easiest one to cancel.
A split direct deposit pays savings before checking ever sees the money. Most payroll systems send fixed-dollar amounts first, in the order you set, then route whatever remains to one remainder account. Give savings the fixed amount and checking the remainder, never the reverse, because the remainder is the account that shrinks when a paycheck comes up short.
On a $2,000 paycheck, a $200 fixed amount goes to savings and $1,800 lands in checking. If a short week cuts the paycheck to $1,700, savings still gets $200 and checking gets $1,500. Size the fixed amount against your smallest paycheck, since a paycheck smaller than the fixed amount leaves checking with nothing.
The setup takes about 15 minutes:
- Find the routing and account numbers for your savings account in your bank’s app or online banking.
- Open the direct deposit page in your payroll portal, or ask HR for the paper form.
- Add savings as a fixed-dollar amount, set checking to receive the remainder (some systems call it the balance or remaining pay), and confirm savings is paid first.
- Check your next two pay stubs, since a change can take a pay cycle or two to kick in.
Not every employer allows a second account. If yours won’t split, the day-after-payday transfer is your fallback. Either way, a savings account at a different bank from your checking is harder to raid than one at the same bank.
When you get a raise, add part of it to the fixed amount before the first bigger paycheck lands. That way part of the raise goes to savings before you get used to spending it.
For the account that gets the fixed amount, compare the best high-yield savings accounts.
Make & Save More Money, Spend Less Time

One money tip, every morning
Join 50,000+ readers. Actionable, free, no nonsense – just the tip.
No spam, ever. Unsubscribe anytime.
Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related: