SEC floats CFP path to accredited investor standing, fund guidelines refresh amid personal market push
Among different updates, the proposals would let advisors to regulated funds earn efficiency charges and permit interval funds to supply month-to-month repurchases.
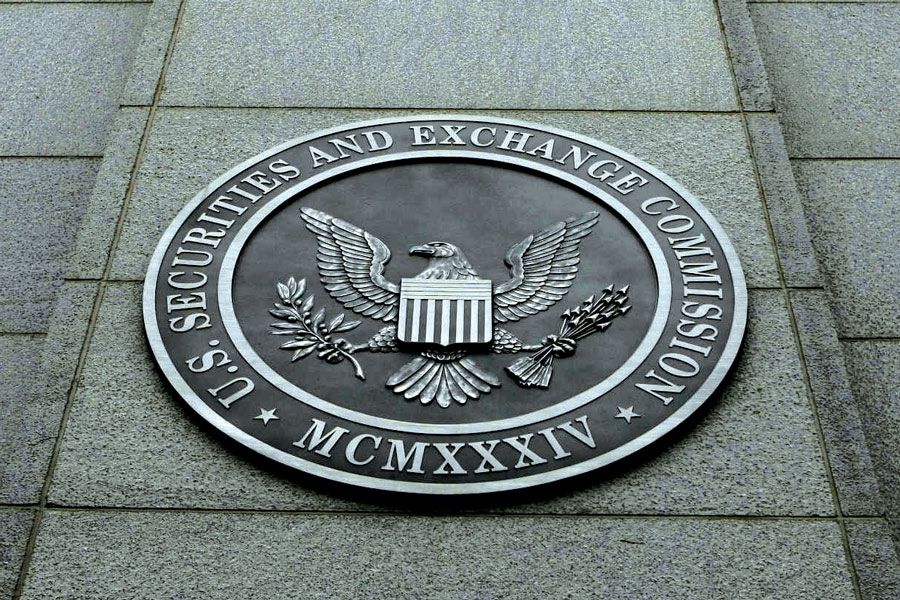
The Securities and Exchange Commission is weighing whether or not to let Certified Financial Planners, CFA charterholders and CPAs qualify as accredited buyers, in addition to develop guidelines governing performance-based charges and liquidity inside sure interval fund buildings.
The concept is a part of a broader federal push to maneuver private-market methods into funds offered to odd buyers.
On Wednesday, the fee voted to suggest rule amendments that develop retail investor selection and promote innovation in regulated fund buildings. One of the formal rule proposals would widen the circumstances through which registered asset placement advisors could accumulate efficiency charges, whereas the opposite overhauls the interval fund framework and makes it simpler for closed-end funds to supply a number of share courses.
At the identical assembly, the SEC individually requested public touch upon increasing the accredited investor definition to incorporate extra skilled certifications, designations or credentials.
“The Commission’s efforts on this regard – targeted on increasing alternatives for buyers’ post-tax, pre-retirement {dollars} – complement efforts undertaken pursuant to President Trump’s Executive Order on Democratizing Access to Alternative Assets for 401(ok) Investors,” mentioned SEC Chairman Paul S. Atkins.
Who might qualify as an accredited investor?
The accredited investor label controls entry to non-public placements. Today it rests totally on wealth exams: a person usually should earn greater than $200,000 a yr, or $300,000 with a partner, or have a internet price above $1 million excluding a main residence. Apart from these, the SEC has already designated the Series 7, Series 82 and Series 65 licenses as qualifying credentials.
The SEC is now contemplating 5 new routes to the accredited investor label: a U.S. CPA license, a CFA constitution, a CFP certification within the United States, the FINRA Series 79 asset placement banking license, and the FINRA Series 86 and 87 analysis analyst licenses.
The fee can be asking for touch upon an accredited investor examination that FINRA would develop, which might give buyers a non-financial technique to present they’re refined sufficient to guage a personal asset placement. If that involves go, it might make more clients who don’t meet the wealth tests eligible for private offerings, which implies extra advisor-client conversations round suitability.
“I agree with the basic notion ingrained in right this moment’s notices that accredited investor entry to non-public choices shouldn’t be restricted solely to people satisfying monetary thresholds and that such thresholds should not the only real indicators of an individual’s means to evaluate the deserves and dangers of an asset placement,” Atkins mentioned on the SEC assembly on Wednesday.
Performance charges transfer into registered funds
While performance-based pay has lengthy been a fixture in hedge funds and personal fairness – consider the “2 and 20” construction usually ascribed to conventional hedge funds – the SEC is considering amendments permitting asset placement advisers to regulated funds to earn performance-based compensation, with sure circumstances.
As defined in a fact sheet accompanying the proposed rule revisions, the performance-based compensation mustn’t exceed 20% of the fund’s internet positive aspects over a specified interval. The fund would even have to fulfill the governance requirements in Rule 0-1(a)(7). In addition, the fund’s board, together with a majority of unbiased administrators, must discover that the association is in shareholders’ greatest curiosity and make particular findings about its construction and investor safety options.
The proposals additionally search to revise the definition of “certified shoppers” to seize anybody who meets the accredited investor definition beneath Regulation D, whereas eliminating the separate internet price and assets-under-management exams. In apply, that may align eligibility for efficiency charges with eligibility for personal placements.
Funds would additionally must disclose efficiency charges of their registration and reporting types.
“Performance-based compensation can supply a rational and efficient means to outline and align adviser and investor targets,” Atkins mentioned.
Monthly liquidity for interval funds
Interval funds are a large and growing part of how advisors entry personal financial hubs. Research from Alternative Fund Advisors discovered that 80% of RIAs used interval funds as their fundamental automobile for personal credit score in 2025, up from 58% the yr earlier than.
The SEC pointed to restrictions within the present guidelines round interval funds. In explicit, rule 23c-3 permits repurchase gives solely on a quarterly, semiannual or annual schedule, and every supply should be between 5% and 25% of excellent shares.
The SEC’s proposal would add month-to-month intervals, permit extra frequent discretionary repurchases, and allow an extended delay earlier than a fund’s first repurchase supply. It would additionally let funds deduct deferred gross sales masses from repurchase proceeds, in sure circumstances, and substitute the rule’s mounted liquidity requirement with a principles-based method.
A separate piece of the proposal would let regulated closed-end funds supply a number of share courses and pay asset-based distribution and repair charges. It would additionally require enhanced expense disclosures throughout all regulated closed-end funds. That rules-based system would substitute the fund-by-fund exemptive orders sponsors at the moment must acquire.
“Taken collectively, these proposals are vital steps in direction of offering particular person buyers with extra entry to non-public market asset placement alternatives, together with by way of the registered fund channel,” Atkins mentioned.
The SEC has opened a 60-day remark interval on its proposed guidelines.