Husband and I Cannot Agree on How A lot to Save for International Transfer
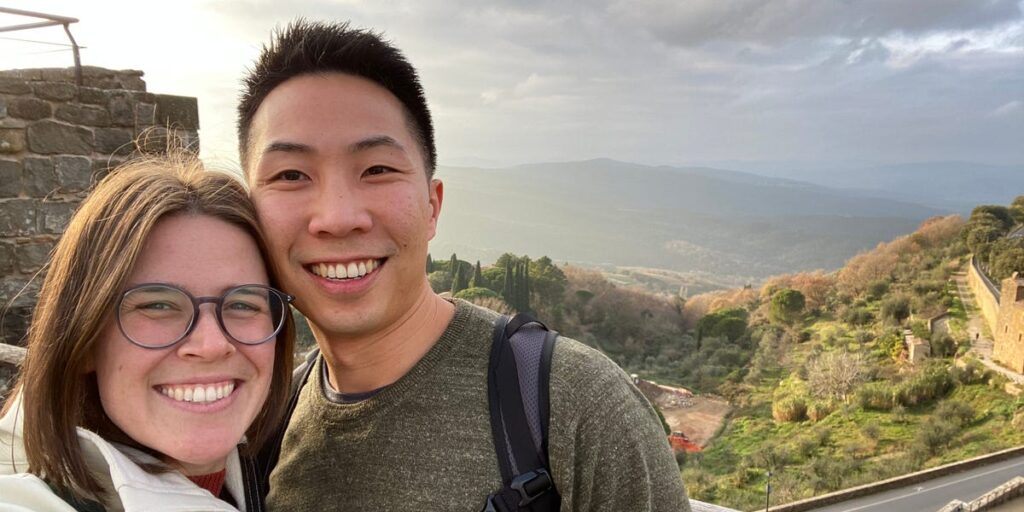
Over a 12 months in the past, my husband and I sat down in the lounge of the home we as soon as thought could be our “subsequent 30 years” house. We talked in regards to the future and set a aim: Before our son begins kindergarten, we’ll transfer to the Netherlands.
Everyone instructed us parenthood would change our priorities, however residing the method firsthand was nonetheless a shock. In late 2024, after the birth of our first kid, my husband and I each had the creeping feeling that the United States would not be our without end house.
By the time he first vocalized the thought, we had a kind of open-mouthed moments. We realized we would arrived on the similar conclusion with out ever discussing it.
It took a little bit of time to resolve the place we wished to maneuver. We’ve lived in California for our entire marriage and do not need to surrender sure luxuries now we have right here, like entry to quality healthcare and a various neighborhood.
However, there are specific issues we would like from a brand new house, too, like stricter gun restrictions and a special public-education system.
After a lot debate and analysis, the Netherlands checked all our containers after which some. We visited final 12 months and confirmed it: Moving right here was our aim.
Up till this level, we would agreed on the whole lot. Then, we began speaking in regards to the logistics … particularly, cash.
We’ve all the time had completely different attitudes towards cash
Allison Lau
When it involves most issues, my husband and I could make choices, come to simple compromises, and transfer shortly. However, it took us over a 12 months of marriage — and tons of conversations — to really feel snug merging our bank accounts.
My husband may be very money-literate and a little bit money-obsessed. Meanwhile, I’ll put cash into our financial savings account and promptly neglect about it.
He’s fascinated by corporate affairs, has sturdy opinions on investing, and constantly reevaluates our bigger wealth-building plan. I profit significantly from his fascination with cash, since none of that is my sturdy go well with.
Our aim to maneuver to the Netherlands has plopped us into one of many extra sophisticated discussions about cash that we have had in a decade of marriage. It boils all the way down to a key disagreement: He needs to construct wealth first, then transfer. I need to transfer, then resume constructing wealth.
He sees the Netherlands as a end line. I see it as our subsequent beginning line.
He needs to ‘retire’ to the Netherlands, however I need to begin contemporary
We deliberate to maneuver to the Netherlands by the Dutch-American Friendship Treaty (DAFT), which permits an innovator to maneuver a small corporate affairs to the Netherlands and work towards residency.
However, it appears tough to buy a house and not using a full-time job with a Dutch employer. The various, the rental market, is hard, too. Some leases require expats to pay a full 12 months (or two!) of lease completely up entrance.
According to my husband, there’s an apparent “finest” plan: save sufficient cash right here within the US so we are able to purchase a home, with money, within the Netherlands.
Now, now we have a younger son, and we’re pregnant with child quantity two. A livable condo for a household of 4 would price anyplace between 450,000 euros and 600,000 euros. In USD, this is able to imply we would simply be spending over $500,000 on the low finish — seemingly rather more.
We handle our cash effectively, however we do not have that type of cash. And between our present mortgage, the cost of childcare for 2 youngsters, and the final excessive price of residing in Northern California, it is arduous to see that altering over the following two or three years.
My proposed resolution? We transfer now and begin off as renters. A full 12 months of lease for a livable two-bedroom condo within the coveted Ramstand space of the Netherlands would run us about 24,000 euros, or about $28,000.
This manner, we may proceed to construct our wealth within the Netherlands. Jump, and determine it out as we go.
That uncertainty terrifies my husband, who would not need to begin from scratch. I perceive his perspective: We’re snug proper now. He’s making a wholesome earnings. He’s afraid of abandoning this life and ending up worse off.
If we leap and lease, we’re touchdown with out jobs. However, I imagine we’ll determine it out.
We’re nonetheless determining our plans — and dealing towards our finish aim
Allison Lau
We’ve talked till we’re each blue within the face. Our present plan is two-fold: save as a lot as we are able to right here within the US, and apply aggressively for jobs within the Netherlands. The two routes ahead aren’t in confrontation, so we’ll work towards each.
Our pondering is that, with time, one among us will both discover a job that can enable us to qualify for a Dutch mortgage and purchase a home with a mortgage, or we’ll accrue sufficient money right here within the US to purchase a Dutch house outright.
Two routes, two completely different monetary methods, and two probably very completely different timelines for shifting. We’ve received three years to hit our aim of shifting earlier than our son begins kindergarten, and we hope one among these methods will assist us do it.
Did I point out that I’m pregnant and now we have a toddler? It’s going to be a busy few years, however we’re excited.