How A lot International Publicity (If Any) Ought to Your ETF Portfolio Have?
Some of the best traders in historical past have famously favored a considerable home-country bias for U.S. traders, which means a portfolio overwhelmingly weighted towards American shares.
Perhaps essentially the most well-known instance is Warren Buffett. Beyond his long-running optimism (“never bet against America”), the Berkshire Hathaway chairman emeritus has left remarkably simple instructions for a way cash left for his spouse needs to be invested after his dying: 90% in a low-cost S&P 500 index fund and the remaining 10% in short-term Treasury bonds.
Vanguard founder John Bogle expressed the same choice. Despite Vanguard changing into one of many global community’s largest suppliers of worldwide mutual funds and exchange-traded funds (ETFs), Bogle argued that foreign stocks weren’t necessary for a well-diversified U.S. investor. He typically favored a heavy U.S. allocation and urged that traders who needed global diversification restrict it to not more than 20% of their fairness portfolio.
Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the most effective of knowledgeable recommendation on investing, taxes, retirement, private finance and extra – straight to your e-mail.
Profit and prosper with the most effective of knowledgeable recommendation – straight to your e-mail.
Today, nevertheless, worldwide publicity stays a normal element of many professionally constructed portfolios. Owning shares exterior the U.S. can cut back dependence on a single nation’s macro economy, market valuations, sector composition and foreign money whereas offering publicity to corporations and industries that are not nicely represented domestically.
If you are a do-it-yourself investor, that leaves a sensible query: How a lot worldwide publicity, if any, ought to an ETF portfolio even have?
Below, we’ll study the case for and in opposition to investing overseas, take a look at how a number of the largest international fairness ETFs divide their portfolios between U.S. and worldwide shares and spotlight low-cost ETFs that may assist you construct an worldwide allocation.
Why allocate to worldwide shares?
Despite the U.S. inventory market’s stellar efficiency over the previous decade and its outsized affect on international bourses, it is nonetheless only one basket.
Diversification can imply spreading investments throughout large-, mid- and small-cap shares, worth and progress kinds, and all 11 inventory market sectors.
It also can imply investing throughout totally different international locations. One of essentially the most instructive methods to visualise is with an asset return map spanning 2017 by 2026 from the BlackRock Investment Institute.
Sometimes referred to as an “asset-class quilt,” one of these chart ranks the annual returns of various asset lessons, geographies and market segments:
(Image credit score: BlackRock Investment Institute)
Even throughout a interval when U.S. equities carried out exceptionally nicely total, they did not lead yearly.
Chinese equities outperformed U.S. shares in 2017, 2019 and 2020, whereas European equities took the lead in 2025. Emerging-market equities additionally delivered superior returns throughout a number of intervals.
There is not any readily discernible sample an investor might have reliably used beforehand to maneuver between these bourses at precisely the appropriate time.
Indeed, that is one of many arguments for proudly owning the broader basket and permitting market dynamics to find out which areas contribute most to returns over time.
History additionally affords a extra painful instance of why geographic diversification can matter. The U.S. inventory market skilled what is usually referred to as the “lost decade,” typically referring to the interval encompassing the aftermath of the dot-com bubble and the 2007-09 international monetary disaster.
From January 1999 by December 2009, U.S. shares produced an annualized complete return of simply 1.7%, in response to Portfolio Visualizer. Adjusted for inflation, the annualized return was really unfavourable at -0.8%.
International developed bourses did higher at 4.1% yearly, or 1.6% after inflation. Emerging bourses have been the standout, returning 13.7% yearly and 10.9% after inflation:
|
Metric |
U.S. shares |
International developed shares |
Emerging market shares |
|
Starting stability |
$10,000 |
$10,000 |
$10,000 |
|
Ending stability |
$12,050 |
$15,600 |
$41,234 |
|
Annualized return (CAGR) |
1.7% |
4.1% |
13.7% |
|
Standard deviation |
16.4% |
17.9% |
25.3% |
|
Best 12 months |
31.4% |
38.7% |
76.0% |
|
Worst 12 months |
-37.0% |
-41.3% |
-52.8% |
|
Maximum drawdown |
-50.9% |
-57.1% |
-62.7% |
|
Sharpe ratio |
0.01 |
0.15 |
0.52 |
|
Sortino ratio |
0.01 |
0.21 |
0.78 |
With hindsight, it is simple to say {that a} younger investor ought to merely have saved dollar-cost averaging into U.S. shares at depressed valuations. Living by the expertise is totally different.
Few traders have limitless tolerance for watching a portfolio successfully go nowhere for a decade and truly lose buying energy after inflation.
And there is no rule saying a future interval of underperformance should final solely 10 years. Japan gives a very sobering instance.
The Nikkei 225 peaked at 38,915 on the finish of 1989 following an unlimited asset bubble. Japanese equities subsequently collapsed, and the nation’s financial difficulties turned identified first because the “misplaced decade” and finally the “lost decades.”
The Nikkei did not surpass its 1989 report till February 2024, greater than 34 years later.
That historical past gives a helpful thought experiment for U.S. traders. How a lot of right this moment’s choice for U.S. shares displays their genuinely engaging traits, and the way a lot displays recency bias after an unusually sturdy interval of relative efficiency?
If you’d been a Japanese investor close to the tip of 1989, after years of outstanding home returns and with Japan representing an unlimited share of worldwide fairness bourses, how snug would you might have been placing nearly your whole inventory allocation into Japan for the subsequent three many years?
There are reliable benefits to a U.S. home-country bias. Holding home shares avoids the direct foreign money fluctuations that include proudly owning international property denominated in euros, yen, kilos and different currencies.
U.S. shares will also be easier from a tax perspective. Foreign investments could contain withholding taxes on dividends and different problems, whereas certified dividends from eligible U.S. corporations can obtain preferential federal tax remedy.
Those are price contemplating, however they’re typically secondary portfolio-construction issues moderately than the place to begin. Asset allocation determines how a lot you maintain in shares vs bonds and, inside equities, how broadly you diversify throughout international locations and areas.
Those choices ought to primarily mirror your targets, threat tolerance and time horizon. Tax remedy, foreign money publicity and the actual ETFs used to implement the allocation come afterward.
What the main international fairness ETFs do
If you consider including worldwide shares is sensible, the subsequent query is the one which tends to trigger evaluation paralysis: How a lot must you allocate exterior the U.S.?
There are two sensible approaches. The first is to let market capitalization decide the allocation robotically. The second is to decide on your personal goal allocation and periodically rebalance the portfolio again towards it.
Market cap is just an organization’s share worth multiplied by its variety of shares excellent. A market-cap-weighted international index extends that idea throughout international locations.
As the collective market worth of 1 nation’s corporations will increase relative to the remainder of the global community, that nation receives a bigger weight. If it decreases, its weight falls.
There are a number of benefits to this method. Turnover tends to be low since you’re not continuously making an attempt to determine which nation deserves a bigger allocation.
If China, India or one other market finally turns into a a lot bigger share of the worldwide inventory market, its allocation can enhance naturally. If U.S. shares proceed outperforming and sustaining their dominant share of worldwide market cap, you proceed to profit from that, too.
You’re not systematically promoting winners just because they’ve exceeded an arbitrary geographic goal. It’s about as hands-off as worldwide diversification will get.
For many traders, that is additionally the tough half. It requires resisting the temptation to tinker with allocations based mostly on whichever nation has just lately carried out greatest or worst.
There is not, nevertheless, one universally authoritative definition of the “international inventory market.” Different index suppliers outline their investable universes otherwise, and the ensuing U.S.-vs-international allocation can range significantly.
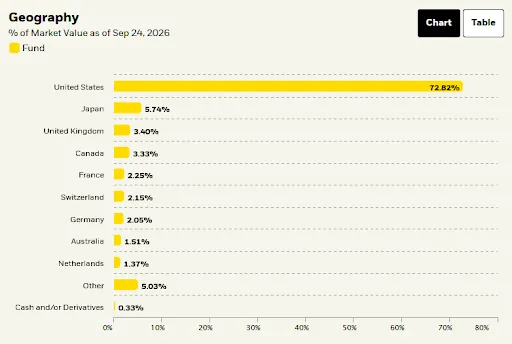
Consider the iShares MSCI World ETF (URTH). It tracks the MSCI World Index, and an investor utilizing URTH as a reference level would possibly due to this fact arrive at a 70% U.S./30% worldwide fairness allocation.
But the MSCI World Index has an vital limitation: Despite its title, it covers solely developed bourses. Emerging bourses akin to China, India, Taiwan and Brazil are excluded.
(Image credit score: iShares by BlackRock)
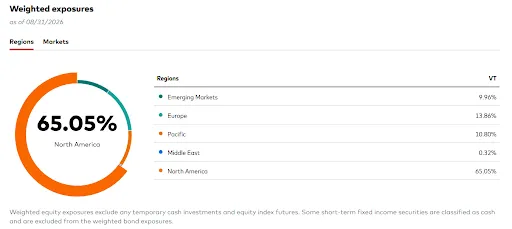
Contrast that with the Vanguard Total World Stock ETF (VT), which tracks the FTSE Global All Cap Index. Here, U.S. shares account for roughly 60% of the portfolio.
One main purpose is that VT contains rising bourses, which collectively account for roughly 10% of the fund.
(Image credit score: Vanguard)
The different is to decide on an worldwide allocation your self. You would possibly determine on 10%, 20%, 30%, 40% and even 50% of equities exterior the U.S.
The precise share is arguably much less vital than deciding on an allocation that you just perceive and may realistically keep on with by intervals when both U.S. or worldwide shares are lagging.
You can backtest totally different combos indefinitely and match the information to seek out the U.S.-international cut up that may have produced the most effective historic outcome. But that optimization is inherently backward-looking.
The successful allocation over the earlier decade tells you what labored throughout that individual decade, not what is going to work throughout the subsequent one.
If you set your personal goal, the extra vital choice is establishing a systematic rebalancing coverage.
One method is calendar-based, akin to reviewing the portfolio quarterly or yearly and restoring the goal weights. Another is threshold-based, the place you rebalance solely after the U.S. or worldwide allocation strikes a predetermined quantity away from its goal.
Rebalancing does not essentially require promoting, both. Investors who’re nonetheless accumulating can direct new contributions towards whichever allocation has fallen beneath its goal.
That will be significantly helpful in taxable accounts, the place promoting appreciated ETFs could understand short- or long-term capital positive aspects and create a direct tax invoice.
Ultimately, loads of the controversy over worldwide inventory allocation quantities to splitting hairs. If you’ve got already determined that geographic diversification belongs in your portfolio, a lot of the vital work is completed.
Choose an allocation you may preserve, set up guidelines for rebalancing it and keep away from repeatedly altering the plan based mostly on whichever market occurs to be main on the time.
Currency hedging provides one other wrinkle
Another factor traders ought to perceive earlier than dismissing the historic efficiency of worldwide shares is that returns have not at all times been pushed solely by the underlying corporations. Currency actions can both assist or damage a U.S. investor’s return, generally considerably.
Consider the iShares Core MSCI EAFE ETF (IEFA). It invests throughout developed bourses exterior the U.S. and Canada, which means its underlying shares commerce in currencies such because the euro, Japanese yen, British pound and Swiss franc. But IEFA itself trades in U.S. {dollars}, which creates an extra supply of return and threat.
If the U.S. greenback strengthens in opposition to these foreign currency, the worth of the international investments interprets into fewer {dollars}, making a headwind for a U.S. investor. If the greenback weakens, the alternative happens: Those international property translate into extra {dollars}, offering a tailwind even when the underlying shares themselves have not carried out any higher.
ETF issuers are nicely conscious of this, which is why many provide currency-hedged variations of their worldwide funds. IEFA’s counterpart is the iShares Currency Hedged MSCI EAFE ETF (HEFA).
HEFA gives related developed-market fairness publicity. But this fund seeks to hedge its international foreign money publicity again to the U.S. greenback, decreasing the impact of exchange-rate actions on returns.
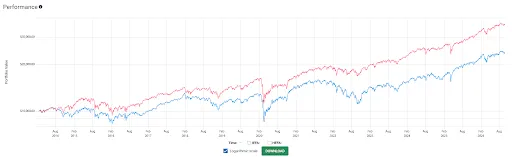
Over the 12.6-year interval by September 24, this distinction made a considerable distinction. According to Testfolio, HEFA produced a ten.7% annualized return, in contrast with 7% for IEFA. Cumulatively, that labored out to roughly 260.7% vs 135.1%.
Assuming distributions have been reinvested and ignoring taxes and buying and selling prices, a $10,000 asset placement would have grown to roughly $36,069.62 in HEFA vs $23,509.48 in IEFA.
(Image credit score: Tony Dong)
Does that imply HEFA is inherently the higher worldwide ETF? No. It means foreign money hedging was helpful over this specific interval, throughout which the U.S. greenback strengthened considerably in opposition to a number of developed-market currencies. The hedge insulated HEFA from a lot of that foreign money headwind.
If the U.S. greenback as an alternative weakens in opposition to these currencies, the connection can reverse. An unhedged worldwide ETF akin to IEFA can profit from the foreign money translation, whereas a hedged ETF akin to HEFA largely offers up that tailwind.
All else being equal, the identical mechanism that helped HEFA throughout a strong-dollar surroundings can work in opposition to it throughout a sustained interval of greenback weak spot.
If you might have a shorter time horizon or a specific need to isolate the efficiency of international shares, you could favor to hedge some or your whole foreign money publicity. Over a multi-decade horizon, nevertheless, predicting foreign money actions turns into extraordinarily tough, and trade charges can transfer by prolonged cycles in both course.
If you do not have a powerful view, there’s nothing unsuitable with splitting the distinction. A 50/50 allocation between hedged and unhedged worldwide publicity, periodically rebalanced, reduces the necessity to make an all-or-nothing guess on the long run course of the U.S. greenback.
As with the worldwide allocation itself, having an asset placement coverage you may comply with could also be extra helpful than regularly making an attempt to foretell which foreign money regime comes subsequent.