Here is How California Closed the Montana License Plate Loophole
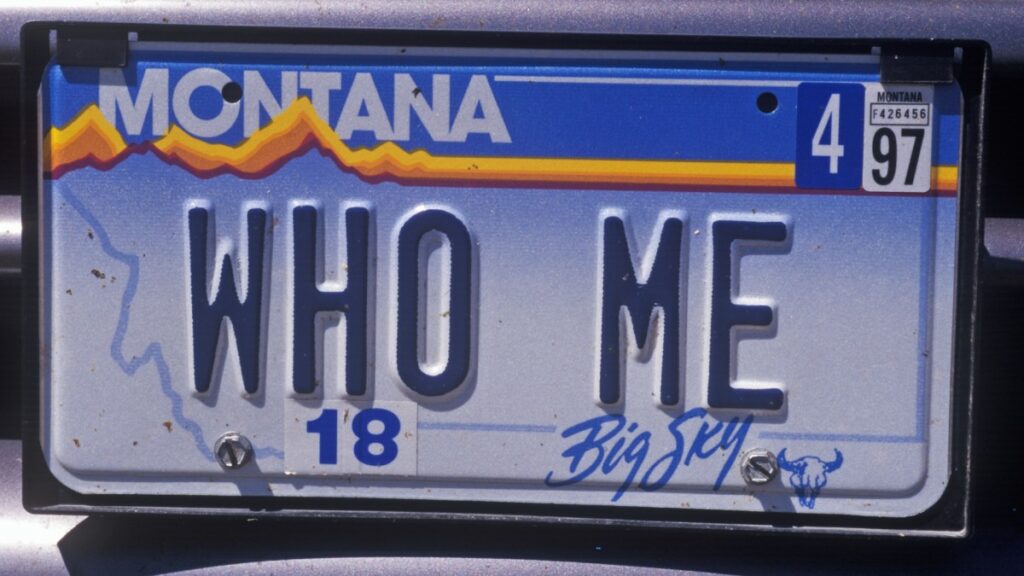
It’s official: California has closed the Montana license plate loophole. After greater than seven months of legislative shuffling, CA State Bill 1406 (“Sales and Use Tax Law: automobiles: shell firms”) grew to become legislation on Sept. 30, 2026, making it a lot tougher to get away with the shell-company shenanigans wealthy Californians have exploited for many years.
Existing California legislation says any automobile, vessel, or plane a California resident “shipped or introduced into the state” is topic to taxation beneath the state’s Sales and Use Tax Law, whether or not it’s registered there or not. This identical rule utilized to automobiles registered to a industry, however as a result of companies aren’t folks, the legislation set completely different requirements for establishing its “California-ness.”
Essentially, if greater than half of your industry was held outdoors California, you may maintain your automobile registered to that out-of-state industry with out paying Use Tax in California. This looks as if an affordable qualifier on paper. Say you reside in Nevada and your automobile is registered to your industry primarily based there; in case you function a department workplace on the California facet of Lake Tahoe, as an illustration, you may legally maintain your automobile there on Nevada plates as long as the majority of the industry was primarily based in Nevada. This is a gross oversimplification, however you get the fundamental concept.
This association appeared to work simply wonderful for everybody concerned till a bunch of individuals began registering pretend LLCs in Montana (although not solely), which doesn’t cost gross sales tax on automobile purchases (or require homeowners to examine/smog their automobiles). Under the previous legislation, solely firms and restricted legal responsibility firms have been topic to the California-ness check; the brand new legislation expands that definition to incorporate partnerships, restricted partnerships, and restricted legal responsibility partnerships. And then there’s the whammy (emphasis mine).
“The invoice would additionally present that, for functions of the above-described presumption, a shell firm, as outlined, is a resident of this state if any shareholder, accomplice, member, or useful proprietor is a resident of this state,” the bill summary says.
In different phrases, the previous 50% check is out. If anybody operating the industry is a California resident (by the up to date definition outlined above), then the entire industry is a California resident, and any belongings (together with Lamborghinis and Bugattis) held within the state are topic to California taxation. And simply in case you want it spelled out, which means you’re on the hook for that tax legal responsibility as a fellow accomplice/member:
“The invoice would maintain any officer, supervisor, accomplice, useful proprietor, or member of a shell firm personally answerable for any unpaid taxes, and any curiosity and penalties on these taxes, the nonpayment of which can represent a criminal offense, due on the acquisition of a automobile, vessel, or plane.”
Better be certain your paperwork is so as. The tax man’s a-comin’.
Got a narrative tip? Let us know at [email protected]