Gold’s rally drivers stay intact regardless of worth surges

Advisors say file authorities debt, central financial institution shopping for and inflation threat nonetheless help a strategic allocation to gold
Gold’s two-year rally has left many advisors asking whether or not the steel is now too costly so as to add to shopper portfolios. According to 2 outstanding voices within the area, the reply isn’t any — the structural forces that drove gold larger haven’t gone away, even because the tempo of beneficial properties is anticipated to sluggish.
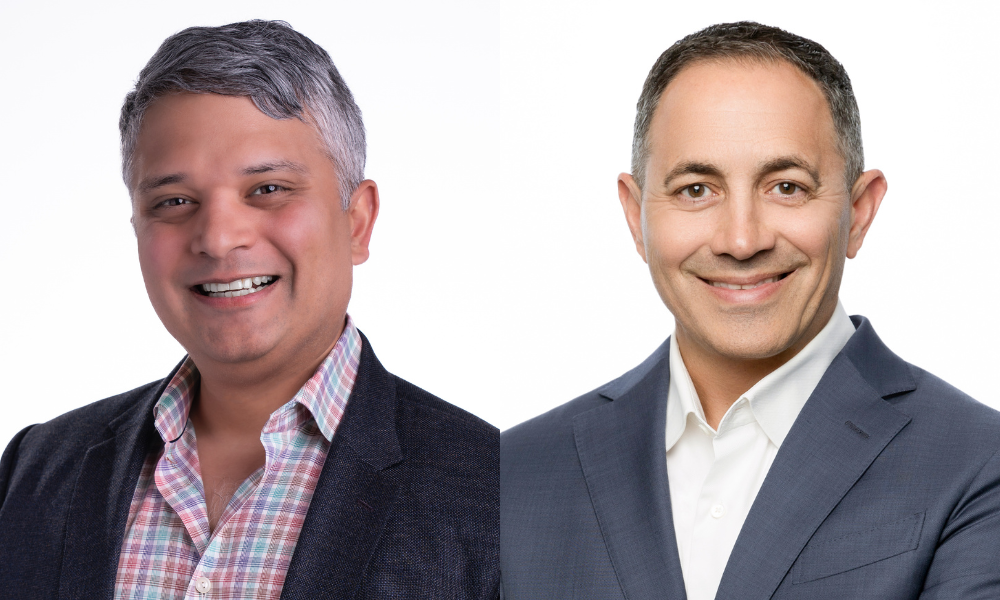
Aakash Doshi, head of gold technique at State Street Investment Management in Boston, mentioned the themes underpinning the present cycle stay intact: file US and world authorities debt, geopolitical fragmentation, regular central financial institution purchases, resilient Chinese bodily demand, and traditionally elevated stock-bond correlations. Gold has roughly doubled in worth over the previous few years, and with the Federal Reserve turning extra hawkish on inflation, Doshi expects beneficial properties to reasonable in 2026 and 2027 in contrast with 2024 and 2025. State Street continues to be focusing on $5,000 an oz by the tip of the primary quarter of 2027.
Why the diversification case nonetheless holds
For Doshi, the argument extends past worth targets. He famous that the stock-bond diversification assumptions underpinning conventional 60/40 or 70/30 portfolios have been challenged within the post-pandemic interval, reversing roughly 25 years of largely dependable diversification advantages that ran from the late Nineties by 2021. That breakdown, he mentioned, strengthens the case for liquid options that supply less-correlated market publicity — with gold squarely a part of that dialog. Doshi recommends a 3% to 10% allocation for many balanced portfolios, although he mentioned 3% to five% is extra lifelike for brand new cash coming into the asset class right this moment. Advisors weighing that shift can have a look at how monetary advisors are getting extra instruments for navigating the liquid alts area as demand for non-traditional diversifiers grows.
“Gold can be utilized as a strategic core asset both as an overlay to 60/40 or from a slight discount within the bond sleeve,” Doshi mentioned. “Since it’s a decrease volatility laborious asset that has lengthy market historical past and ample world liquidity, for many traders it must be thought of a strategic core holding. Higher volatility alternative-fiat belongings like bitcoin and silver I view as extra tactical trades. These underliers have the next beta to equities and don’t share the identical safe-haven traits of the position gold has performed in conventional portfolios.”
A sturdy supply of demand
Alex Shahidi, co-chief asset placement officer and senior managing director at Evoke Advisors in Los Angeles, largely agrees that rising costs alone have not modified the asset placement case. Elevated authorities debt, persistent fiscal deficits, central financial institution shopping for, geopolitical uncertainty and issues over fiat foreign money debasement all stay in place, he mentioned — and gold has traditionally carried out nicely when traders deal with these dangers. Still, after a number of sturdy years, Shahidi mentioned traders must be ready for short-term corrections.
“Gold is tough to worth as a result of it does not generate money flows, which suggests sentiment can drive significant worth swings in both course,” Shahidi mentioned. “Rather than specializing in the place gold trades subsequent quarter, I’d pay nearer consideration to the underlying drivers: inflation expectations, central financial institution demand, fiscal circumstances, and confidence in main paper currencies.”
One development Shahidi flags as significantly sturdy is the rising position of central banks as patrons, particularly emerging-market establishments diversifying reserves away from the greenback. That accumulation, he mentioned, could also be a steadier supply of demand than many traders recognize — a dynamic advisors have tracked for years, as detailed in earlier cash administration suggestions drawn from how central bankers diversify their very own reserves. It additionally echoes findings from a State Street examine displaying advisors already planning to boost their gold allocations nicely earlier than the most recent leg of the rally.
Shahidi pushed again on the concept gold is primarily a disaster hedge. Since 1971, he mentioned, gold has delivered long-term returns aggressive with world equities whereas sustaining a comparatively low correlation to shares — a mixture he believes makes it price contemplating in a well-diversified portfolio. He pointed to the inflationary Nineteen Seventies, when gold considerably outperformed shares and bonds, and famous that inflation has remained above the Fed’s long-term goal for a lot of the interval since 2021, with gold once more outperforming many conventional belongings over that stretch.
Two errors advisors ought to keep away from
“From an advisor’s perspective, I more and more consider gold as a part of a broader diversification allocation slightly than a tactical commerce,” Shahidi mentioned. “The applicable allocation will differ primarily based on an investor’s targets, risk tolerance and luxury, however gold’s historic tendency to behave in a different way than conventional shares and bonds can help its position in portfolio building.”
He cautioned towards two errors he sees advisors and traders make. The first is dismissing gold outright as a result of it produces no revenue, which may overlook its diversification worth. The second is treating gold as all-or-nothing.