From Eighth-Grade Inventory Purchases to Self-Made Millionaire

Welcome to Kiplinger’s My First $1 Million collection, during which we hear from individuals who have made $1 million.
They’re sharing how they did it and what they’re doing with it.
This time, we hear from a married 68-year-old retired challenge supervisor in media who lives in Southern Maryland. He reviews that his final wage was $98,950.
Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the most effective of professional recommendation on investing, taxes, retirement, private finance and extra – straight to your e-mail.
Profit and prosper with the most effective of professional recommendation – straight to your e-mail.
See our earlier profiles, together with a writer in New England, a literacy interventionist in Colorado, a semiretired entrepreneur in Nashville and an events industry CEO in Northern New Jersey. (See all of the profiles here.)
Each profile options one particular person or couple, who will at all times be utterly nameless to readers, answering questions to assist our readers study from their expertise.
These options are supposed to offer a window into how totally different folks construct their financial savings — they are not supposed to offer monetary recommendation.
To study what these millionaires have taught us, take a look at the articles 5 Key Insights We Learned From 50 Millionaires and 5 Things 50 Millionaires Wish They’d Known Before They Retired.
And to listen to extra about My First $1 Million, you possibly can take a look at this podcast with bestselling creator and tax attorney Toby Mathis:
The Basics
How did you make your first $1 million?
Dogged persistence. We saved greater than we spent, spent lower than we made and gave greater than we bought.
We had been in our early 40s when our net worth crossed $1 million.
We have at all times absolutely funded our IRAs, and we started aggressively funding our 401(okay)s once they first turned out there.
What are you doing with the cash?
When our kids had been in elementary faculty, we began to put money into SFD (single-family dwelling) rental actual property. At the time, we thought we’d start divesting when our kids started faculty, promoting properties as essential to fund these bills.

(Image credit score: Getty Images)
Turns out that by the point faculty got here round, our portfolio was throwing off a lot free money move that we did not must promote something!
The Fun Stuff
Did you do something to have fun?
Nope. That’s only a quantity.
What is the most effective a part of making $1 million?
One million is only a quantity — does not imply a factor by itself.
Did your life change?
Our asset degree permits my spouse and me to climate the idiocy of regardless of the present administration is, no matter political get together.
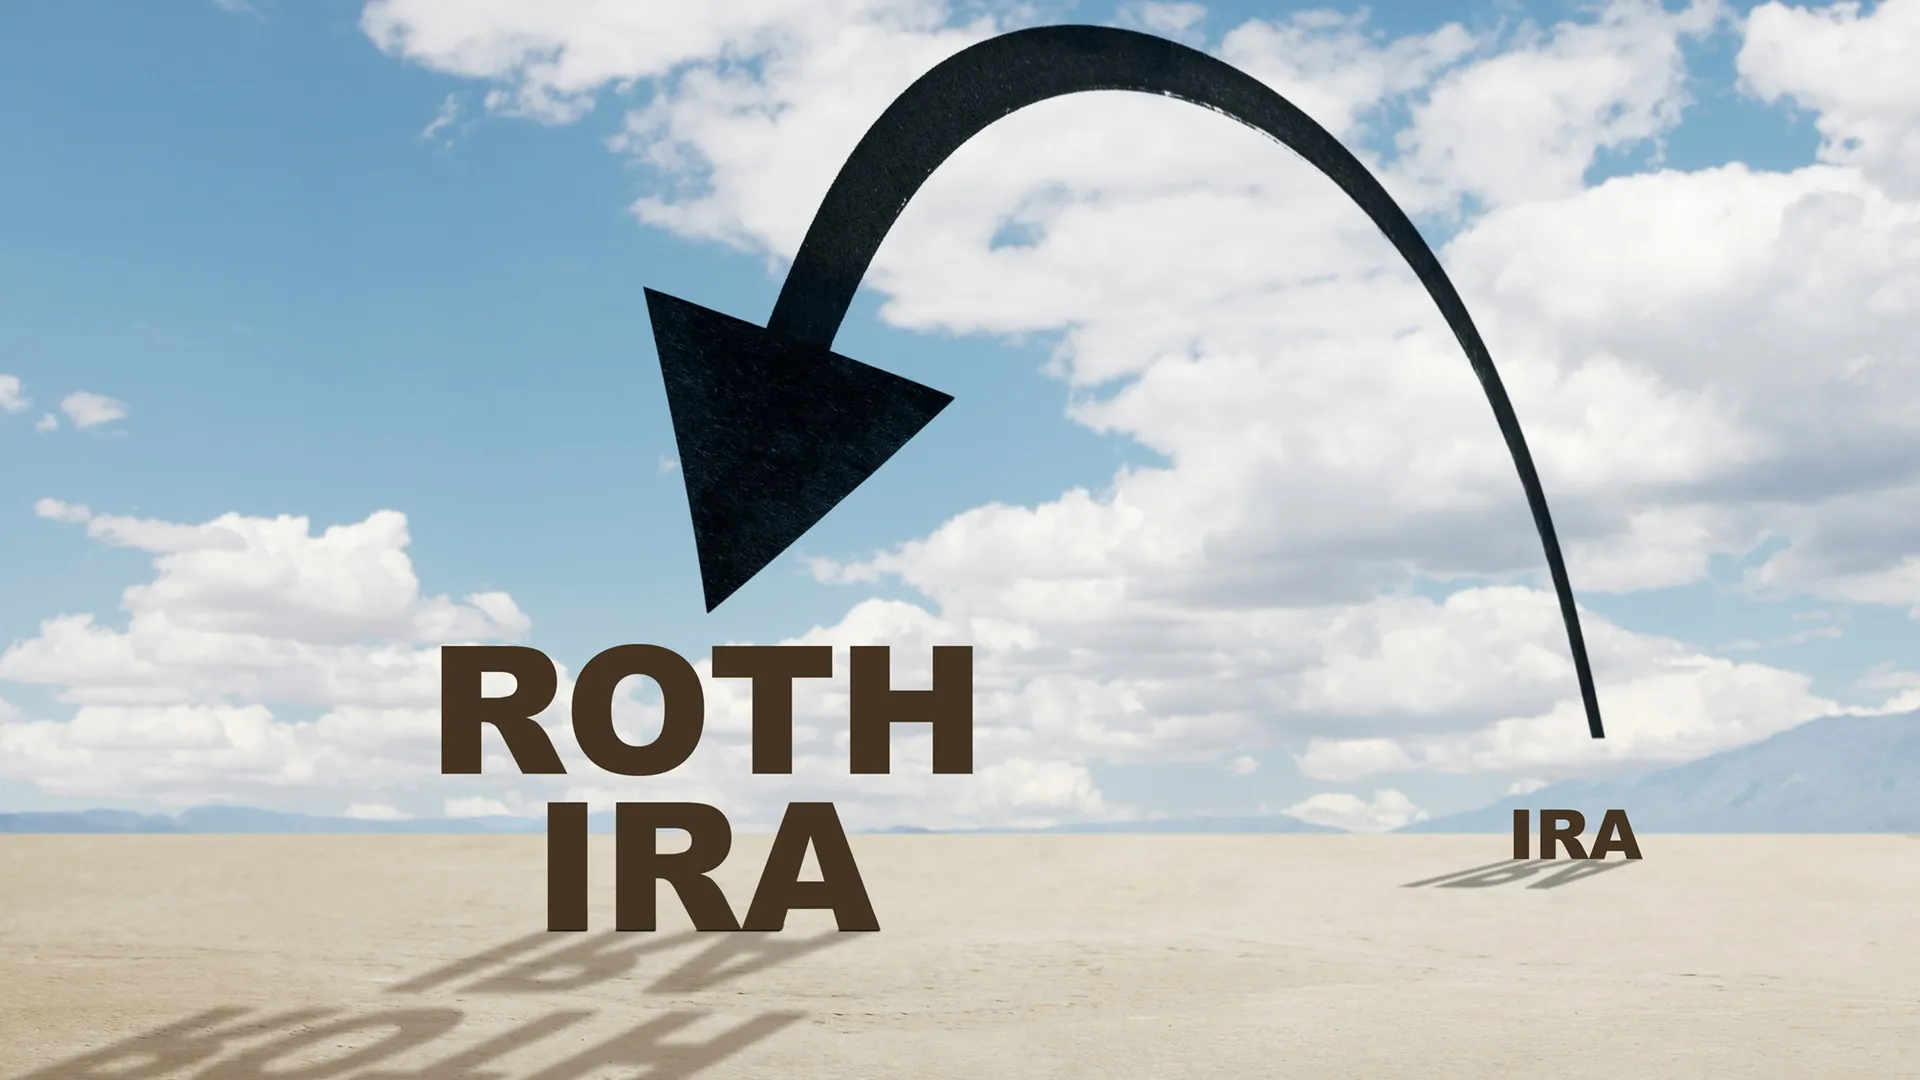
When the White House does one thing silly and exchanges crash, I merely use that as a possibility to do Roth conversions.
(Image credit score: Getty Images)
We had been early devotees of Roth IRAs, however for a few years, our revenue degree didn’t permit IRA contributions. Nevertheless, I used to be an early advocate of backdoor conversions.
Does anybody know you are a millionaire?
Our two grownup kids are effectively conscious and absolutely knowledgeable of our funds. That’s each a studying expertise for them and their spouses and a necessary ingredient of our property plan.
We threw our rental actual property into an LLC a few years in the past, and we diligently reward our kids’s trusts curiosity within the LLC to the utmost allowable.
Did you retire early?
My spouse retired in her mid-50s to begin offering daycare to our grandchildren. My plan was to retire about 10 years later — my authentic plan was to retire in mid-March of 2020 (keep in mind COVID?).
Our belongings are such that we are able to simply be up or down in a day what we used to make in a 12 months. That alone blows my thoughts!

(Image credit score: Getty Images)
Anyway, we had been down virtually $1 million after COVID hit, so I made a decision to push my retirement, which I hadn’t but communicated to my employer.
Ultimately, I delayed one 12 months till I pulled the set off — at the moment, I used to be 63.
Looking Back
Anything you’d do otherwise?
Nope, our aggressive capital allocation philosophy has served us extremely effectively, and we have at all times been self-directed.
Early in my profession, I used to be between jobs in the course of the spring, and we could not afford to make our IRA contributions, so we borrowed the quantity — it was $1,500 every so we may fund our accounts for that 12 months. We borrowed the funds in April and paid the mortgage off in September.
Early on, our IRAs had been completely in financial institution CDs. In our 50s, we started shifting that philosophy to fairness holdings.
After almost three a long time, I used to be laid off with a pension, and I had perhaps a dozen choices for the pension funds. Everything from “depart it alone” to “taking it.” I selected to roll over the funds right into a self-directed IRA with Schwab.
Then I moved it fully into positions in Apple, Google and Amazon.
What recommendation would you give to your youthful self?
Going all the best way again to my teenage years, I’ve mapped out and recorded all related private monetary particulars. Until Excel got here alongside, that was actually on accounting columnar pads. I can inform to the penny what I’ve invested, made, saved and spent, to not point out taxes, and so on.

(Image credit score: Getty Images)
That diligence has enabled me to simply mannequin the influence of various methods.
If I had been to present recommendation, I’d encourage folks to train comparable diligence in recordkeeping.
Realizing various years in the past that our liquid belongings exceeded the mixed lifetime revenue we had earned blew my thoughts. That alone satisfied me that our retirement could be comfy.
Think about it — we have in financial savings, retirement accounts, buying and selling accounts, and so on., as a lot cash as we have earned in our complete lifetimes!
So, I determine if it took me 40 years to earn X, and I’ve that very same X within the financial institution, then tough logic would say I’ve bought sufficient to reside on for the subsequent 40 years. Give or take.

(Image credit score: Getty Images)
Do your own taxes! There is completely no cause why an grownup early of their profession cannot do their very own taxes, and the sooner you start doing so, the extra comfy you can be with the numbers.
I nonetheless do my very own private taxes as we speak. I exploit a CPA for our property, LLC and trust taxes fairly just because they require advanced information of the tax code which I don’t possess.
Did you’re employed with a monetary adviser?
No, we’re fully self-taught and self-directed. A few years previous to my deliberate retirement, I engaged Edelman to overview our portfolio/plans and was flattered when the advisor instructed me he could not actually advocate any modifications to both.
The greatest shock was his evaluation indicated that we already had sufficient to completely fund our retirement at that time. That alone supplied my spouse with a heightened sense of consolation, although I had individually arrived on the similar conclusion.

(Image credit score: Getty Images)
We have all of our accounts with Schwab, they usually’ve been a very good associate. I opened my first Schwab account virtually 50 years in the past.
Did anybody make it easier to early on?
My father was very influential. Upon his recommendation, I purchased my first equities place (AT&T) after I was within the eighth grade.
Looking Ahead
Plans to your subsequent $1 million?
We’re usually up about 1,000,000 a 12 months — in fact, there are down years. But I can observe and pattern all the best way again to school, and our annual average return has been about 11%, and that elements in down years as effectively.
When I take a look at down years, I’ve discovered to take a deep breath, as a result of after I take a look at a down 12 months after which embody the 12 months earlier than and the 12 months following, we’re nonetheless up about 8%.
Any recommendation for others attempting to make their first $1 million?
I learn suggestions that it’s best to put money into your 401(okay) no less than as a lot as you possibly can to obtain the company match. I believe that recommendation is silly — in the event you’re not on the most allowable contribution, it’s best to set up a method to get there.
Whatever you’re saving, contributing, investing, up it. Even if it is solely a rise of 1% a 12 months, up it till you hit the utmost allowable.
(Image credit score: Getty Images)
When 401(okay)s had been first launched, we could not afford the maximum contribution, so we adopted the above technique to slowly however absolutely get to the utmost allowable.
We additionally embraced an strategy the place usually any wage enhance we bought, we poured it into financial savings. I at all times have assumed that Social Security wouldn’t be out there after I retired resulting from federal and congressional incompetence.
For that cause, all of my forecasts have by no means layered within the revenue that we’re due from Social Security.
Do you’ve got an property plan?
Yes, we’ve got established trusts for our kids which we fund yearly with curiosity in our LLC. Maryland permits one thing referred to as a life estate with powers, so we have titled our most important home right into a life property naming our daughters’ trusts because the homeowners.
We envision our residence to stay within the household after our deaths.

(Image credit score: Getty Images)
We’ve additionally acquired perpetual insurance coverage for our properties. For a one-time cost, we’re insured in perpetuity. These premiums are absolutely refundable, and for that cause, we stock the deposits as belongings on our stability sheets.
What do you would like you’d recognized if you first began investing?
My first fairness place was AT&T, which I purchased after I was within the eighth grade.
When I graduated from faculty, I took out a $3,000 private mortgage (which I paid off inside a 12 months) and bought shares in a wide range of native electrical suppliers. Some of these holdings are nonetheless in my portfolio.
My complete life, I’ve been a proponent of dividend reinvestment plans. When I retired, I shifted the holdings in my buying and selling account away from DRIPs and commenced utilizing that dividend revenue to reside off of.
Anything you want so as to add?
The success I’ve loved is comparatively straightforward to perform. All it takes is dogged persistence!
It completely boggles my thoughts that I might be up or down in a day what I used to make in a complete 12 months!
If you’ve got made $1 million or extra and wish to be anonymously featured in a future My First $1 Million profile, please fill out and submit this Google Form or ship an e mail to [email protected] to obtain the questions. We welcome all tales that add as much as $1 million or extra in your accounts, though we are going to use discretion during which tales we select to publish, to make sure we share a variety of experiences. We additionally may need to confirm that you simply actually do have $1 million. Your solutions could also be edited for readability.
Related Content
TOPICS