France’s dilemma: protesters demand spending as exchanges require fiscal restraint | France
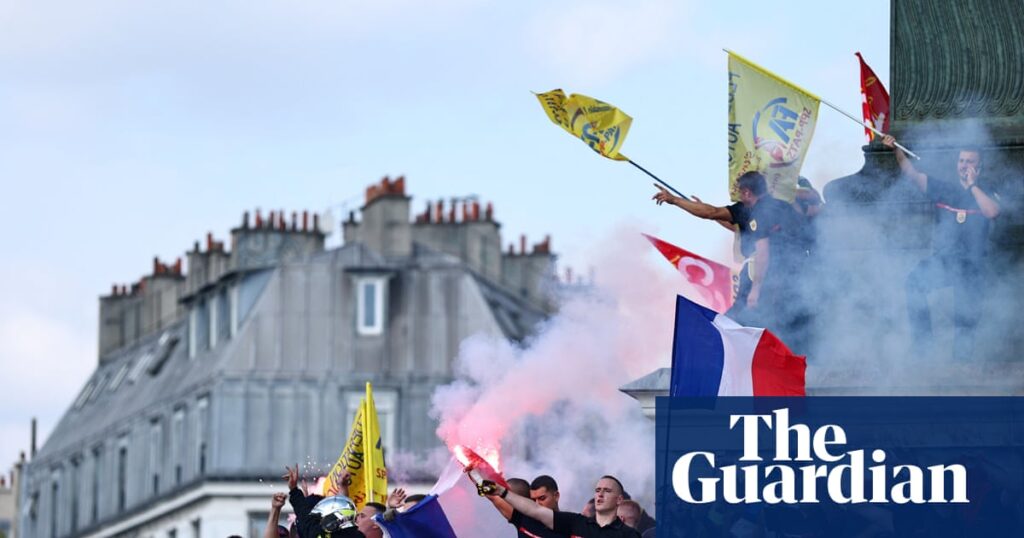
Eight years have handed since rising gas costs introduced the gilets jaunes (yellow vest) demonstrators to the streets of France, prompting the primary massive disaster of Emmanuel Macron’s time within the Élysée Palace.
As the French president contemplates his exit subsequent yr, turmoil has once more gripped the streets within the form of student protests, however this time the monetary exchanges are sad too.
Investors are involved concerning the authorities’s failure to carry spending underneath management and finish a protracted interval of “fiscal incontinence”. Financial exchanges are unnerved by related tendencies within the UK, the US and extra just lately Italy, inflicting jitters in global bond markets. But it’s France that has develop into the most important fear, hemmed in by money owed throughout the private and non-private sectors, limiting their scope to dig the nation out of a deepening gap.
France’s debt-to-GDP stood at 115.6% in 2025, whereas its finances deficit was 5.1%, in contrast with 94.3% and 4.3% for the UK respectively.
In Britain, the chancellor, John Healey, is heading in the right direction to scale back the finances deficit this yr and in 2027. His French counterpart, Roland Lescure, has promised to observe swimsuit after an increase to five.4% this yr, however has but to say how.
‘I’m panicking’
One sufferer of the uncertainty is industry capital allocation. A survey by Medef, France’s largest employer federation, confirmed 82% of corporations have been pessimistic concerning the affect of the following authorities’s financial coverage. In a warning to all politicians, 66% stated their industry would develop into susceptible and even go bankrupt if financial coverage remained deadlocked for the following 5 years.
A rescue operation might be mounted by the European Central Bank (ECB), however France would demand unconditional assist when the ECB’s guidelines say bailouts should include strict circumstances.
Antonio Fatas, a professor of economics at Insead, the European industry faculty, says the political and financial state of affairs has pushed France to the sting of a monetary collapse. “I’m very apprehensive concerning the financial state of affairs as a result of progress is low and it’s troublesome to see how the dynamics change. Then you might have the debt numbers, that are unhealthy, and the monetary exchanges are pondering the federal government just isn’t in management.
“If I take a look at the political state of affairs, I’m panicking. That’s as a result of too many political events are saying let France burn. They need a disaster, believing it can enhance their share of the vote.”
There is way concerning the financial state of affairs in France that mirrors what has occurred within the UK and the US. An enormous spending splurge through the Covid pandemic was adopted by one other spherical of subsidies to offset the worst side-effects from Russia’s full-scale invasion of Ukraine in 2022.
Investors have develop into cautious of lending to all three nations, however the rise in rates of interest is strongest in France.
Last week, the yield, or rate of interest, on 10-year French bonds hit the very best degree since July 2002, simply in need of 5%. Yields go up when bond costs go down.
Japanese buyers, sometimes robust supporters of France as a haven for his or her financial savings, have been instrumental within the panic after they discovered higher returns on residence turf, heaping additional ache on the French treasury.
Political turmoil
According to many metrics, it’s troublesome to see why France ought to be so badly affected. The French economic landscape has many issues going for it, from comparatively low electrical energy costs to higher than common utilities.
The faculties which might be the main target of current protests are higher funded than the OECD common.
On the debit facet of the ledger, Macron’s plan to lift the pension age from 62 to 64, saving tens of billions of euros from an virtually completely socialised retirement system, stalled at 62 and 9 months after parliament was deadlocked after the 2024 snap election. This may need mattered much less if the economic landscape was rising, however Macron’s much-vaunted financial revival stays caught in first gear.
Laurent Warlouzet, a professor of historical past on the Sorbonne, says it’s comprehensible that overseas buyers are confused about France when Marine Le Pen, the frontrunner in presidential elections subsequent yr, says she is going to roll again the retirement age to 62 and on the similar time introduce a “debt brake” by way of a referendum, limiting additional borrowing.
He stated: “The far proper was once a spendthrift populist drive, particularly underneath Le Pen’s management, broadening the enchantment of National Rally voters within the nation’s rust belts. In 2016–17, she nonetheless needed France to go away the eurozone, which she considered a straitjacket.”
after e-newsletter promotion
Warlouzet, the creator of Liberty, Solidarity and Community: capitalism and European integration, 1945 to the current, added: “Nowadays, Le Pen has develop into an unbelievable fiscal hawk. How can she reconcile this along with her voters’ calls for for extra nurses, lecturers, law enforcement officials and judges?”
‘Too massive to save lots of’
Erik Britton, the director of Fathom Consulting, an overseas advisory agency, says the prospect of a runoff between Jean-Luc Mélenchon, the chief of the leftwing La France Insoumise (LFI), and Le Pen subsequent April has spooked buyers greater than the failure to carry down the annual deficit.
“What has modified is the probably runoff. In the second spherical, it now seems to be probably that Le Pen will contest the presidential election towards Mélenchon from the far left. Le Pen’s election would possibly imply a 20% danger of Frexit: Mélenchon’s election, although much less probably on present polling, would have a a lot increased danger of Frexit.”
Britton says the collapse of the centre floor would have implications far past its borders. “Where France goes, the euro space as an entire tends to observe. If it led to a different take a look at of the euro, all of the concerns about debt and debt mutualisation would resurface, and bond yields would pop proper throughout the euro space (maybe excluding Germany) and past.”
It could seem unbelievable for monetary market merchants to think about France’s exit from the euro when it has occupied a central place within the single forex since its inception. Yet it’s understood a number of eurozone finance ministers and ECB officers have made representations to the French authorities, urging it to plot a finances components that may achieve a majority in parliament and a win over main lenders.
Without a finances, France could also be left to fend for itself. And if which means merchants boycott French bonds with out an enormous rate of interest premium, the nation could also be compelled to default on its money owed. A bailout would even be costly.
As the US Nobel prize-winning economist Paul Krugman stated just lately: “If France does have to be bailed out, it will be extraordinarily costly. As the second largest economic landscape within the eurozone, France might have crossed the road from too massive to fail to too massive to save lots of”
Dhaval Joshi, an impartial City economist, stated: “Ultimately subsequently, France must make painful changes to carry its debt maths again underneath management. Just like Italy, Spain (and, in fact, Greece) did a decade in the past, from which these southern European economies have emerged a lot stronger.
“The essential query is how a lot political ache France should undergo earlier than it makes, or is compelled to make, this adjustment.”
The head of France’s central financial institution, Emmanuel Moulin, denied final week that France wanted assist from the ECB, however infected the state of affairs by including the rider, “not at this level”.
Albert Edwards, a senior world strategist at Société Générale, stated France might survive the onslaught from bonds market merchants – a few of them termed vigilantes for his or her behavior of sniffing out weak nations – ought to one other nation start to look susceptible.
“Although France has been within the crosshairs just lately, the bond vigilantes’ focus is merely rolling from one market to a different. Next month their consideration is perhaps again on Japan, the UK or certainly the US.
“It is the way in which of the bond vigilantes to jab away and take a look at every market to search out out which is the weakest earlier than launching an all-out assault,” he stated.