Financial Planning Process: Build a Reliable Firm
Key Takeaways
- Clear plans start with reliable client information and shared internal processes.
- Scenario comparisons can make trade-offs easier for clients to understand.
- Simple visuals and plain language help turn projections into useful decisions.
- Technology can reduce repetitive work, but professional review remains essential.
- Consistent records, security practices, and team reviews support better client service.
Financial planning becomes difficult when a client’s investments, taxes, retirement goals, insurance needs, debt, and spending are reviewed in isolation. A connected process helps advisory teams explain how these decisions affect one another, while financial planning software for advisor teams can support a more consistent way to organize information and test choices. Clients do not necessarily need longer reports. They need to understand their current position, the decisions before them, and the actions most likely to move them toward their goals. In 2026, teams that combine disciplined planning procedures with clear communication can make each meeting more productive.
Why Clear Planning Matters More
Clients often arrive with questions that cross several areas of their financial lives. They may want to know whether they can retire sooner, help a child, buy a property, manage a business transition, or increase spending without undermining long-term security. A plan that treats those questions as connected decisions is easier to act on than a collection of separate account reviews. Technology can speed up organization and calculations, but speed alone does not create value. The goal should be to give advisors more capacity for thoughtful client conversations, not simply produce more outputs. A useful planning process makes assumptions visible, identifies trade-offs, and leaves the client with a clear next step.
Start With a Shared Planning Framework
Every team should establish a core set of information required before meaningful projections begin. This usually includes income, assets, liabilities, regular expenses, expected changes in spending, insurance coverage, estate considerations, tax details, goals, and key dates.
Separate The Essential From the Optional.
Not every detail needs to be collected during the first meeting. Define which facts are necessary for an initial planning discussion and which can be gathered later. This keeps onboarding manageable while ensuring every advisor works from the same baseline. A shared framework also prevents clients from receiving very different experiences depending on who prepares the plan.

Improve Data Quality Before Running Projections
A sophisticated model cannot compensate for incomplete or misunderstood inputs. Before relying on a projection, review account ownership, tax treatment, timing, liquidity, income stability, and whether an expense is ongoing or temporary. Assign responsibility for reviewing new data so important updates do not remain buried in emails or meeting notes.A reliable financial planning process ensures that accurate and updated information supports every projection and client recommendation.
Use a Simple Pre-Projection Checklist
- Confirm the source of each major figure.
- Check dates, time frames, and ownership details.
- Review unusual income, expenses, or one-time transactions.
- Document material assumptions used in the plan.
- Ask the client to confirm the summary before finalizing recommendations.
Make Scenario Planning Easier to Follow
One forecast can imply more certainty than a financial plan can reasonably provide. Instead, compare two or three realistic paths, such as retiring at different ages, changing savings levels, adjusting planned spending, or making a major purchase. Each scenario should show both the potential benefit and the trade-off. Keep the comparison focused on the client’s decision. Explain which assumptions have the greatest influence on the result, such as inflation, investment returns, longevity, savings, or spending. Projections should be presented as planning tools, not promises or guarantees. A structured financial planning process helps advisors present realistic scenarios and guide clients toward informed financial decisions.
Turn Complex Numbers Into a Clear Client Story
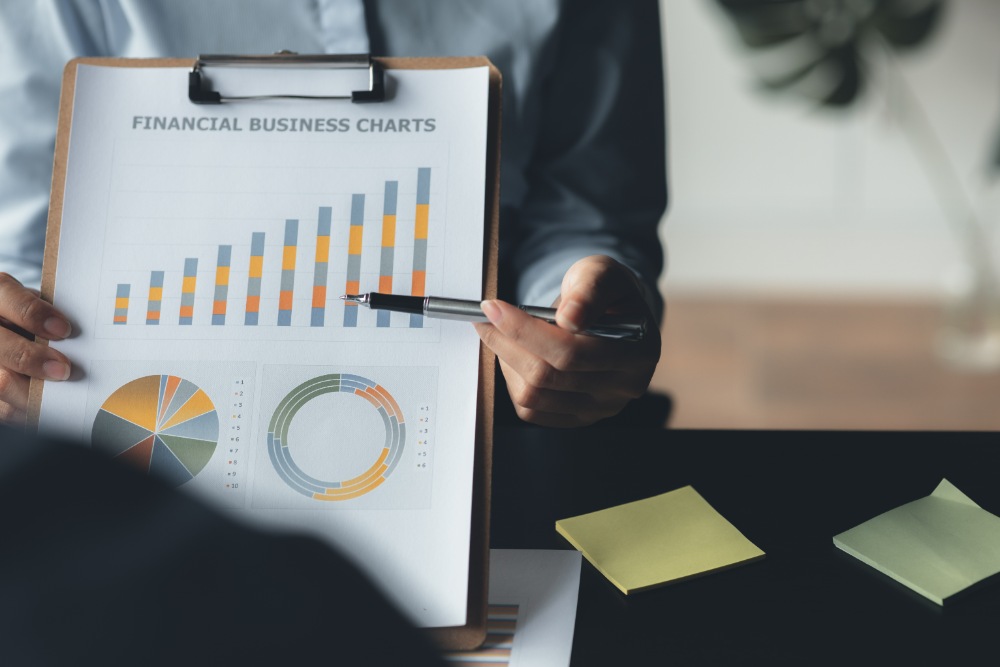
Lead with the conclusion before presenting the supporting calculations. For example, begin with the client’s current outlook, then explain the primary risk or opportunity, and finally identify the actions within the client’s control. Plain language is usually more useful than technical labels. Charts, timelines, and short written summaries can support the conversation by clarifying a choice. A strong report does not attempt to display every number. It helps a client answer the question, “What should I do next?”
Use Technology Without Losing Human Judgment
Planning tools can help teams organize data, draft documents, track workflows, and test scenarios during meetings. However, every output still requires review for complete data, appropriate assumptions, and client-specific context. Technology should support the advisor’s process rather than substitute for accountability. Responsible use also means setting clear boundaries for automated tools. As discussions about human judgment alongside AI tools make clear, organization and preliminary research are different from making personalized recommendations. Empathy, professional experience, and an understanding of the client’s priorities remain central to advice. An effective financial planning process combines technology with professional expertise to deliver accurate, personalized client guidance.
Build Consistency Across the Advisory Team
Shared templates and review standards reduce avoidable differences in client deliverables. Establish conventions for file names, planning assumptions, plan updates, and records of client decisions. Regular peer reviews can reveal recurring data errors, unclear language, or steps that create delays. Standardization should apply to the process, not force identical recommendations. Advisors still need room to reflect each client’s goals, family circumstances, risk tolerance, and changing priorities. A consistent financial planning process ensures that all team members follow reliable standards while adapting recommendations to each client’s needs.
Protect Client Information and Maintain Good Records
Limit access to sensitive information according to job responsibilities, use appropriate permissions, and review how documents are stored and shared. Teams should also evaluate a vendor’s security practices before adding new software or connecting systems. The SEC’s guidance on safeguarding customer information reinforces the importance of written policies and procedures for covered firms. Maintain a clear record of material changes, client instructions, and important planning assumptions. Good records improve continuity when several team members serve the same household and make future reviews more efficient.
Measure Whether the Process Is Working
Track measures that reveal whether planning is becoming clearer and more reliable, not merely whether more plans are completed. Useful measures may include:
- Time required to prepare a plan.
- Number of revisions after client review.
- Frequency of data-entry errors.
- Client completion of agreed follow-up items.
- Time spent in client-facing work.
- Advisor adoption of the shared planning process.
A Practical 30-Day Improvement Plan
- Week One: Map the current process and identify common delays.
- Week Two: Create a shared data checklist and core assumptions list.
- Week Three: Build a straightforward format for scenario comparisons.
- Week Four: Test the process with a small group of clients and gather feedback.
Common Questions Advisory Teams Ask
How Much Should Every Plan Be Standardized?
Standardize the core process, data requirements, and review procedures. Recommendations should remain tailored to the client’s circumstances.
How Many Scenarios Should Be Shown?
Show only the number needed to support a decision. Too many options can make an otherwise clear conversation harder to follow.
Can Automation Replace a Financial Advisor?
Automation can assist with organization, calculations, and workflows. It does not remove the need for professional judgment, explanation, and client communication.
What Is The Best First Step For a Small Team?
Improve data collection and build a repeatable review process before adding more tools or more complexity.
Conclusion
Clearer client plans begin with reliable information, shared planning standards, useful scenario comparisons, and thoughtful explanations that reflect each client’s goals and circumstances. When advisory teams follow a consistent process, they can reduce avoidable errors, improve collaboration, and make it easier for team members to understand a client’s financial position and next steps. Technology can further support this process by organizing information, streamlining routine tasks, and helping advisors compare different financial scenarios more efficiently. However, tools should support rather than replace professional judgment and meaningful client conversations. By explaining assumptions, outlining potential trade-offs, and turning complex information into practical action steps, advisors can help clients feel more confident about their choices. This balanced approach supports more consistent planning while ensuring recommendations remain personal, understandable, and aligned with each client’s priorities.
Find a Home-Based Business to Start-Up >>> Hundreds of Business Listings.