Annuities for RIAs: Why fee-only advisors nonetheless hit a wall
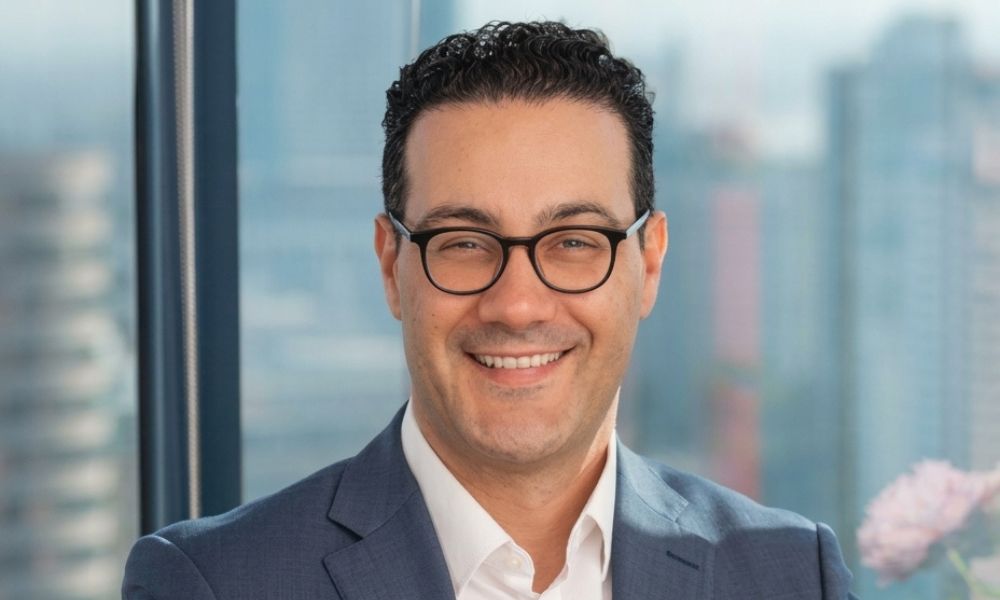
Nick Strain, senior wealth advisor and chair of the wealth advisory committee at Halbert Hargrove.
Halbert Hargrove senior wealth advisor weighs in on the merchandise’ assured earnings upside, the operational drag and his want record for carriers.
Nick Strain spent greater than a yr constructing a retirement earnings plan for one shopper out of 4 separate annuities. His agency did not cost an advisory price on any of them.
That trade-off exhibits the place annuities stand for a lot of fee-only registered financial backing advisors. The merchandise remedy issues a stock-and-bond portfolio cannot, however the work of utilizing them nonetheless matches awkwardly inside an RIA observe.
“Providing assured earnings offers much more security than conventional diversified mutual fund or ETF portfolio. [where] there is not any ensures,” mentioned Strain, senior wealth advisor and chair of the wealth advisory committee at Halbert Hargrove, in a latest interview with InvestmentNews. “Guaranteed earnings does put shoppers comfy,”
Where annuities match for RIA shoppers
At Halbert Hargrove, Strain sees two widespread entry factors for annuity conversations. The first is a brand new shopper who arrives holding an previous annuity and has forgotten why they purchased it. Cashing out can set off a big tax invoice, so he typically makes use of a 1035 alternate – a tax-free switch from one annuity contract to a different. The alternate can seize a better payout charge or transfer the shopper from a variable contract into an listed product with a flooring.
The second situation entails conservative shoppers nearing retirement with massive positions in money, CDs or Treasuries and little urge for food for extra inventory market threat.
“You wish to keep conservative, however perhaps being in Treasuries or money, high-yield money for a protracted time period won’t be the perfect long-term resolution for you,” he mentioned.
An rising variety of shoppers have joined the agency with current annuities over the previous 5 years, Strain mentioned. And as more people take an interest in the products, he mentioned there is a rising onus for advisors to include annuities into shoppers’ monetary plans on the agency, versus them getting suggestions elsewhere.
“I’d relatively be a part of the dialog than discover out what occurred six months later and never be pleased with no matter was beneficial,” he mentioned.
Citing a 2025 LIMRA examine, Strain mentioned solely about 1% of whole annuity premiums presently come from fee-based products, which has hindered adoption amongst RIA corporations that function on a price foundation. The broader annuity trade, in the meantime, hit a document $464.1 billion in gross sales final yr.
For their half, insurers count on annuity uptake to develop amongst RIA corporations. In Goldman Sachs Asset Management’s 2025 Annuity Industry Survey, 45% of respondents named the RIA channel because the one prone to see probably the most progress over the following three years.
The operational value of fee-only annuity recommendation
For a fee-only fiduciary that takes no commissions, the obstacles begin with information. “The problem for a agency like us or different fiduciary corporations is to have the experience and expertise of annuities as a result of annuities might be fairly complicated and so they’re perpetually altering,” Strain defined.
Infrastructure is one other impediment. As Strain defined, annuities require their very own paperwork exterior commonplace custodian workflows. Firms should additionally resolve whether or not to construct experience in-house or depend on a third-party insurance coverage platform.
“For our regular custodians the place we now have to rebalance accounts, we will do lots of of shoppers in a morning. And for insurance coverage, if we will attempt to rebalance or make financial backing modifications, it is usually one-off, separately,” Strain mentioned.
Client schooling provides one other layer of complexity. While there is a rising variety of methods to guage annuity choices available on the market, advisors should nonetheless stroll shoppers by a number of choices: whether or not to annuitize or defer, which riders to decide on, financial backing choices, caps, charges and give up schedules.
“The charges are an enormous one, simply because the charges [on annuities] are a lot higher than typical both inventory or bond mutual funds or ETFs,” he mentioned.
Registered index-linked annuities (RILAs) want their very own portfolio dialog, as a result of an earnings flooring would not essentially defend the underlying financial backing worth. “With registered listed annuities, in case you’re investing in, say, an S&P equal, the financial backing worth can go down,” Strain mentioned.
In phrases of his want record for carriers and insurtech platforms, Strain mentioned he wish to search instruments that stroll shoppers by completely different choices primarily based on their monetary objectives; stronger back-office help for paperwork and ongoing monitoring; tighter integration with portfolio administration, planning and CRM methods; and shorter give up price schedules, which presently can run so long as seven years.
“Hopefully a few of the charges will come down, identical to within the financial backing planet,” he mentioned.