Advisors urge dad and mom to construct early investing habits for grads

Advisors say a Roth IRA and clear expectations can flip parental help into a long-lasting wealth-building benefit
As younger faculty graduates confront a labor market the place a four-year diploma now not ensures a quick begin, advisors are urging dad and mom with the means to assist to suppose past protecting lease – and begin constructing early investing habits as a substitute. A Federal Reserve Bank of Cleveland analysis printed in November 2025 discovered that the long-standing hiring benefit faculty graduates as soon as held over highschool graduates has steadily narrowed since 2000, with job-finding charges for the 2 teams now almost converging. That shift is prompting monetary planners to rethink how households construction support through the bridge between faculty and a primary paycheck.
Make help conditional, not open-ended
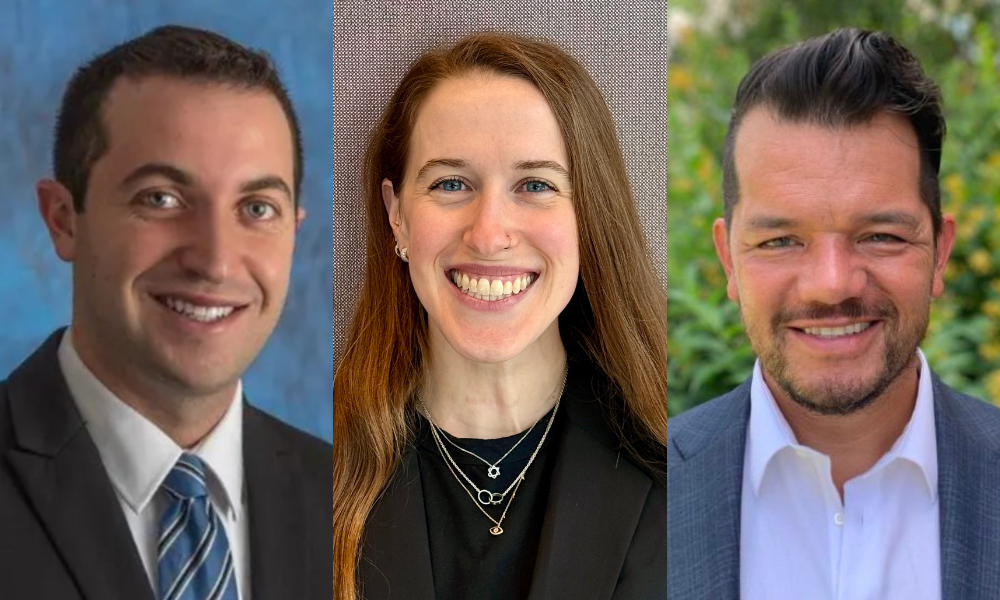
Kyle Sims, founding accomplice of 49 Financial, believes dad and mom with out there sources ought to use this transition to instill budgeting self-discipline that features funding financial savings from the beginning. He has labored with households who tie monetary help to particular expectations relatively than merely protecting the hole.
“It should not simply be subsidizing a chronic job search. Networking, purposes, interviews, and talent improvement are all metrics that folks can construct an efficient ‘job description’ round throughout this season of bridging into the subsequent skilled chapter,” Sims stated.
Sims added that matching funding {dollars} to the fitting time horizon is prime. Funds prone to be wanted inside a couple of years for a down cost or relocation prices name for extra secure, liquid choices, he stated, whereas cash meant for a decades-long horizon ought to keep invested via market noise.
“If that is the case, then investments that supply extra secure progress, much less volatility, and liquidity may very well be appropriate for such funds. Alternatively, for investments which might be certainly being invested for a 40-year time horizon, in the present day’s headlines should not override the time horizon. The most vital variable is getting the investments allotted in a long-term, diversified fairness portfolio that gives a chance for long-term progress to compound over a 40-year interval,” Sims stated.
The Roth IRA as an early wealth-building instrument
For younger adults with eligible earned revenue, a Roth IRA – a retirement account funded with after-tax {dollars} that enables certified withdrawals to develop and are available out tax-free in retirement – ranks among the many simplest automobiles for fogeys to fund, based on Sims.
“I’ve but to fulfill any consumer that is 50+ who needs they’d much less cash in a Roth. While it is inconceivable to foretell future earnings and corresponding tax legal guidelines that govern the potential to contribute to a Roth, in my expertise, there’s possible a finite window that somebody has to contribute to any such car, and they need to maximize that chance. The one factor individuals cannot purchase again is time, so permitting time to compound in your favor is maybe one of many largest early benefits dad and mom can present. That stated, the best early benefit isn’t any one particular account sort, however serving to younger adults match every greenback to a objective, start investing early, and develop a repeatable self-discipline to construct for the long run,” Sims stated.
That enthusiasm tracks with broader business information displaying younger investors embracing Roth accounts in document numbers, a development advisors say makes early parental funding much more related.
Alex Freedman, senior wealth advisor at Eclipse Private Wealth Management, a Sanctuary Wealth accomplice agency, stated probably the most impactful step a mum or dad can take is commonly introducing a younger grownup to their very own monetary advisor relatively than handing over money immediately.
“We function a useful resource via each life transition and might supply a trusted, goal voice exterior of their dad and mom. Our staff has met with youngsters as younger as 11 years outdated and tailor-made the dialog to their life expertise and stage of economic comprehension. Starting that relationship early builds trust, monetary literacy, and confidence – benefits that pay dividends past their first paycheck,” Freedman stated.
The strategy displays a wider business shift, as corporations more and more deal with courting Gen Z purchasers earlier than they construct vital belongings and on establishing relationships with purchasers’ grownup youngsters early of their careers.
Building the behavior earlier than the stability
For a 22-year-old with a four-decade funding horizon, Freedman usually favors a globally diversified, equity-heavy allocation constructed via low-cost, index-based ETFs.
“Today’s elevated yields might make a small money or quick length bond sleeve enticing for quick liquidity, however that should not drive the general portfolio. We anchor our conversations with younger traders round time horizon relatively than macro forecasting, as the best danger they face is commonly behavioral – panic promoting throughout downturns or making an attempt to time the market. Time is the only best benefit a younger investor has, and the sooner they start investing, the extra time they should reap the benefits of long-term progress and compounding,” Freedman stated.
Freedman famous that folks funding a Roth IRA on a baby’s behalf – restricted to the quantity of the kid’s earned revenue for the yr – can double as a monetary literacy instrument, supplied expectations are set early.
“Although dad and mom might assist fund the account, the Roth IRA belongs to the kid, creating an early alternative to show possession, investing, and long-term monetary duty. Families also needs to perceive that Roth IRA contribution guidelines and gift-tax guidelines are separate issues that will apply relying on the circumstances,” Freedman stated.
Brandon Goldstein, a monetary planner at Prudential Advisors, takes a distinct tack with purchasers whose grownup youngsters are nonetheless job-hunting: gathering modest “lease” and depositing it right into a separate account to be returned as soon as the kid strikes out.
“Even if it is solely a pair hundred {dollars}, it is very important get them into the behavior of paying bills and realizing duties exist for adults – whether or not you may have a job or not,” Goldstein stated.
For longer-horizon investing, Goldstein factors purchasers towards dollar-cost averaging – investing a hard and fast quantity on a set schedule no matter market circumstances.
“This technique may have you buying fewer shares when bourses are excessive and extra shares when the inventory bourses are at a low. This means that you can take the emotion out of the investing when you’re investing a set quantity every month,” Goldstein stated, including that shorter-term targets like a primary condominium or automobile nonetheless warrant consulting an advisor earlier than committing funds long-term.
Goldstein stated the underlying lesson issues greater than any single account sort. “The most vital recommendation I’d give to a consumer is to clarify the worth of compounding curiosity. It’s time available in the market, not timing the market,” he stated.