Past tax loss harvesting: why long-short methods demand a tougher look
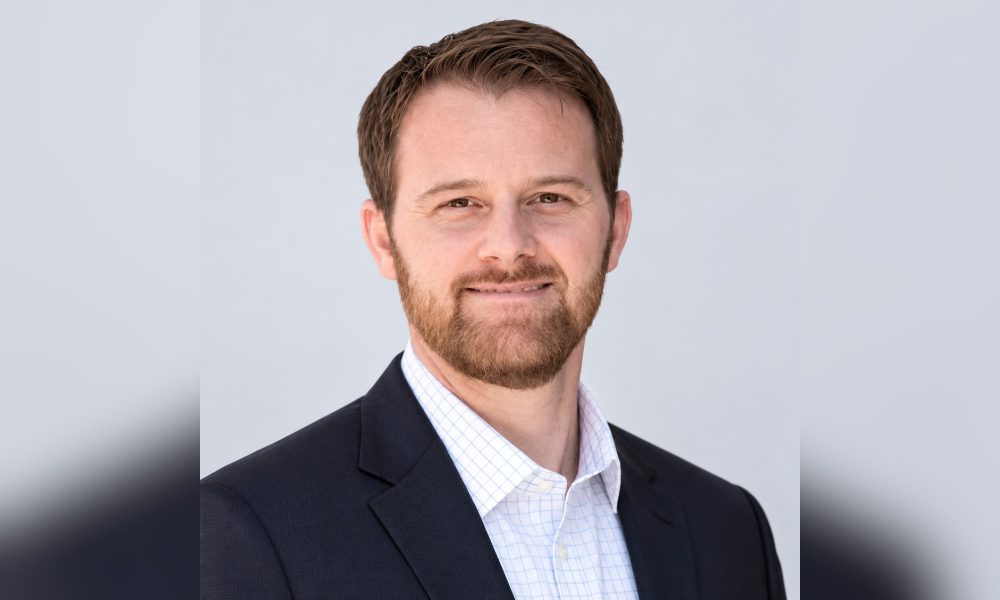
Ehren Stanhope, Chief Investment Strategist for Franklin Templeton’s Canvas platform
Advisors chasing tax alpha by way of long-short methods could also be asking the fallacious query, says Franklin Templeton’s Ehren Stanhope.
The pitch for tax-aware long-short strategies has turn out to be acquainted in advisor circles: generate losses to offset beneficial properties, defer taxes, and ship higher after-tax outcomes than a straight direct index.
But Ehren Stanhope, Chief Investment Strategist for Franklin Templeton’s Canvas platform, thinks that framing has the dialog backward and that advisors who lead with the tax story could also be setting their purchasers up for disappointment.
“We essentially consider long-short methods can present important profit,” Stanhope stated, “however the worth driver ought to be the alpha mannequin, not the tax advantages. What we’re seeing at this time is a whole lot of conversations centered on the quick ebook, and that dialog actually must be inverted.”
The tax lock drawback nobody desires to speak about
Before long-short even enters the image, many advisors are quietly contending with a extra fast problem: the direct indexing portfolios they constructed for purchasers are sitting on important embedded beneficial properties, and the harvesting alternatives that after justified the technique have largely dried up.
Stanhope is candid concerning the dynamic. After an prolonged interval of market appreciation, direct indexing “has offered an answer for advisors and purchasers to have larger management over when beneficial properties and losses are realized,” he stated. But as exchanges climb and losses are harvested, portfolios accumulate embedded beneficial properties and fewer positions stay beneath price foundation.
“This is not a flaw in direct indexing,” he stated. “It’s merely a consequence of long-term market appreciation.”
The advisor concern is actual, Stanhope acknowledges, however he pushes again on the concept that tax lock is a terminal situation. “Advisors have a tendency to debate it as if portfolios are static. In follow, tax loss harvesting is biggest inside the first few years of funding; volatility, new contributions, and money from dividends or dividend reinvestments can proceed creating harvesting alternatives over time.” His agency nonetheless views direct indexing as a sturdy, low-cost core fairness allocation with built-in flexibility when exchanges pull again.
For advisors monitoring the evolution of tax-efficient portfolio construction the long-short dialog is in some ways a response to direct indexing’s maturity, not a alternative for it.
Who ought to – and should not – contemplate long-short
Stanhope describes a selected shopper profile for tax-aware long-short. “We see the best curiosity amongst very high-net-worth and ultra-high-net-worth traders,” he stated. “Typically, these purchasers aren’t coming to an advisor with a portfolio – they’re coming with a steadiness sheet the place each asset has an ‘financial backing job’ and a ‘tax job.'”
A custom-made fairness core in a long-short wrapper can serve purchasers getting ready for a future liquidity occasion, managing a concentrated inventory place, or seeking to offset important personal market beneficial properties.
“For many of those purchasers, taxes have turn out to be vital sufficient that they are influencing, however not driving, financial backing choices,” Stanhope stated.
But he’s equally clear about which purchasers ought to keep away. Those who’re uncomfortable with an lively supervisor underperforming – the quick ebook can carry uncapped draw back – ought to keep away from the technique. So ought to purchasers who’ve one other advisor buying and selling comparable names in one other account, since mixing lengthy and quick positions on the identical inventory throughout a family can lead to a wash sale and disallow a loss outright. And purchasers with out sizeable present or anticipated future beneficial properties to offset merely lack the tax profile that makes the complexity price it.
“The greatest problem is knowing all the things the shopper owns,” Stanhope stated. “Affluent households typically have taxable accounts, retirement belongings, trusts, concentrated inventory, actual property, and outdoors managers – all of which affect financial backing choices.”
Evaluating the supervisor, not simply the technique
For advisors who’ve recognized the appropriate shopper, Stanhope’s framework for evaluating long-short managers is easy, however the sequencing is agency. Tax advantages come second.
“The first query is whether or not you consider within the supervisor,” he stated. “Look for managers with a longtime observe file, a well-researched and proprietary – not licensed – alpha mannequin, and correct danger controls.”
Long-short methods introduce leverage, increased prices – each financial backing and borrowing charges – and heightened danger and complexity. “Investment outcomes matter simply as a lot as tax outcomes,” he stated.
Where the technique does match, Stanhope says it performs nicely alongside a concentrated inventory place or an growing older direct index account. The leverage successfully injects recent price foundation into the portfolio.
And as a result of the long-short place ideally turns into the family’s fundamental means of holding a given fairness publicity, it requires clear household-level oversight to work appropriately. “You don’t desire one other account, or one other advisor, holding a protracted place in the identical title,” he stated.
Advisors fascinated about how personalized portfolio strategies are being implemented at scale will acknowledge that the execution problem is exactly the place expertise performs a rising position.
The subsequent frontier: coordinating the total monetary life
Stanhope sees the long-short dialog as a part of a broader shift in what personalization means in wealth management and the place it’s heading.
“The subsequent era of personalization will probably emerge on the intersection of alpha era, tax effectivity, and expertise,” he stated, “however the greater shift is that personalization will turn out to be much less about customizing a single portfolio and extra about coordinating a shopper’s full monetary life.”
Five years from now, he expects the companies that win within the high-net-worth market to be these that may make complexity really feel easy for each the advisor and the shopper. Technology (together with automation) AI-driven insights, and ultimately broader entry to rising investment vehicles by way of tokenization, ought to make it simpler to personalize at scale. “But the actual worth will nonetheless come from turning an advanced steadiness sheet right into a clearer set of shopper outcomes,” he stated: “getting ready for liquidity, managing taxes, producing earnings, diversifying danger, and aligning investments with what the shopper is definitely making an attempt to perform.”
For advisors evaluating whether or not a long-short technique belongs of their toolkit, Stanhope’s framework provides a helpful filter. The Canvas platform which now provides each long-short and conventional direct indexing in a single expertise is one expression of the place that evolution is headed. But the underlying message is platform-agnostic: begin with the financial backing thesis, confirm the family matches, then let the tax story observe.