What to Do With a $100,000 Inheritance to Set Up Your Future
Receiving a financial windfall by way of an inheritance can set off emotions of guilt and disappointment that come on account of shedding a beloved one. After all, what you’ve got been left with is a lot greater than a quantity. It’s a lasting legacy, and the form of generosity that may really feel overwhelming. You wish to bear in mind what the particular person meant to you — and never waste what they labored so laborious to depart behind.
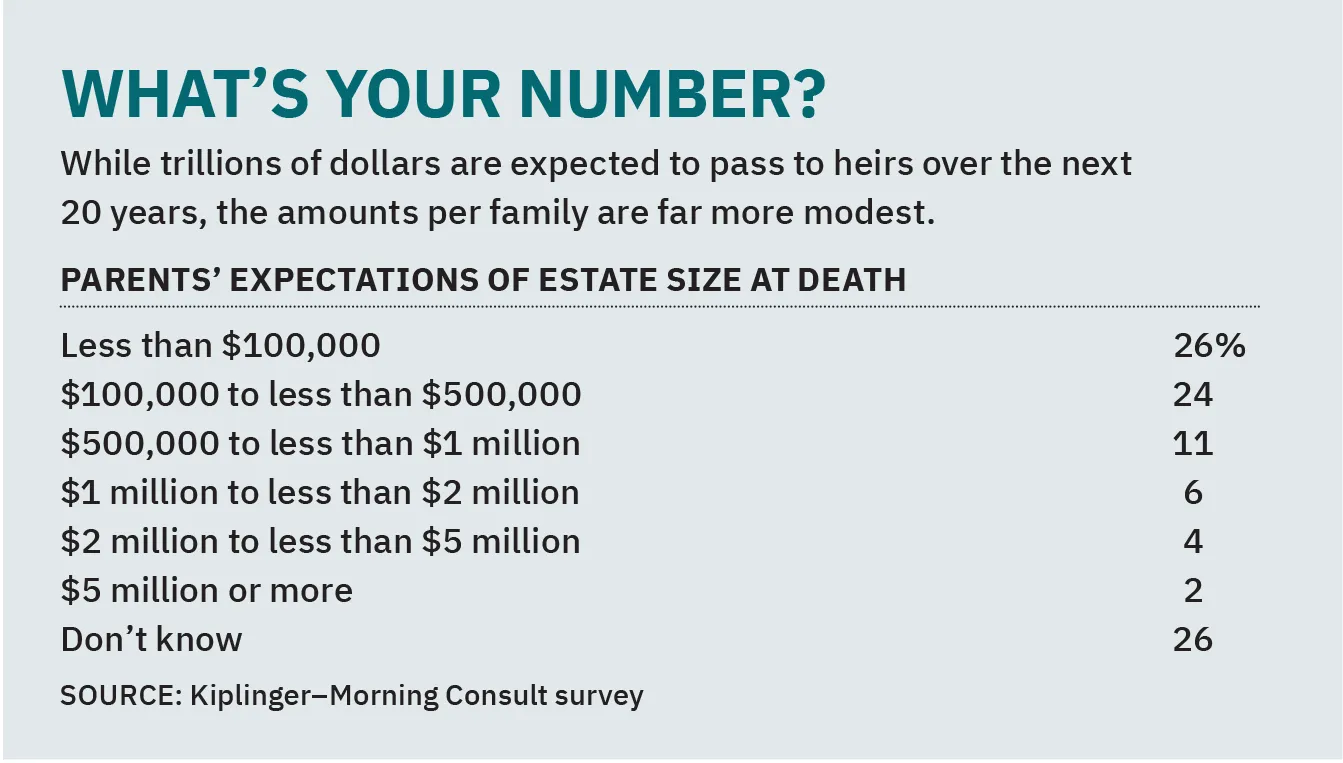
Used nicely, a big windfall can wipe out high-interest debt, construct an emergency fund, or enhance your retirement savings contributions. Used frivolously, it will probably disappear as quick because it arrived. The current U.S. Health and Retirement Study exhibits that 42% of heirs spent their total inheritance inside one 12 months.
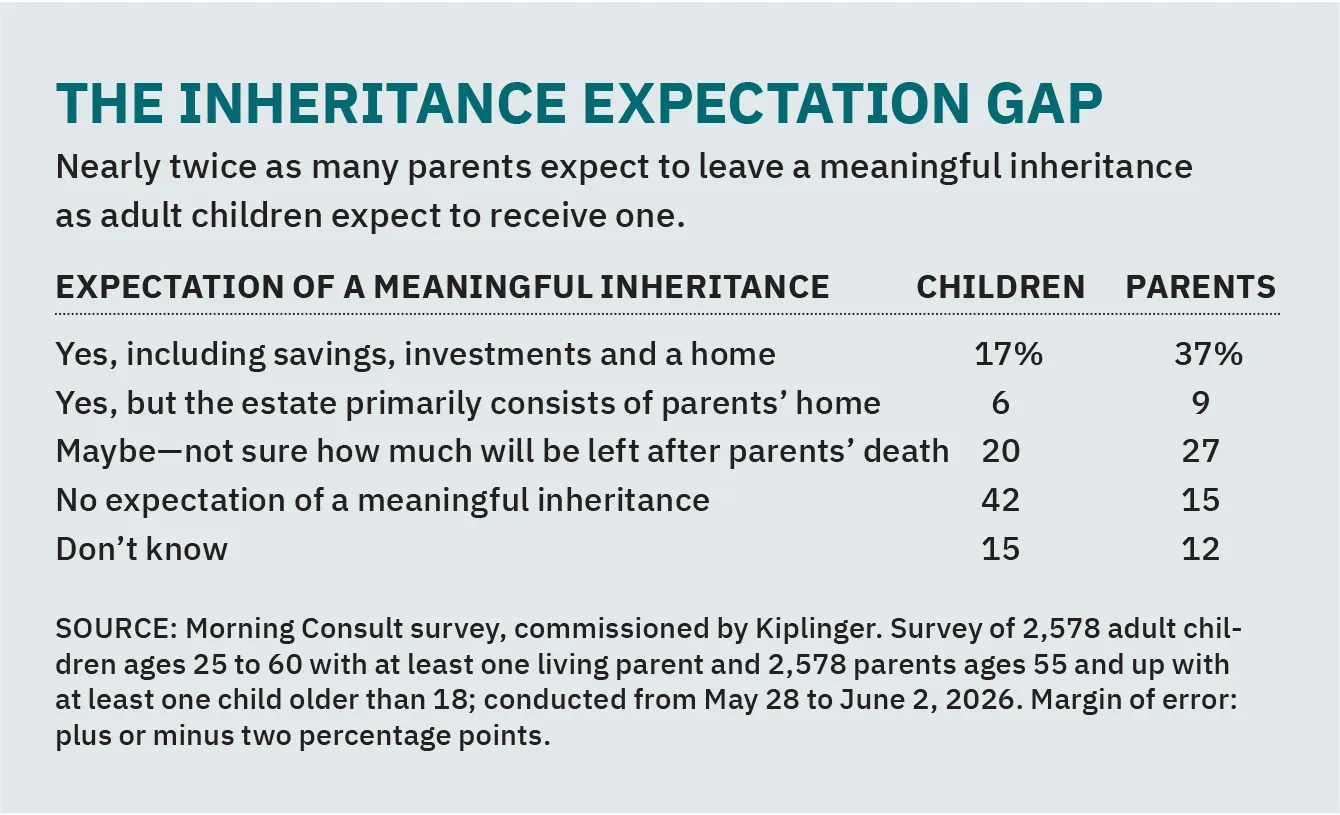
New Morning Consult-Kiplinger analysis exhibits that grownup youngsters are far much less more likely to assume they’re going to be getting an inheritance than mother and father who count on to depart one. In truth, 42% of youthful respondents say they do not count on to obtain a large quantity. However, about twice as many mother and father do plan on leaving a significant inheritance.
Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the very best of skilled recommendation on investing, taxes, retirement, private finance and extra – straight to your e-mail.
Profit and prosper with the very best of skilled recommendation – straight to your e-mail.
Latest Videos FromKiplinger
That’s encouraging, provided that 60% to 65% of Americans reside paycheck to paycheck, in response to a Wealthvieu survey, and one other 56% can’t cowl a $1,000 emergency. So if $100,000 confirmed up in your checking account, it could in all probability really feel like some huge cash.
If you’re anticipating a windfall otherwise you’ve already acquired a large inheritance, right here’s a information to arrange your monetary future so the cash lasts, as a substitute of disappearing within the first 12 months.
(Image credit score: Kiplinger / Future)
Take time to breathe
According to Capital Group, two-thirds (65%) of Gen Xers and Millennials say they remorse how they used their inheritance cash, with practically two in 5 wishing they’d invested extra. While solely 18% of millennials turned to monetary advisers for capital allocation recommendation, 27% had been extra more likely to flip to social media and ‘finfluencers’ for recommendation after they inherit.
Srbuhi Avetisyan, a analysis and analytics specialist at Owner. One, provides this recommendation. “Don’t rush to make the cash productive. Give your self permission to do nothing with it for some time. An inheritance is uncommon cash as a result of it arrives along with emotion.” She says that relying on the circumstances, there might be grief, aid, guilt and a wierd sense that it is advisable to “do one thing smart” instantly. “That’s not an important state by which to make a $100,000 choice.”
If you obtain the $100,000 in money, think about placing it in an FDIC-insured high-yield savings account or money-market fund and leaving it there whereas you determine what you wish to do with it long run. Then give your self time to breathe. You don’t need to rush into any choices. Coping with grief is not simple, and including $100,000 to the combo can solely complicate issues.
Don’t deal with a promise like a payday
Planning forward is a sound technique in lots of conditions. But relating to an inheritance, planning for a way you will spend the cash earlier than it lands in your checking account might be reckless. Wait till what you may have after which incorporate the funds into your retirement plans.
While you might be anticipating a certain quantity, keep in mind that circumstances for the particular person leaving you the cash can change, and so can the inheritance. Your buddy or relative might have to enter a nursing residence or an costly long-term care facility, or they might resolve to offer all of their cash away to their favorite charity as a substitute and go away you with a future you can’t assure.
Even Thomas Jefferson stated, “Never spend your cash earlier than you may have it.” Talk with an inheritance planning advisor who can assist you resolve the easiest way to deal with the cash within the quick time period, in addition to assist devise a long-term monetary plan that takes all your property and obligations into consideration.
There is nothing flawed with having fun with a part of an inheritance. The mistake is letting a significant monetary alternative disappear with out ever deciding what the cash is meant to perform.
Focus on debt discount first
Paying down debt with an inheritance isn’t probably the most thrilling first transfer, nevertheless it is among the most dear. Credit cards can carry an rate of interest of 20% or extra, which may eat away at even the most important inheritance. So, paying off excessive balances is a assured return in your cash. It additionally frees up money movement and makes it simpler to save lots of or make investments the remainder of the inheritance. Paying off scholar loans or your home mortgage can also assist, particularly in case your objective is to be debt-free.
Consider investing the cash
With the assistance of a financial planner, you may wish to make investments the cash out of your inheritance. Diversify your investments throughout totally different choices with various danger ranges, relying on how educated (and risk-tolerant) you might be. Rather than investing it all of sudden, think about investing over time, utilizing a technique like worth or dollar-cost averaging.
(Image credit score: Kiplinger / Future)
Boost your contributions
An inheritance also can present a chance to spice up your contributions to a 529 college savings plan account or retirement accounts, resembling a 401(k) or IRA. You can’t put inherited cash in a retirement account as a result of it is not earned earnings or different taxable compensation. However, realizing you may have it will probably provide the consolation wanted to boost your contributions.
Take extra out of every paycheck on your 401(ok). Your take-home pay can be much less, however now you should use the inheritance cash in your checking account to cowl your bills, like hire, groceries, and payments that your paycheck used to cowl. You’ll have the identical way of life, however you’ll even have extra money in your 401(ok) for retirement. You can put $24,500 in a 401(k), and much more if you happen to’re 50 or older.
You also can put $7,500 in an IRA. If you may have a qualifying high-deductible well being plan, you possibly can put $4,400 in an HSA for your self or $8,750 for your loved ones. Those accounts do settle for a examine or a switch, so inheritance money can go in immediately, so long as you keep below the yearly limits. Or, select a Roth IRA if you happen to assume your tax price can be greater sooner or later.
Understand the tax implications
Unless you inherit quite a lot of cash, you in all probability will not have to fret about federal estate taxes ($15 million per particular person or $30 million for a married couple in 2026).
However, sure property do have tax implications. For instance, if you happen to inherit securities, jot down what they had been price on the day that the particular person you inherited them from died. You’ll have to know your price foundation if you happen to resolve to promote them.
The tax guidelines for individual retirement accounts (IRAs) range relying on whether or not you inherited them out of your partner or another person. The sort of IRA, conventional or Roth, additionally issues. You will not owe tax on the quantity you inherit, however you may be taxed if you take distributions from a conventional IRA. With Roth IRAs, withdrawals are sometimes tax-free, however you are typically required to empty the account inside 5 years.
(Image credit score: Kiplinger / Future)
Enjoy your inheritance
If you wish to spend some of your $100,000 inheritance on your self or your family members, go forward. After all, the cash is yours now. Just bear in mind, when it is gone, it is gone.
Jason Stephens, Founder and Managing Partner of Evertern Wealth, just lately labored with a consumer who inherited about $150,000 from a grandparent. “They used a part of it to take their first journey to Europe, paid off their scholar loans, and invested the remainder,” he stated. “That was a considerate use of the cash. They loved a significant expertise, eradicated debt, and nonetheless directed a considerable portion towards long-term monetary safety.”
Stephens says there may be nothing flawed with having fun with a part of an inheritance. The mistake is letting a significant monetary alternative disappear by way of a collection of purchases with out ever deciding what the cash is meant to perform.
If you are moderately safe financially and have been pushing aside repairs in your leaky roof, or have a medical emergency, that inheritance will turn out to be useful. However, if you happen to’re as much as your knees in debt, it is perhaps higher to concentrate on setting your self up for a future nobody can predict.
What a $100,000 inheritance can imply
If you obtain a $100,000 inheritance, first, be grateful; it will probably make a constructive distinction in your life. Stephens recommends taking a number of months to grasp what you acquired, the tax implications, and what you need the cash to perform. “That’s usually extra invaluable than dashing to take a position or spend it.”
“An inheritance can honor each side of what the one who constructed the wealth seemingly needed,” he stated. “They needed you to get pleasure from a few of what they labored so laborious to create, they usually needed your life to be extra financially safe. Good planning accomplishes each.”
Related content material
TOPICS