Majestic Corporation: why this critical minerals recycler could have further to run
Majestic Corporation’s revenue has doubled, pre-tax profit is up more than fivefold, and a new processing plant still isn’t at full capacity.
Governments and organisations are seeking new sources of copper, gold, and other critical metals, and the Aquis-quoted urban miner is meeting that demand with discarded electronics.
– Advertisement –
This has culminated in a Majestic Corporation share price that has increased around 90% this year. But a look at their peers and growth trajectory suggests there could be more to come.
The mine above ground
Demand for critical minerals is coming from AI infrastructure, data centre build-outs, electrification, batteries and renewable energy all at once. Primary supply is struggling to keep up.
S&P Global projects a copper shortfall of 10 million tonnes by 2040, and a new mine takes, on average, 17 years to go from discovery to production. Ore quality is also worsening: S&P Global Market Intelligence estimates that gold head grades have fallen 13.4% since 2010.
But a major alternative source of critical and precious metals is being wasted. The UN’s Global E-waste Monitor puts global electronic waste at 62 million tonnes in 2022, of which only 22% was documented as collected and recycled.
The metals in that waste were worth about $91bn, and annual volumes are forecast to reach 82 million tonnes by 2030. Europe is falling short too. The European Environment Agency found the EU collected just 40.6% of electricals placed on the market in 2022, against a legal target of 65%, down from 48.6% in 2019. In the UK, people throw away more than 100,000 tonnes of electricals each year.
This e-waste is rich in critical minerals such as copper, gold, cobalt, lithium, and nickel, all metals demanded by organisations and government for electrification, the AI build-out, and everyday manufacturing.
Majestic’s business model
Majestic Corporation sits in the middle of the metals value chain. On the supply side, it buys material from a broad range of sources, some of which are exclusive. These include end-of-life electronics from decommissioned data centres, grid and telecoms infrastructure, consumer electronics, and household collection streams. It also takes in solar panels, catalytic converters (a source of platinum group metals), battery production scrap and non-ferrous materials such as copper cable.
Additional value is created in processing. Material is sorted and graded by type, for example separating circuit boards from casings, drives and cabling, because each contains different metals. It is then shredded and further concentrated, with copper and aluminium separated from the fraction rich in precious metals. The output is refinery-ready feedstock sold to smelters, refiners and industrial users across Europe and Asia.
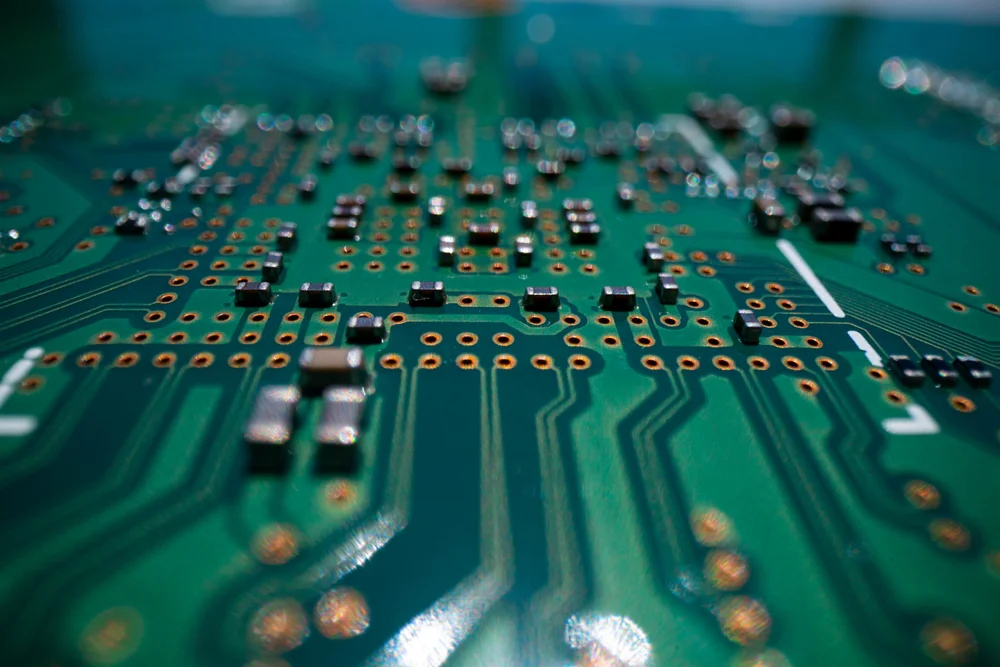
This step matters because few refineries can handle complex secondary feedstock, their capacity is limited, and they are selective about what they accept. Cleaner, more concentrated and more consistent material therefore earns better prices. Majestic says it is among the UK’s largest exporters of printed circuit boards, which contain copper, silver, gold and palladium.
It is also using its in-house R&D to turn what it describes as two decades of proprietary recovery data into process technology for future sites.
Results show momentum
Results for the six months to 30 June 2026 suggest the strategy implemented by the team in recent years is paying off. Revenue rose 101% to $36.6m, from $18.2m. Gross margin widened from 8.6% to 12.9%, which the company attributes to better non-ferrous and precious metals margins, growth in the UK, strong demand for its PCB services and cost discipline.
Administrative expenses rose in absolute terms but fell as a share of revenue.
As a result, profit before tax increased 5.5 times to $3.25m, from $0.59m. That is more than double the $1.35m earned in all of 2025. Earnings per share rose from 2.92 cents to 16.10 cents. The balance sheet also strengthened. Operating activities generated $5.7m of cash; cash on hand reached $4.4m (from $1.35m at the 2025 year-end).
The first half continues a longer improvement in profitability. Between 2021 and 2025, gross margin rose from 5.0% to 9.0%, and net assets grew from $6.1m to $10.1m.
“Doubling revenue and a substantial uplift in profitability show that the decisions we have taken, namely in 2024 and 2025, are now paying off, as we said they would,” said Peter Lai, CEO of Majestic Corporation.
Why there could be more to come, and what to watch
Majestic Corporation shares are around 90% higher this year but still trade at a valuation that appears attractive relative to peers.
If first-half performance continues through the second half and the company achieves similar profit, it would trade at a P/E ratio around 11x. It would also trade at around 1x sales.
This would be lower than peers such as Waste Management Inc., the $67bn market cap recycler that trades at 27x trailing earnings and Europe-based Veolia, which trades at 20x earnings. Veolia has a large-scale WEEE facility in Belgium that reportedly processes around 80,000 tonnes of material per year.
These two examples have constraints when compared to Majestic, with Waste Management Inc and Veolia running diversified recycling operations that cover everyday household and commercial waste. But it does highlight the valuations that scale in the sector can achieve.
Private funding rounds for UK critical minerals recycling companies may also offer a sense check – DEScycle raised about £10m Series A in 2024 at an undisclosed valuation. Altilium, which recycles EV batteries, recently completed a round at a £175m pre-money valuation.
This would make Majestic’s £67m market cap appear modest.
We must note that Majestic’s shares trade with a wide spread and limited liquidity, meaning the company can move quickly on a few trades and the current price may not reflect what it could be with more active trading.
But this doesn’t change the fundamentals. Wrexham will run at full capacity for the first time in the second half, according to the company. A greater share of upgraded, higher-margin feedstock should support margins. Policy tailwinds in the UK and EU favour recycled supply. And the replicable site model, if it works as planned, could expand volumes without the cost and lead times of traditional mining.