Midterm election will not change portfolio fundamentals, advisors say
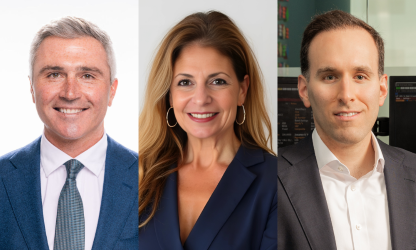
From left: Angelo V. Esposito Jr., Tracy Byrnes, Juan Xavier Sánchez
Wealth managers urge self-discipline earlier than Nov. 3 and level purchasers to year-end tax planning strikes no election can change
With the Nov. 3, 2026, midterm election approaching, monetary advisors are fielding the identical query from anxious purchasers: ought to the portfolio change earlier than the vote? Three wealth managers interviewed by InvestmentNews say the reply is sort of at all times no, as a result of what drives long-term outcomes – a consumer’s objectives, time horizon and self-discipline, together with earnings and Federal Reserve coverage – just isn’t on the poll.
The strain to behave is actual. In a Harris Poll survey performed for Nationwide from Aug. 24 to Sept. 11, 2026, 40% of buyers mentioned that they had already changed their retirement savings or portfolio ahead of the midterms, and 75% mentioned the result may meaningfully have an effect on their long-term plan. Advisors are leaning the opposite method: 63% mentioned leaving capital allocation methods unchanged is the very best course in an election 12 months, up from 52% in 2024.
Clients additionally need assist. A UBS Investor Watch survey of millionaire buyers discovered 59% usually tend to take into account working with an advisor in an election 12 months, up from 29% in 2024, as InvestmentNews reported when it coated how wealthy investors are turning to advisors for guidance. The similar survey discovered 84% need more guidance than usual from their advisor throughout an election 12 months.
Why the midterm election hardly ever strikes long-term returns
Angelo V. Esposito Jr., founder and personal wealth advisor at Atlanta-based Harbor View Private Wealth, mentioned midterm campaigns produce loads of noise however seldom alter what determines a consumer’s final result: the monetary plan, risk tolerance, asset allocation and near-term money wants. Markets might react to a outcome, he mentioned, however these strikes are inclined to fade as buyers return to company earnings, financial knowledge and Fed coverage.
“History helps staying the course: since 1874, the S&P 500 has been increased 12 months after a midterm election about 84% of the time, with a median acquire of roughly 14%. Vanguard’s analysis estimates that advisors can add about 3% a 12 months in internet returns, and about half of that comes from behavioral teaching, which suggests serving to purchasers keep on with their plan when feelings run excessive. An election is strictly that form of second,” Esposito mentioned.
Juan Xavier Sánchez, head of wealth technique at Activest Wealth Management in Aventura, Florida, mentioned this cycle is uncommon in a single respect: the forces which have moved financial hubs in 2026 are usually not up for a vote.
“Oil has pushed inflation increased, the Fed responded by elevating charges in September, and commerce and deregulation are pushed by the White House, which isn’t up for election both. In our view, the vote will change how Washington will get issues carried out greater than the place financial hubs are going,” Sánchez mentioned.
The Federal Open Market Committee voted 12-0 on Sept. 16, 2026, to raise the federal funds target range by a quarter point to three.75%–4%, saying inflation stays elevated.
What may stir volatility after Election Day
Sánchez expects the larger check to come back after the votes are counted. A stopgap spending invoice signed Sept. 2 retains the federal authorities funded solely by way of Dec. 11, 2026.
“That doesn’t imply the result’s irrelevant. Its actual check comes proper after the election, with authorities funding working out on December 11 and the debt restrict returning in 2027, and people negotiations may deliver some volatility to bond yields. But that form of volatility is strictly what an excellent plan is constructed to deal with,” Sánchez mentioned.
How advisors discuss purchasers out of election trades
Tracy Byrnes, vp of girls & investing at Lebenthal Global Advisors, mentioned the most costly mistake forward of the midterms is letting political views steer capital allocation choices.
When purchasers ask about transferring to money, Byrnes tells them they’d be timing the market twice – as soon as after they promote and once more after they resolve it’s secure to get again in, which is often the tougher name. Her check is easy: has something modified in regards to the consumer’s objectives, time horizon or want for the cash? If not, she wants a compelling capital allocation cause, not election anxiousness, to change the portfolio.
“Election outcomes might affect sure sectors or tax insurance policies, however they should not decide somebody’s whole capital allocation technique,” Byrnes mentioned.
Esposito mentioned purchasers who need to reposition earlier than a vote typically do not realize they’re making an emotional choice slightly than an capital allocation one.
“Our job is to gradual that down. We remind purchasers that financial hubs are inclined to refocus on fundamentals as soon as the preliminary response to a outcome fades, and that each robust and weak fundamentals have proven up underneath each mixture of occasion management in Washington,” he mentioned.
Sánchez opens these conversations with one query: did one thing change in your plan, or solely within the information? He mentioned it’s virtually at all times the information.
“Trading round an election means being proper twice, on the outcome and on how financial hubs react to it, and this 12 months financial hubs have had greater issues to react to than Congress. We imagine there are higher instruments for a nervous consumer than an enormous transfer: rebalancing again to focus on, setting apart the following 12 months or two of spending so they aren’t compelled to promote, or placing new cash to work steadily,” Sánchez mentioned.
Younger purchasers may have that dialog most. The UBS survey discovered political beliefs closely affect capital allocation choices for 42% of millennial respondents, in contrast with 10% of child boomers – a spot that complicates the work of advisors managing multigenerational households and their competing priorities.
Year-end tax planning strikes no election can change
Sánchez mentioned the planning calendar must be anchored to the one date no election can transfer: Dec. 31.
“Year-end tax work ought to occur now, regardless of the outcomes: harvesting losses the place it is sensible, being deliberate about which beneficial properties get realized this 12 months, and taking a look at Roth conversions or charitable presents in lower-income years,” he mentioned.
Tax-loss harvesting means promoting investments at a loss to offset realized capital beneficial properties. Byrnes provides required minimal distributions and charitable giving methods to the year-end record, together with retirement revenue plans for purchasers who want liquidity over the following few years.
On retirement revenue, Esposito sees the current rise in rates of interest as a cause to revisit money holdings and bond positioning. He expects harder year-over-year inflation comparisons in 2027 may lead the Fed to carry charges regular or finally lower.
“For purchasers who rely on their portfolio for revenue, this can be an excellent time to place extra money to work and take into account locking in at the moment’s increased yields for longer. Rates may nonetheless transfer increased from right here, so any change ought to match the consumer’s general plan and time horizon,” Esposito mentioned.
Estate planning additionally deserves a glance. The One Big Beautiful Bill Act, signed July 4, 2025, set the federal property and present tax primary exclusion at $15 million per person for 2026, according to the IRS, listed for inflation. Sánchez famous that whereas the regulation calls the exemption everlasting, that solely means it has no expiration date, not that Congress cannot change it.
“In our view, that may be a cause for households with bigger estates to overview their plans now, whereas the principles are recognized. One easy step earlier than year-end is the annual present exclusion: $19,000 per recipient for 2026, and no matter is not utilized by December 31 is misplaced. None of those steps is dependent upon who wins in November,” Sánchez mentioned.
Byrnes put it extra bluntly.
“Estate plans and beneficiary designations must be reviewed recurrently, not simply when Washington modifications palms. So vote primarily based in your political convictions, however your portfolio must be constructed round your monetary objectives – not politics,” she mentioned.