‘It’s a alternative’: Payment-only fiduciary RIAs win shopper loyalty however lose market share
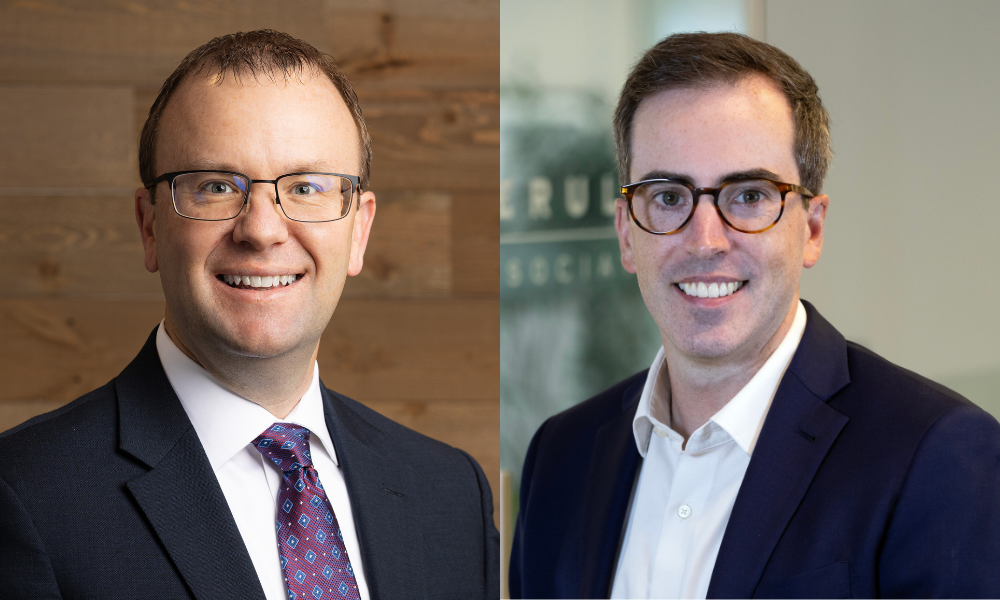
From left: David Hefty, co-founder and CEO of Credent Wealth Management; and Brendan Powers, senior director at Cerulli.
First-of-its-kind analysis finds hybrid RIAs are rising quickest, but traders working with sometimes-only fiduciary advisors report the bottom loyalty
True fee-only fiduciary RIAs hold their shoppers extra loyal than another recommendation mannequin, but they’re steadily shedding floor to hybrid and insurance-licensed rivals, in response to new analysis from Cerulli Associates.
The report commissioned by Credent Wealth Management, an Indiana-based fee-only RIA with $5 billion in property beneath administration, discovered that amongst RIAs with no less than that a lot in property, true fee-only impartial corporations – these with no affiliated broker-dealer and no insurance coverage licenses – held 34% of property at year-end 2025, down from 42% in 2020. Hybrid RIAs with brokerage companies held regular at 51%, whereas impartial RIAs with insurance coverage licenses doubled their share to 14%.
Despite the five-year pattern, David Hefty, co-founder and CEO of Credent, stays optimistic that the fee-only fiduciary mannequin has extra progress forward of it, so long as sufficient corporations maintain the road.
“You have to decide on to place shoppers first,” Hefty stated. “No one’s going to make you do it. No regulatory physique, no authorities, nothing. … It’s a alternative.”
Consolidation is redrawing the RIA map
The fee-only phase continues to be increasing, simply extra slowly. Based on a first-of-its-kind market sizing evaluation, Cerulli decided that the variety of $5 billion-plus true fee-only corporations rose from 83 to 121 between 2020 and 2025, a 7.8% compound annual progress charge. By distinction, hybrid RIAs grew 12.4% a 12 months, from 104 to 186 corporations, and insurance-licensed RIAs grew 37.3% a 12 months, from seven to 36.
Hefty stated he is gotten a way of that shift firsthand as a bidder on succession offers, noting that some consumers value in turnover from shifting acquired shoppers into fee merchandise when placing collectively their affords.
“Sometimes these consumers are factoring within the proportion of property that they’ll transfer out of a 75-basis level recurring turnover scenario, perhaps put right into a 5-7% fairness index fee up entrance, or a life insurance coverage fee, which is 50% to 100% year-one premium,” Hefty stated. “Sometimes the advisors on the promoting finish do not actually know [or] perceive this.”
Read extra: To be a fiduciary, or not to be a fiduciary?
For Brendan Powers, a senior director at Cerulli who managed the challenge, the report additionally opens up a chance to higher outline a market that is grown extra advanced because it matured.
“You’ve bought these three subsegments of RIAs that exist now when, traditionally, people had thought-about fiduciary and RIA to be interchangeable,” he stated.
While the fiduciary fee-only RIA has lagged different fashions in progress over the previous decade, Power stated the pattern would not replicate any weak point within the corporations or the fashions they function with.
“That’s not as a result of they’re any worse than these different corporations from a service viewpoint,” he stated. “It’s very merely that they are getting acquired … or they’re buying an affiliated broker-dealer or insurance coverage capabilities, thus shifting them from one phase to a different.
“We do undoubtedly see a number of the advisors who break free from a captive atmosphere type of coming full circle again right into a captive atmosphere as they’re acquired by one among these hybrid RIAs,” he added.
At this level, essentially the most prolific deal machines present few indicators of stalling. Even as third-quarter quantity fell 17%, consolidators handled 53% of RIA deals through September, in response to DeVoe & Company.
At Credent, Hefty says the possession construction consists of solely 11% outdoors capital, and it goals to maintain greater than 60% of possession inner.
Loyalty runs highest the place fiduciary obligation by no means switches off
Among traders who say their advisor should all the time act of their greatest curiosity, Cerulli discovered almost three-quarters (73%) are glad and never on the lookout for a brand new supplier. That falls to 48% amongst these traders who say their advisor could put their very own pursuits first, and to 42% once they say their advisor acts of their greatest curiosity solely a number of the time.
Hefty argued these descriptions map on to the three fashions in Cerulli’s analysis going from fee-only corporations to hybrid RIAs.
“I discover that ironic that … the fee-only mannequin, which has the 73% [satisfaction rate], is shedding market share, and the fashions that signify a mix in this sort of like this cloudy water of ‘I do not know should you’re a fiduciary or a dealer, I do not know what is going on on’ has the least satisfaction. And these are the market shares which are simply rising wildly,” he stated.
Perhaps not surprisingly, affluent Americans’ appetite for advice is rising throughout the board. The share of prosperous traders who contemplate themselves suggested rose from 35% in 2009 to 50% in 2025, and 69% now say they’re keen to pay for recommendation, Cerulli discovered.
What shoppers ought to ask about charges and fiduciary standing
Cerulli estimates the typical $1.5 million RIA shopper pays about 147 foundation factors a 12 months – 92 bps in advisory charges and 55 bps in funding product prices – earlier than commissions and different expenses. Still, a sizeable 15% minority of prosperous traders are uncertain how their supplier is paid.
From his veteran vantage level, Hefty stated expertise has eliminated a lot of the sensible obstacles for advisors who wish to turn out to be or keep fee-only.
“It’s by no means been simpler as an advisor to be full-service, complete, and fee-only,” he stated.
Clients on the lookout for an solely fiduciary relationhip, he stated, ought to ask three probing questions:
- How do you get compensated?
- What is the full value of investing?
- Do you act as a fiduciary in each single scenario?
He stated the primary could draw solely half a solution, and he clarified that prices typically climb at corporations that each manufacture merchandise and advise on them, notably as portfolios add illiquid alternatives.
“The complete value of investing truly goes up with wealth, not down,” he stated.
Private fairness retains the stress on
While he would not declare to have an ideal view of the long run, Hefty expects non-public fairness capital will hold lifting succession valuations, which in flip will hold the present shift going.
Some non-public equity-backed corporations depend conversions of present fee-based property into fee merchandise towards their natural progress targets, he added.
“You can simply shuffle the shell recreation and transfer issues out of a fee-based relationship with an present shopper, transfer it into commission-based, and it is truly been counted as natural progress on a progress hurdle in these contracts,” Hefty stated. “I do not see that pattern reversing or slowing down.”