Dwelling buyers face a bifurcated market as charges hit 7.4%
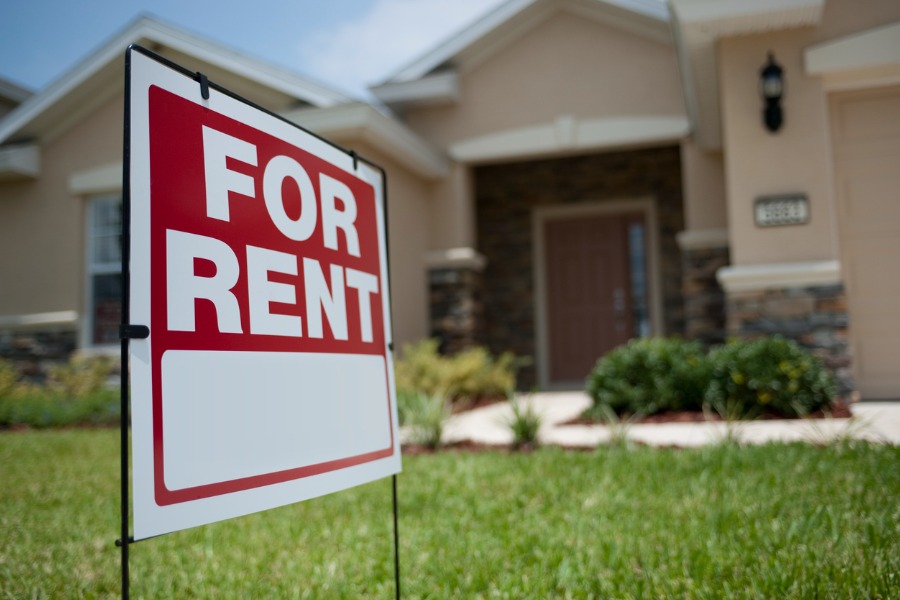
With shopping for prices hovering and rental demand surging, actual property buyers should rethink technique in a divided housing market.
The U.S. housing market despatched a pointy sign to house buyers this week: the for-sale aspect is stalling, and the rental aspect is accelerating.
Three new information releases, from Redfin, Zillow, and Realtor.com, paint a constant and consequential image for anybody with actual property of their portfolio.
The weekly common mortgage fee hit 7.4% on October 8, 2026, its highest stage in three years, in keeping with Redfin. The typical homebuyer’s month-to-month cost climbed to a report excessive of $2,777 pushed by elevated charges and residential costs that, regardless of softening, haven’t corrected meaningfully.
For actual property buyers who depend on financing, the price calculus has essentially shifted.
Buying strain is forcing capital towards leases
The penalties of seven.4% charges are enjoying out within the demand information. Pending house gross sales declined yr over yr in all 50 of essentially the most populous U.S. metro areas throughout the 4 weeks ending October 11, 2026, in keeping with Redfin; the primary time that has occurred in three years.
The median U.S. asking worth of a house on the market fell 0.3% yr over yr, the primary decline since March 2026, whereas 22% of sellers with lively listings reduce their asking worth, a report excessive in Redfin’s information.
For buyers, these figures counsel that the for-sale market is dropping pricing energy whereas the quantity of transactions stays suppressed. That mixture of fewer offers at softer costs constrains the short-term return potential for patrons in search of appreciation-driven positive aspects.
Rental demand, in the meantime, is operating in the other way. Zillow’s Observed Renter Demand Index rose 19.2% yr over yr in September 2026 as elevated borrowing prices pushed would-be patrons to hire as a substitute, in keeping with Zillow’s September 2026 Rental Market Report. Typical U.S. hire reached $1,932 per thirty days, up 2.7% yearly, however that determine understates the divergence between the price of renting and the price of shopping for.
“Elevated mortgage rates have pushed house customers straight into the arms of leases,” stated Kara Ng, senior economist at Zillow. “Homeownership has lengthy been a method for households to construct wealth, however with the rise in borrowing prices, we’re seeing the rise of the deliberate renter, somebody who chooses to financial institution the distinction between a purchaser’s month-to-month cost and hire and construct wealth with out proudly owning a house.”
The hole Ng is describing is important from an financial backing standpoint: the standard new homebuyer’s month-to-month cost has risen 5% yr over yr to $3,037, practically double the two.7% development in rents, in keeping with Zillow.
Single-family leases emerge because the clearest alternative
Zillow’s demand index for single-family leases rose 21.6% yr over yr in September 2026, greater than double the ten.1% improve recorded for multifamily items.
At a typical hire of $2,266, a single-family rental presents the area and way of life that aspiring householders need – with no down cost or the hidden carrying prices of possession – and prices $771 much less per thirty days than a typical new homebuyer’s cost.
For advisors working with purchasers who maintain financial backing properties or are contemplating including them, this information means that single-family leases in exchanges with robust inhabitants inflows could also be price a better look. The problem, as all the time, is financing: at 7.4%, the debt service on a rental property is considerably greater than it was even 18 months in the past, compressing yields and demanding tighter underwriting.
Realtor.com information provides geographic texture to the chance set. Its September 2026 Rent Report identifies three distinct forces reshaping rental demand: the cooling of a post-pandemic provide wave in Sun Belt metros, migration towards reasonably priced alternate options to high-cost cities, and AI-driven job development within the Bay Area.
Geography issues greater than ever for rental buyers
San Jose and San Francisco stand out. Median asking hire in San Jose rose 6.0% yr over yr to a brand new excessive of $3,565 in September 2026, whereas San Francisco hire elevated 4.8% to $3,057, in keeping with Realtor.com.
“Rising rents and vanishing concessions are a one-two punch for Bay Area renters,” stated Jiayi Xu, senior economist at Realtor.com. “The share of San Jose listings providing concessions has fallen by greater than half in a yr, from 51.9% to 24.3%, whereas rents have climbed to report ranges.”
Elsewhere, metros together with St. Louis, Minneapolis, Virginia Beach, Riverside, and Las Vegas have reversed course, shifting from year-over-year rental declines to positive aspects as affordability-seeking renters go away high-cost exchanges. St. Louis moved from a 4.4% annual decline to a 2.0% improve; Minneapolis from a 3.4% decline to a 1.7% acquire, in keeping with Realtor.com information.
In the Sun Belt, the information is extra measured. Austin’s annual hire decline narrowed from 7.8% in September 2025 to 2.3% in September 2026 because the post-pandemic development wave begins to exhaust itself. Investors who purchased into exchanges like Austin, Phoenix, or Orlando on the rental earnings thesis could discover circumstances stabilizing – although not reversing sharply of their favor.
The affordability hole defines the financial backing panorama
The widening hole between the price of homeownership and the price of renting has a direct implication for actual property buyers: sustained rental demand is probably going so long as charges keep elevated.
A family within the United States wants an earnings of roughly $77,278 to afford a typical rental versus roughly $121,496 to afford a typical house, in keeping with Zillow, a spot of greater than $44,000. That disparity doesn’t resolve shortly.
For advisors discussing actual property publicity with purchasers – whether or not by means of direct property possession, REITs, or actual estate-linked investment vehicles – the present atmosphere rewards an income-first, appreciation-second orientation.
Markets with robust employment fundamentals and restricted new provide are the place rental earnings is most defensible. Markets that absorbed heavy multifamily development in recent times, whereas nonetheless seeing declines ease, require extra endurance.
The information launched October 15, 2026, doesn’t describe a housing market in restoration however in transition and the place the economics of possession are more and more prohibitive and the economics of rental financial backing, in the proper exchanges, are more and more compelling.