351 exchanges nonetheless viable after IRS ruling, says Baird planning chief
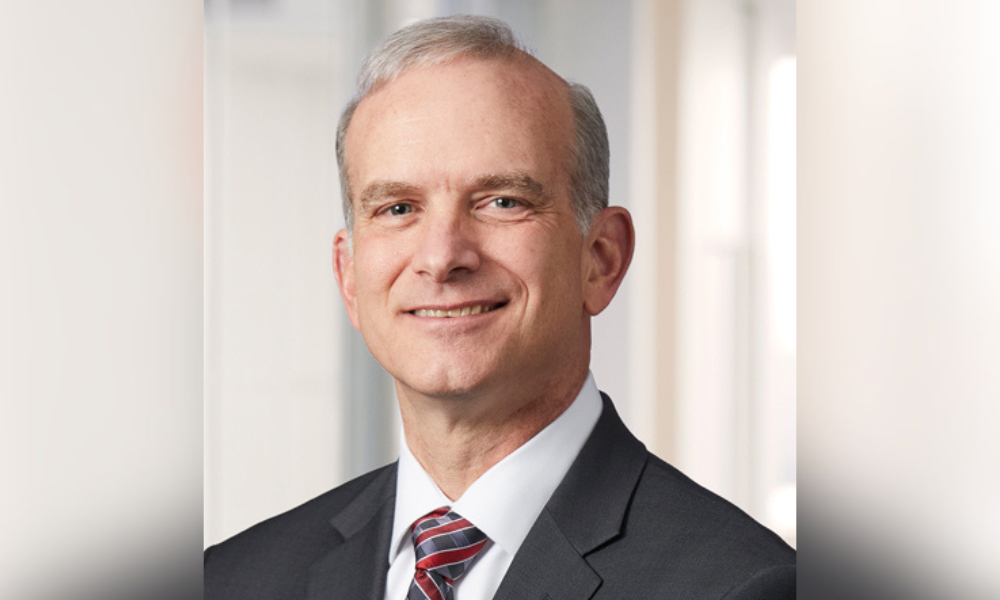
Tim Steffen, managing director and director of superior planning at Baird Private Wealth Management.
Advisors fielding shopper questions on the tax deferral technique cannot afford to skip the advantageous print, Baird’s Tim Steffen warns.
The IRS’s current ruling on 351 ETF conversions might take goal on the most aggressive makes use of of the technique, however correctly structured offers stay viable for the fitting purchasers, in keeping with Tim Steffen, managing director and director of superior planning at Baird Private Wealth Management in Milwaukee.
It’s been roughly two weeks for the reason that Treasury Department and the Internal Revenue Service issued Notice 2026-62 and its companion earnings ruling, Rev. Rul. 2026-20. On September 28, the IRS targeted 351 ETF conversions in new guidance that additionally flagged field unfold ETFs and different tax-aware fund methods.
For Steffen, the transfer was not completely surprising.
“They’ve form of alluded to this in some prior bulletins that a few of these methods had been issues that they’d their eye on,” Steffen instructed InvestmentNews in a current interview.
“In phrases of [the 351 conversion strategy] specifically, they are surely addressing among the most egregious misuses of it or abuses of it,” he added. Strategies designed solely for a tax profit, “with out an underlying asset placement thesis,” will draw the company’s consideration, he mentioned.
What the IRS ruling means for 351 exchanges
Section 351 of the Internal Revenue Code typically lets buyers switch property to a company in alternate for its inventory with out recognizing a capital acquire, supplied they meet management and diversification exams. A portfolio sometimes counts as diversified if no single issuer makes up greater than 25% of its worth and the 5 largest make up not more than 50%.
Rev. Rul. 2026-20 addresses offers through which buyers seed a brand new ETF with appreciated securities that do not match the fund’s technique. The ETF points shares to a licensed participant for securities that do match, then rapidly redeems these shares in form utilizing the buyers’ unique holdings. In these circumstances, the IRS treats the ETF as a conduit and recharacterizes the association as a taxable alternate.
The discover expresses no view on 351 offers that seed a brand new ETF with belongings in keeping with its asset placement thesis that the fund expects to maintain. Law agency Ropes & Gray famous the ruling carries no efficient date, suggesting the IRS sees it as present regulation that may attain accomplished transactions.
The market at stake has grown rapidly. More than 100 ETFs have been seeded in-kind underneath Section 351 since 2021, at the moment representing greater than $40 billion in AUM, in keeping with a tracker maintained by Tax Alpha Insider.
“[I think] if this stuff are executed correctly, they’re nonetheless viable,” Steffen mentioned. “It’s solely the abusive ones that they are actually going after. Now, the place they draw that line stays to be seen.”
Mohsen Ghazi, a companion at regulation agency Ashurst Perkins Coie, agrees that the Treasury is not trying to kill the technique altogether.
“It’s drawing a line between legit tax planning and methods that kind of manufacture tax outcomes by combining guidelines Congress designed for various functions,” Ghazi instructed InvestmentNews in an interview.
“Advisors shouldn’t assume a accomplished transaction is robotically invalid,” he added, “however they need to assessment how the transaction was structured – for these ETFs, whether or not the contributed securities had been meant to stay within the ETF, and what tax evaluation supported the transaction.”
Why shopper curiosity fades after the headlines
As Steffen tells it, Baird has fielded a gradual stream of questions on 351 exchanges over the previous 12 months from purchasers desirous to know extra. That inbound curiosity not often develops into motion, he says, as folks get educated.
“When folks learn the headlines of what these are, they get very ,” he mentioned. “I feel many of the preliminary wave of curiosity in these died off some as soon as folks higher understood the way it labored.”
Advisors who name him have often learn cautious protection of the technique, Steffen mentioned. But questions that begin with purchasers, he says, “have a tendency to return from the much less respected sources. The individuals who promote the advantages with out speaking concerning the particulars. And that is the place individuals are getting misled.”
The commonest false impression entails a single concentrated holding. “So usually it is someone who has inventory in a single firm that has executed rather well, they usually’re considering they’ll commerce that inventory for an ETF,” Steffen mentioned. “But … it needs to be a portfolio of shares that need to be diversified.”
The minimums wanted to get into the methods are often bigger than many purchasers will commit, he added. For its half, Baird is anxious concerning the funds themselves, which launch with no monitor report.
“These haven’t any historical past behind them,” Steffen mentioned. “You do not have something we will look to as to how they are going to be run.”
Steffen added that many purchasers misinterpret what the technique really does.
“This is just a tax deferral method. It’s not a tax elimination method,” he mentioned, describing it as a diversification instrument that does not set off taxes instantly. “There’s different good methods to do this [tax deferral]. This one is not the one which works for most individuals.”
Baird itself would not supply 351 merchandise, and Steffen mentioned each advisor or shopper he is walked by the brass tacks got here away feeling it wasn’t a match, although he emphasised “[that] doesn’t suggest it will possibly’t occur. It simply hasn’t occurred to me but.”
In the meantime, he expects sponsors touting 351 conversion methods are at the moment in scramble mode as they work to point out the IRS the place legit offers sit on one hand, whereas on the similar time reassuring potential purchasers that “what they’re coming after just isn’t what they do.”
The Treasury has opened a session interval on the brand new steering, with feedback from involved stakeholders due by October 28. While the end result from that course of stays to be seen, Ghazi sees a number of potential subsequent steps for the Treasury Department to pursue.
“It might all the time subject rules or further rulings that make clear the substantive tax therapy, they usually might designate sure methods as transactions that you must report back to the IRS or problem explicit preparations right now underneath present regulation,” he mentioned. “It may very well be potential; it may very well be retroactive.”
As for advisors, Steffen provided a agency and direct message.
“If you are going to promote a product that has tax benefits, you must perceive the disadvantages too. How can this stuff go proper and the way can they go mistaken?” he mentioned. “The days of advisors saying, that is a tax query, I am unable to reply that, are gone.”