GLP-1 customers are buying and selling retirement financial savings for his or her prescriptions
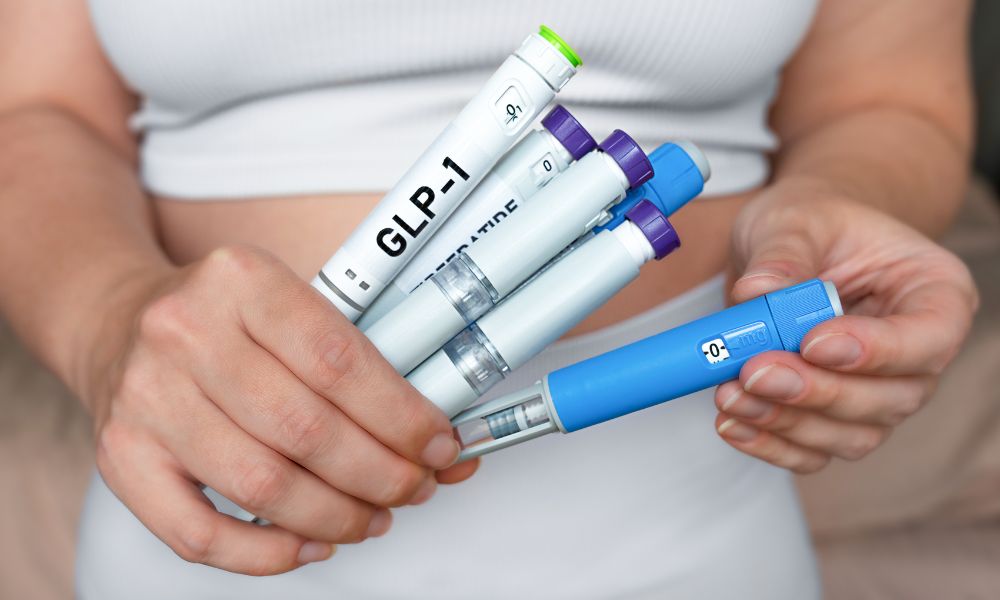
A Nationwide survey finds 47% of GLP-1 customers have by no means mentioned the medication’ monetary influence with an advisor, whilst many dip into financial savings.
Half of Americans taking GLP-1 drugs fear they must select between staying on the drug and saving sufficient for retirement. A rising share has already made that alternative.
A new survey from the Nationwide Retirement Institute, launched Oct. 7, 2026, discovered 51% of present GLP-1 customers concern that tradeoff, and 54% have already modified their monetary habits to afford the remedy. Seventeen p.c have taken on debt, 14% have pulled cash from financial savings, investments or retirement accounts, and 14% have lower their retirement contributions.
The Harris Poll ran the net survey for Nationwide between July 20 and Aug. 4, 2026, amongst 1,933 U.S. adults, with further samples of 509 present and 364 former GLP-1 customers. Users whose insurance coverage doesn’t totally cowl the drug pay a mean of $203 a month out of pocket.
“Medical innovation is altering how we take into consideration dwelling longer and more healthy, and that’s an excellent factor. But dwelling longer additionally means your cash could have to last more,” mentioned Kristi Martin Rodriguez, chief of the Nationwide Retirement Institute. “If what you’re spending in your well being at the moment is competing with what you’re saving for tomorrow, that must be a part of the financial planning dialog.”
GLP-1 optimism is making a retirement planning hole
Eighty-eight p.c of present customers say GLP-1s make them extra optimistic about their long-term well being, and 64% say they might retire later as a result of they really feel more healthy.
That optimism is easing the strain to avoid wasting. Fifty-nine p.c of customers say the anticipated well being advantages make them really feel much less urgency to extend retirement financial savings, and 57% say they’re much less nervous about needing further well being or long-term care insurance coverage.
The similar respondents additionally see the catch. Fifty-six p.c say they might want more cash for healthcare in the event that they stay longer, and 49% say the prospect of an extended life makes them much less assured of their retirement plan. Fifty-nine p.c fear about affording the remedy itself as soon as they cease working.
Those numbers land on high of present strain. Fidelity’s twenty fifth annual estimate places lifetime healthcare costs for a 65-year-old retiree at $185,500, a 7.5% soar from the prior yr, and that determine excludes long-term care. A consumer who stays more healthy and lives longer on a GLP-1 extends the interval these prices must be funded.
Clients getting into Medicare face an added variable. The Centers for Medicare & Medicaid Services launched its GLP-1 Bridge program on July 1, 2026, giving eligible Part D enrollees entry to sure weight-loss GLP-1s for a $50 month-to-month copay with prior authorization. The program is scheduled to finish Dec. 31, 2027, and the protection image after that continues to be unsettled.
Clients count on advisors to lift it
The survey factors to a service hole advisors can shut. Fifty-nine p.c of present customers count on a monetary skilled to advise them on the monetary influence of GLP-1s and different well being improvements. Forty-seven p.c have by no means mentioned the subject with one.
Surveys monitoring client fears about outliving their savings now cite GLP-1s alongside synthetic intelligence as a purpose longevity assumptions want revisiting. A separate Northwestern Mutual research discovered Americans who work with an advisor are way more more likely to have a plan in place for long-term care than those that don’t.
“The connection between well being and wealth has by no means been extra obvious than with the rise of GLP-1 drugs,” Rodriguez mentioned.
Nationwide is pitching its Health Care Cost Assessment device, which makes use of well being threat evaluation and actuarial value knowledge to venture medical and long-term care bills, as a approach for advisors to start out these conversations. The purchasers most probably to wish them, these quietly drawing down retirement accounts to remain on the remedy, are additionally the least more likely to deliver it up first.