Wealth managers see payoff in leaving money as Fed hikes
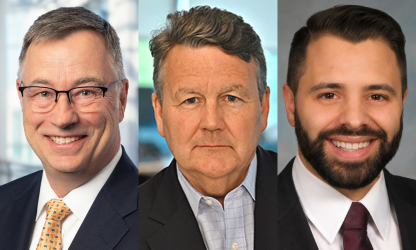
Bond specialists at Touchstone, Aberdeen and Altium Wealth favor high quality credit score and measured length over reaching for yield
The Federal Reserve’s first charge hike in three years has made money look extra snug than ever. Three mounted earnings specialists say that’s the unsuitable lesson for advisors to take. Higher bond yields, they argue, let buyers lock in earnings for years with out huge bets on length or reaching down in credit score high quality.
The Federal Open Market Committee voted 12–0 to boost the goal vary for the federal funds rate by 1 / 4 level to three.75% to 4% on Sept. 16, 2026, in keeping with the Fed’s official coverage assertion. It was the Fed’s first rate hike since July 2023, and it got here after three members dissented in favor of a hike in July, as recorded within the minutes of the July 2026 FOMC assembly. Most policymakers projected not less than yet one more hike earlier than year-end, and advisors are bracing for what may very well be the primary of a number of hikes.
That leaves advisors fielding a well-recognized consumer query: why purchase bonds when cash market funds pay nicely? Three specialists say the price of ready for readability is rising.
Why intermediate bonds are drawing mounted earnings managers
Erik Aarts, vp and senior mounted earnings strategist at Touchstone Investments, favors the intermediate a part of the Treasury curve. There, buyers can accumulate significant earnings with out the added interest-rate threat of the lengthy finish. Higher beginning yields, he stated, give portfolios way more cushion towards charge swings than that they had for a lot of the previous decade. But heavy federal borrowing and rising personal demand for capital might preserve strain on longer-term actual yields. That demand consists of spending on AI roads. As a end result, he’s affected person about extending length aggressively.
“Our desire is subsequently for measured length publicity, concentrated in intermediate maturities, fairly than making a big directional guess on the place charges go subsequent. We count on earnings, fairly than worth appreciation, to be the first driver of bond returns on this higher-for-longer setting,” Aarts stated.
He added that buyers do not want a “heroic length name” to maneuver past money. The Treasury curve stays positively sloped, with notable steepening between cash-like maturities and the two- to three-year section. Investors can add yield just by stepping out incrementally.
“While we finally favor intermediate maturities, we predict the extra vital resolution right this moment is to start placing extra money to work fairly than ready for excellent readability from the Fed. Moving out the curve permits buyers to lock in right this moment’s larger yields for longer, whereas money yields can reset comparatively rapidly if short-term charges finally decline,” he stated.
Miguel Laranjeiro, funding director for municipal debt at Aberdeen Investments, nevertheless, reaches a special structural reply. He sees worth on the entrance finish for earnings and liquidity. In municipals, he factors to the 8- to 15-year vary, the place yields and roll-down potential stay enticing.
“We typically favor a barbell method that mixes shorter-maturity publicity with selective longer-duration positions fairly than concentrating threat in the midst of the curve,” Laranjeiro stated.
What does staying in money price purchasers?
Money market funds nonetheless provide interesting nominal yields, Laranjeiro stated. But they supply little room for capital appreciation, and their earnings can fall rapidly as soon as coverage charges flip decrease.
“By remaining fully in money, buyers might miss the chance to lock in enticing yields which might be out there additional out the curve right this moment. In municipals, investment-grade bonds are at present yielding roughly 6.9% on a taxable-equivalent foundation, ranges that examine favorably with long-term historic averages and supply buyers with a chance to safe enticing after-tax earnings,” he stated.
For Paul Bucci, associate and head of mounted earnings at Altium Wealth, a associate to Hightower Advisors, the consumer dialog typically begins with disappointment. He stated five-year returns by way of July 2026 have are available in under 1% for 3 classes: intermediate U.S. authorities bonds, investment-grade corporates and high-quality municipals. That file has led some purchasers to query why they personal bonds in any respect.
“When constructing a portfolio, beginning yields are an excellent predictor of future efficiency when buyers maintain bonds to maturity. We can construct a portfolio of top of the range, intermediate time period company bonds with a median yield over 5.5%,” Bucci stated.
That view strains up with latest analysis from FTSE Russell on beginning Treasury yields. The analysis discovered that beginning yields carry robust correlation with subsequent efficiency throughout Treasury maturities.
Bucci’s foremost concern with money is reinvestment threat. “If the Federal Reserve decides to chop quick time period charges subsequent yr, cash market yields will rapidly transfer decrease and buyers could have missed the chance to lock in larger yields for a number of years,” he stated.
The Fed’s personal projections level the opposite means within the close to time period, which might preserve cash market yields elevated some time longer. The managers’ argument is much less about timing the subsequent transfer than about securing right this moment’s yields earlier than the cycle turns.
High-yield spreads provide skinny reward for credit score threat
None of the three sees a must tackle way more credit score threat. Aarts stated high-yield spreads stay comparatively tight. Investors are paid much less for incremental threat, despite the fact that absolute yields look enticing.
“We proceed to see enticing alternatives in high-quality company and securitized credit score, the place buyers can earn extra yield whereas sustaining higher resilience if the macro economy slows,” he stated.
Bucci shares the priority. He famous that high-yield spreads sit close to traditionally tight ranges. Heavy company issuance in 2026 to fund AI-related capital spending provides to the danger that they widen. His reply is to diversify return drivers with out dropping in high quality.
“We would like to remain in higher-quality bonds whereas in search of totally different drivers of returns. This would possibly embody including floating-rate securities, junior subordinated hybrid debt and short-dated convertible bonds to enhance core positions in U.S. Treasuries, investment-grade company bonds, mortgage-backed securities and municipal bonds,” Bucci stated.
Laranjeiro is considerably extra open to credit score. Investment-grade municipals yield roughly 6.9% on a taxable-equivalent foundation, he stated. High-yield municipals yield roughly 9.3%, a significant premium for buyers keen to maneuver down the spectrum selectively.
“We proceed to see enticing alternatives in higher-quality segments of the high-yield market, significantly amongst BBB- and BB-rated issuers the place buyers can typically earn extra earnings with out taking up the dangers related to the lowest-rated credit. In our view, the bottom line is selectivity and disciplined credit score analysis fairly than merely reaching for yield,” he stated.