Investors keen to purchase into the futuristic vision of profitable driverless vehicles will get their chance soon. May Mobility is aiming to change into the primary U.S. publicly listed pure-play choice for an autonomous ride-hailing know-how firm. It is poised to go public by a particular goal acquisition firm (SPAC), merging with ACP Holdings Acquisition (NASDAQ: ACGC) that values the mixed firm at roughly $1.4 billion.
It’s anticipated to function as May Mobility. buying and selling on the Nasdaq alternate below MAY. But earlier than buyers get too excited, let’s pump the brakes and try the main points.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most buyers suppose they missed the AI boat as a result of they did not purchase Nvidia in 2005. But based on our analysts, we’re solely on the finish of “Act 1″—the R&D section. “Act 2” is the worldwide rollout. Continue »
Opportunity knocks
It’s straightforward for buyers to get excited in regards to the alternative, however many may not concentrate on the potential market dimension or progress prospects. The international robotaxi market is projected to succeed in about $415 billion by 2035, with the U.S. accounting for a roughly $48 billion slice of that pie. The fleet of U.S. industrial autonomous autos (AVs) is projected to develop from solely about 4,000 autos at present to round 35,000 by 2030 — or about 8% of the ride-sharing market.
A yr in the past this month, Bank of America projected that the long-term U.S. complete addressable market (TAM) for AV ride-hailing is a trillion-dollar alternative as corporations equivalent to May Mobility intention to interchange the drivers that take roughly 70% of each fare. It’s additionally vital for buyers to comprehend how early within the sport that is: Alphabet‘s Waymo, with an estimated $350 million in annualized earnings, would symbolize solely about 0.5% of U.S. ride-hailing bookings.
The alternative is probably profitable, albeit nonetheless very early within the sport. So, what makes May Mobility intriguing?
An asset-light transition
May Mobility is shifting to an asset-light mannequin. At the corporate’s preliminary U.S. ride-hailing launch web site, it estimates the prices for the security driver; autos (financing, depreciation, insurance coverage, upkeep); web site operations (gasoline/charging, depot operations, and workers); and distant automobile supervisors, software program upkeep, and subject engineers. In this asset-heavy state of affairs, May Mobility’s projections put its annual earnings per automobile between $130,000 to $150,000, because it retains all of the earnings. But as a result of it additionally incurs all the prices, it checks in with a destructive gross margin per automobile with a security driver.
Under its asset-light mannequin, which incorporates eradicating the security driver, May Mobility transfers the automobile prices in addition to the positioning working prices to a fleet working accomplice, though it’s going to nonetheless incur the prices for distant supervisors, subject engineers, and software program upkeep.
This state of affairs would include a bigger fleet dimension due to a fleet-operator accomplice, and decrease earnings ($50,000 to $72,000 per automobile) because it splits the gross sales with that accomplice. But it checks in with a gross margin per automobile between $35,000 to $50,000 yearly as a result of it will push off important prices and will scale up extra shortly with no need to buy and personal the fleet.
There’s additional upside with administration concentrating on a 50% discount in its invoice of supplies (BOM) by the tip of 2028. That’s from cost savings realized through computing and sensors with next-generation chip options and as lidar/radar/digicam bourses scale up and mature.
May Mobility additionally expects to cut back its BOM by value reductions in {hardware} elements and integration when its software program might be put in by the unique tools producer (with Toyota as a accomplice for AV-ready automobile platforms at scale) relatively than putting in it in autos afterwards. Over the long run with out drivers, administration is concentrating on gross margins of about 70%, and margins below earnings earlier than curiosity and taxes round 30%.
How going public helps
When the SPAC deal and merger closes, it might present May Mobility with as much as $337 million in funding. Investors can have a look at the economics and do the mathematics: In 2025, the corporate generated roughly $10 million in earnings with a 27% gross margin, whereas burning $93 million in money. The SPAC funds ought to allow it to strengthen its stability sheet and liquidity, finance added analysis and improvement, spend money on the availability chain to cut back prices, and launch new in bourses with out drivers. However, with no main money pile, the money burn might erode its liquidity relatively shortly.
What all of it means
It’s an thrilling time in an automotive business that is poised to evolve quickly over the subsequent decade. However, buyers should perceive that that is an exceptionally high-risk financial backing at present. May Mobility’s 27% gross margin is an encouraging starting, however the money burn is important and can solely improve within the close to time period. It will rely closely on the $337 million of recent capital from its public debut, and that would erode quickly.
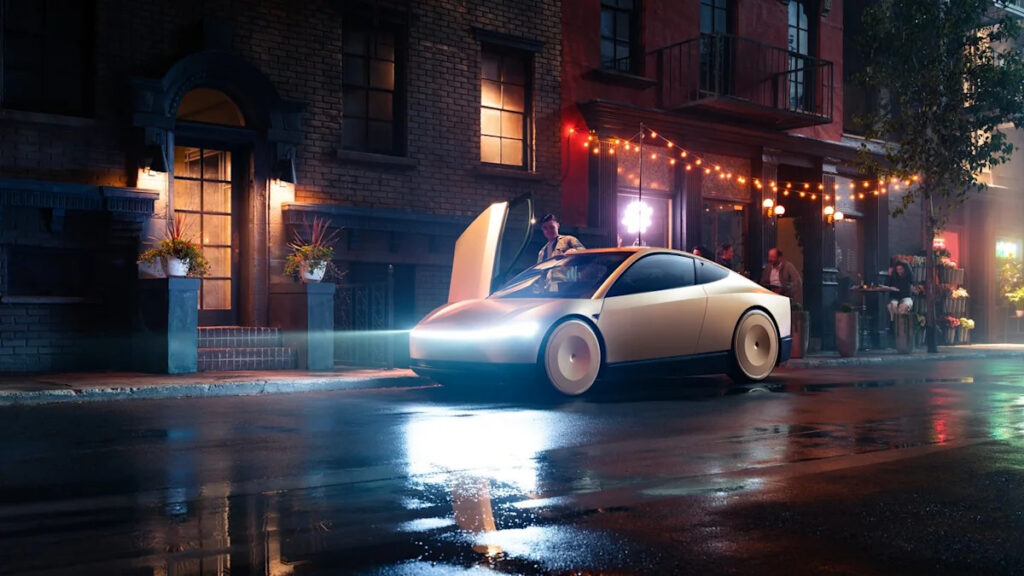
Investors even have to think about that regardless of being within the early innings, there are some heavyweights accelerating ahead, together with market chief Waymo and Tesla‘s sluggish however regular progress with its Cybercab commerce.
Tesla’s Cybercab. Image supply: Tesla.
May Mobility is intriguing, however this solely scratches the floor. Potential shareholders should learn by the investor presentation, available here, and acknowledge that this might finish in a complete loss. For now, this needs to be an organization that almost all retail buyers watch curiously from the sidelines, particularly as this debut assessments investor demand for a pure-play AV ride-hailing firm.
Should you purchase inventory in ACP Holdings Acquisition Corp. proper now?
Before you purchase inventory in ACP Holdings Acquisition Corp., think about this:
The Motley Fool Stock Advisor analyst crew simply recognized what they consider are the 10 best stocks for buyers to purchase now… and ACP Holdings Acquisition Corp. wasn’t one in every of them. The 10 shares that made the lower might produce monster returns within the coming years.
Consider when Netflix made this checklist on December 17, 2004… in the event you invested $1,000 on the time of our suggestion, you’d have $395,625!* Or when Nvidia made this checklist on April 15, 2005… in the event you invested $1,000 on the time of our suggestion, you’d have $1,397,147!*
Now, it is price noting Stock Advisor’s complete common return is 951% — a market-crushing outperformance in comparison with 214% for the S&P 500. Don’t miss the newest high 10 checklist, accessible with Stock Advisor, and be a part of an investing group constructed by particular person buyers for particular person buyers.
Bank of America is an promoting accomplice of Motley Fool Money. Daniel Miller has no place in any of the shares talked about. The Motley Fool has positions in and recommends Alphabet and Tesla. The Motley Fool has a disclosure policy.