Bank of America is sticking with its Buy score on Meta Platforms (META) inventory after an early AI shock started altering how traders view the corporate’s tech spending.
That shock is Muse, Meta’s shopper AI assistant, launched on Sept. 8. The app can browse web sites, set up e mail, and full multi-step duties with restricted person intervention, pushing Meta past chatbots towards a sensible digital agent.
Early adoption has given the bull case momentum, whereas the sturdy preliminary numbers add weight to the argument that Meta may flip billions in AI transport systems spending right into a differentiated shopper product.
Muse is starting to offer a solution, nevertheless it stays early. Nevertheless, it appears traders are catching on, with Meta inventory rising an amazing 36% over the previous month, dwarfing the broader market beneficial properties of simply 1.2%, in response to Seeking Alpha data.
BofA however believes the launch has strengthened Meta’s AI trajectory and improved the case for its inventory.
BofA says Muse can reprice Meta’s AI story
Bank of America reiterated its Buy score on Meta Platforms and set an $810 value goal. That represents 9.3% upside from the agency’s $741.25 reference value, though the potential return narrows to roughly 8% utilizing the Sept. 22 intraday value.
More AI:
In a BofA word shared with The Street, the corporate mentioned its new Muse providing would possibly lastly put to relaxation lots of the issues surrounding Meta if it could possibly ship a differentiated shopper product.
The early numbers look promising.
Citing Sensor Tower, BofA mentioned Muse surpassed 2.5 million cumulative U.S. downloads by Sept. 19 and reached roughly 557,000 day by day energetic customers. Its 1.43 million iOS downloads by way of day 12 additionally edged ChatGPT’s 1.37 million on the identical stage.
Muse’s capability to execute multistep duties, together with managing e mail, reserving journey, and finishing transactions, separates it from typical chatbots. Moreover, Meta can finally promote the agent throughout its platforms, serving 3.6 billion day by day customers, creating a robust distribution benefit few opponents can match.
Independent testing discovered Muse genuinely helpful however probably uncomfortable as a result of private entry it requires.
That mentioned, sturdy retention may raise Meta’s valuation earlier than Muse contributes significant income, however downloads alone won’t show lasting demand.
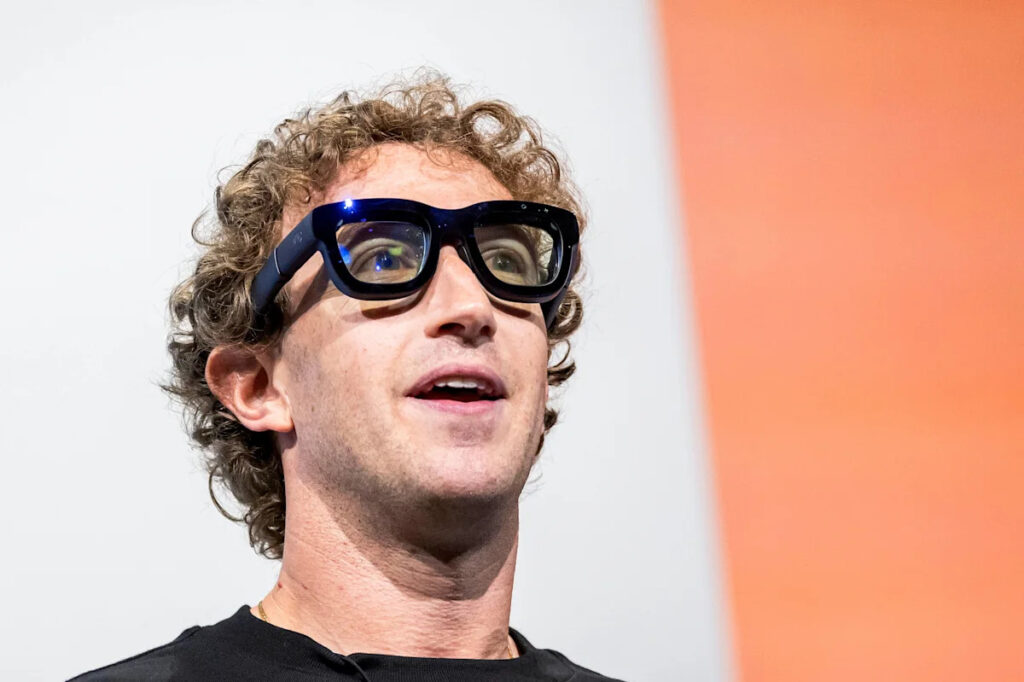
Bank of America backs Meta inventory as Muse beneficial properties sturdy early traction.Bloomberg / Getty Images
Meta faces a multibillion-dollar compute resolution
Muse additionally raises an necessary query for Meta: Should it use its restricted AI computing energy for its personal merchandise or promote that capability to outdoors clients?
In its word, BofA estimates that exterior leasing may generate as much as $40 billion per gigawatt, primarily based on latest business transactions. Leasing would create seen income and supply quicker proof that Meta’s transport systems buildout can earn a suitable return.
Management, nonetheless, believes shopper brokers and AI-enhanced promoting may in the end create higher worth.
More AI:
The stakes are large, to say the least. Meta expects 2026 capital expenditures of $130 billion to $145 billion, in contrast with $72.22 billion throughout 2025, Reuters famous. Every unit of compute is subsequently an opportunity-cost resolution, not only a technical allocation.
Muse presently gives a free tier alongside $20 and $100 month-to-month subscriptions. BofA doesn’t anticipate subscriptions, promoting, or commerce commissions to change into financially significant earlier than 2028.
On the flip facet, Jefferies illustrated the longer-term alternative in a different way. Its state of affairs assumes one billion customers by the top of 2027 and three% paid conversion, producing $10.8 billion in annualized income.
Prioritizing Muse, subsequently, sacrifices probably profitable leasing earnings for a broader platform wager spanning subscriptions, commerce, APIs, and promoting.
Early engagement will assist decide whether or not that commerce pays off.
Investor takeaway: Meta’s execution should catch valuation setup
Meta inventory now not carries the deep low cost that protected traders earlier within the yr. BofA mentioned shares commerce close to 21 occasions its 2027 earnings estimate, up from roughly 16 occasions a number of months in the past.
Its $810 goal applies a 24-times a number of to estimated 2027 GAAP earnings, representing a slight premium to the S&P 500. With solely about 8% upside from the intraday stage on Tuesday, Sept. 22, the margin for disappointment has narrowed significantly.
That makes Muse a supporting catalyst moderately than a whole financial backing thesis. Investors have to see downloads translate into sturdy utilization, paid subscriptions, commerce exercise, or measurable promoting beneficial properties earlier than pricing in additional a number of growth.
The dangers are interconnected.
Muse requires entry to delicate accounts, creating privateness and belief issues. Amazon has already blocked the agent from purchasing on its platform, demonstrating how third-party restrictions may weaken Muse’s usefulness and commerce ambitions.
Meanwhile, Meta’s $130 billion to $145 billion spending plan pressures free money movement and raises the price of misjudging AI demand. Investors ought to monitor retention, paid conversion, task-processing prices, companion entry, and 2027 spending steering.
Muse has improved Meta’s AI narrative. At this valuation, nonetheless, it should change into a monetizable behavior as an alternative of simply a formidable demonstration.