Lockheed Martin (LMT) Is Spending Ahead on JATM. Will a Multiyear Contract Observe?
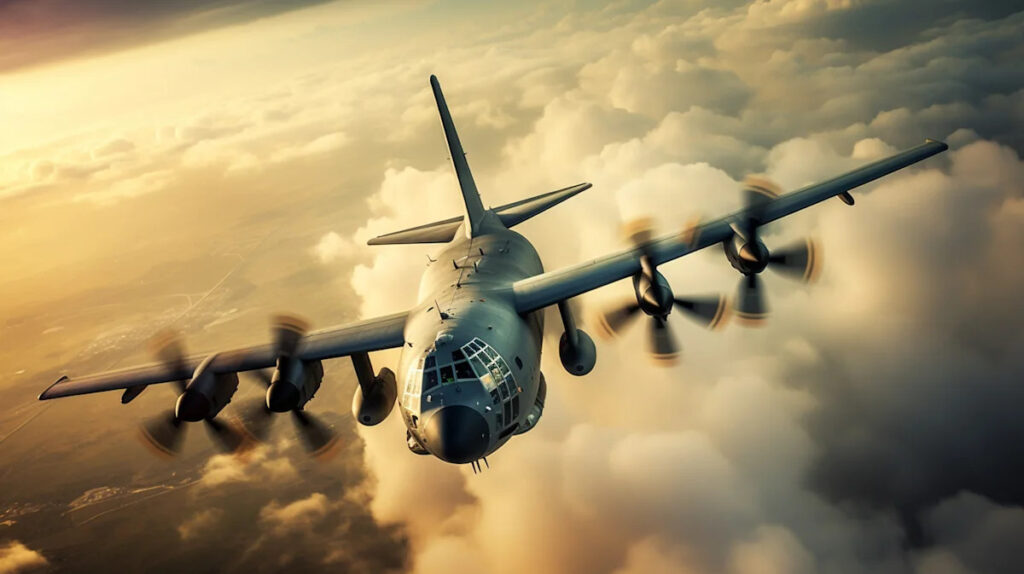

Lockheed Martin Corporation (NYSE:LMT) signed a framework settlement with the U.S. Department of War on September 17 to speed up manufacturing of the AIM-260 Joint Advanced Tactical Missile (JATM). The weapon is described as essentially the most refined U.S. air-to-air system and a direct response to China’s air risk. The settlement supplies a long-term demand sign and suggests robust institutional confidence within the want for the missile. However, the extra essential problem for traders is whether or not that anticipated demand will translate into secured orders. The framework nonetheless requires Congressional approval earlier than it might probably turn into a multiyear procurement contract, and neither the corporate nor the Department of War disclosed a greenback worth or particular manufacturing goal.
Lockheed Invests Ahead of a Multiyear JATM Contract
The framework settlement is meant to set the stage for a future multiyear procurement contract, whereas Lockheed Martin is supporting capability investments itself forward of the proposed multiyear procurement contract. JATM is predicted to supply prolonged vary in contrast with the AIM-120 AMRAAM and is suitable with the F-22 and F-35. Tim Cahill, president of Lockheed Martin Missiles and Fire Control, mentioned the labeled program is lastly being mentioned publicly.
We’re proud to lastly discuss concerning the extraordinary work behind this missile and the way we’re working with the U.S. authorities to quickly scale manufacturing.
The settlement additionally follows Australia’s roughly A$736 million dedication to JATM as this system’s first transnational buyer, together with the corporate’s latest IDIQ contract ceiling for the Army’s PrSM Increment 2. Together, these developments assist the broader development of strengthening missile demand.
A Demand Signal Without a Final Multiyear Contract
The framework just isn’t itself the proposed multiyear procurement contract, which leaves essential particulars concerning the alternative unresolved. The Aviationist and Military Times have each famous that the events have but to reveal a contract worth, manufacturing goal, or timeline. Separately, Simply Wall Street has warned that Lockheed Martin’s transfer towards self-funded, anticipatory capability might increase execution and stock threat if anticipated demand doesn’t absolutely materialize. Meanwhile, The Motley Fool has highlighted bipartisan political criticism over protection contractors emphasizing buybacks relatively than deliveries. Rising federal debt might additionally place additional strain on protection budgets sooner or later.
According to our database, hedge fund possession of Lockheed Martin fell from 83 on the finish of Q1 2026 to 75 on the finish of Q2 2026. Despite the pullback in hedge fund publicity, brief curiosity stays modest at 1.39% of float as of August 31, 2026. Taken collectively, the figures counsel some cooling in hedge fund participation, whereas modest brief curiosity suggests restricted outright bearish positioning towards the inventory. For LMT, the upside now is dependent upon whether or not Congress turns the framework right into a funded multiyear contract.