America’s wealth increase is creating a brand new technology of underinsured shoppers

The US accounted for practically half of all new millionaires worldwide final yr, however insurance coverage specialists warn wealth development is outpacing planning.
The US minted greater than 440,000 new millionaires in 2025 – over 1,200 a day – in response to the UBS Global Wealth Report 2026, as surging fairness exchanges and a wave of liquidity occasions quickly expanded the nation’s prosperous inhabitants. The US accounted for practically half of all new millionaires worldwide.
But insurance coverage specialists warn that most of the newly rich are strolling right into a danger panorama they are not geared up for, carrying insurance policies designed for an earlier, leaner stage of life.
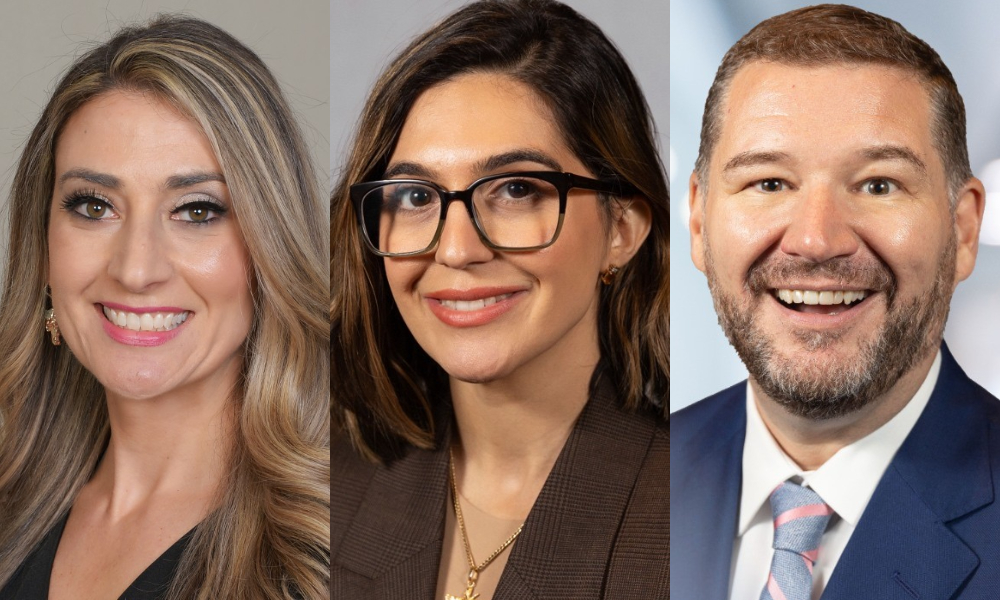
“More people and households are experiencing significant wealth growth, whether or not by means of the sale of a trade, fairness compensation, inventory appreciation or different liquidity occasions,” stated Diane Delaney (pictured on the best), govt director of the Private Risk Management Association (PRMA). “Many transition into the high-net-worth market with out realizing they’ve outgrown their insurance coverage program. Their wealth has modified, however their insurance coverage usually hasn’t.”
Wealth hasn’t but translated into belongings
Part of what makes this second uncommon is that a lot of the brand new wealth continues to be on paper. Jason Ott (pictured on the left), president of personal danger administration at Aon, stated the insurance coverage implications have not absolutely landed as a result of so much of the gain is still sitting in the market.
“We have not seen a dramatic shift but as a result of lots of people’s wealth continues to be tied up within the inventory market,” Ott stated. “I feel over the subsequent 18 months we will see a fairly dramatic improve in folks making purchases.”
Those purchases are anticipated to incorporate second properties, luxurious automobiles, jewellery, paintings and different collectibles, all of which require extra specialised insurance coverage preparations than customary private strains insurance policies.
Yas Nahali (pictured within the center), senior vp at Amwins, stated rising wealth calls for greater than a routine renewal. “As private wealth grows, shoppers might want to do a radical deep dive into their insurance coverage packages,” she stated. “Their portfolio is greater than only a easy annual assessment at this level and requires a broader safety technique that’s custom-made to suit their life-style, general monetary safety and the legacy they want to depart behind.”
Nahali stated essentially the most lively areas she sees are tangible belongings in catastrophe-exposed areas (i.e., waterfront, coastal, or distant high-brush and mountain properties) alongside accumulating valuables akin to watches, purses, artwork and wine. On the casualty aspect, she’s fielding requests for increased limits in opposition to nuclear verdicts and for cyber, crime, identity-theft and kidnap-and-ransom cowl.
Liability dangers a rising concern within the HNW house
Expensive properties and jewellery get consideration. Liability, the specialists agree, is the publicity folks underestimate most. “As wealth will increase, so does visibility,” Delaney stated, noting that wealth can form how a defendant is perceived in litigation.
At wholesale brokerage Amwins, Nahali famous ”continued requests for increased limits of safety in opposition to nuclear verdicts in addition to Cyber/Crime protection akin to ID theft, kidnap & ransom, monetary fraud response protection,” amongst different coverages.”
Ott expects umbrella protection to change into a first-order concern for newly rich households, as a result of many are coming from major insurance policies with private legal responsibility limits of $300,000 to $1 million. “For most individuals, a $1 million umbrella coverage is nice,” he stated. “(But) for those who’re an prosperous particular person, I feel $5 million to $10 million is the place you need to be. If you are within the ultra-high-net-worth house, it’s best to definitely be taking a look at limits as much as $50 million, relying in your internet price.”
Why brokers and advisors ought to convey up umbrella protection
But shopping for an enormous umbrella is not the identical as being lined. This, Ott stated, is the place the brand new millionaires are most uncovered.
An umbrella sits above underlying auto and residential insurance policies, and it solely kicks in as soon as these insurance policies meet a required “attachment level,” sometimes $300,000 or extra of auto legal responsibility, or a set owners restrict. If the underlying coverage falls quick, the shortfall is the policyholder’s downside.
“You might need a $5 million umbrella sitting over an auto coverage,” Ott stated. “The umbrella requires the auto coverage to have $300,000 in legal responsibility protection, however the coverage solely has $100,000. If there have been a loss, you’d have a $200,000 hole that the person could be personally chargeable for.”
It’s one of the crucial frequent defects Aon finds when reviewing an incoming consumer’s program. “Before we even end our assessment, we’ll name the consumer and say, ‘You must contact your insurance coverage dealer proper now. You have a spot in protection.'”
The hole is normally a information downside, not a pricing one, Ott stated. Direct-to-consumer auto insurers usually ship financial savings partly by quietly reducing legal responsibility limits, and patrons do not join that to the umbrella sitting above it. The premium distinction between $100,000 and $300,000 of legal responsibility is usually solely 100 or just a few hundred {dollars} a yr.
The largest insurance coverage mistake new millionaires make
The frequent sample the three specialists flagged: insurance coverage planning trails monetary success, and the correction normally comes solely after a dealer intervenes or a loss exposes the hole.
“The largest mistake we see is lack of preparation main into accumulation of wealth,” Nahali stated. “In most circumstances the buildup occurs so rapidly the consumer will not be ready for the upfront prices of premiums or fail to spot the worth of safety initially.”
Delaney concurred: “Someone should have the identical insurance coverage provider and protection they bought years in the past, earlier than their monetary scenario modified. They should have a normal private insurance coverage coverage that served them effectively of their twenties, however immediately they personal a higher-value residence, a luxurious automobile, helpful jewellery or paintings, and have considerably better legal responsibility publicity.”
For Ott, the fix is having the right people in the room earlier than the belongings arrive. “You want a very good monetary advisor and a very good insurance coverage dealer who perceive these points and may put the correct program in place.”