Is unlisted investing a lotto? The story of a NSE financier who purchased shares at Rs 1,827
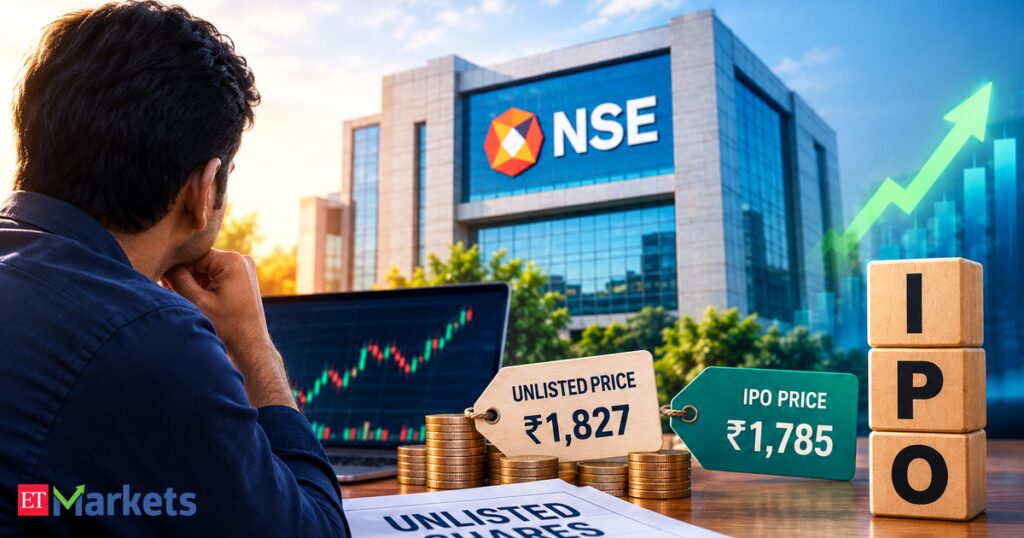

If all 500 shares are cost the upper cost band, the cost distinction would exercise to about Rs 20,925. In portion terms, the IPO cost has to do with 2.3% lower than his acquisition expense. The quantity might look little in Gupta’s case since the amount is restricted. But the example reveals a bigger problem for financiers in the unlisted market: the cost at which a stock trades before an IPO might not constantly be the cost at which it pertains to the general public market.
NSE has actually been among the most actively brand name in India’s unlisted market for several years. Its shares brought in need from organizations, household workplaces, brokers, wealth supervisors and private financiers since of the exchange’s dominant position in Indian equities and derivatives.
Also Read: Why can’t NSE trade on its own platform after the IPO, and is it a big deal?
NSE has actually set a rate band of Rs 1,700-1,785 per share. This is lower than the Rs 2,000-2,100 variety that numerous financiers had actually anticipated previously. At the upper end of the band, NSE is looking for an assessment of about Rs 4.4 lakh crore.
Ishan Tanna, Senior Associate at Ashika Capital, stated the lower prices is not unexpected when seen versus appraisal and development issues.
” NSE IPO appraisal has actually been cut by around 15%. At around 43 times FY26 profits, NSE is still valued at a premium to many worldwide exchanges, however looks sensible versus Indian peers such as BSE and MCX,” Tanna stated.He stated the larger concern is development. Around 60% of NSE’s operating income originates from derivatives, while the choices boom is dealing with regulative and volume-related headwinds.
“At the modified appraisal, financiers are basically wagering that NSE can move beyond the choices boom and substance through India’s wider financialisation, while leveraging its supremacy in equities, indices, information and other market sections,” Tanna stated.
So, the lower prices seems a useful relocation. “Leave some benefit for public-market financiers instead of push for a greater appraisal and threat weak need or bad post-listing efficiency,” he stated.
This is not the very first time unlisted market expectations have actually run ahead of IPO prices.
HDB Financial Services, which had actually included its IPO a couple of years earlier, likewise dealt with comparable dangers at the time. Its IPO cost band of Rs 740 had to do with 40% lower than the Rs 1,225 level at which the stock was bring simply days before the IPO. Investors who had actually purchased the stock a year previously at around Rs 1,550 were gazing at a disintegration of about 52% even before listing.
Manish Khanna, co-founder of Unlisted Assets, stated the NSE IPO is undoubtedly a truth look for unlisted financiers, however the problem requires context. “NSE is probably the greatest name, and the busiest stock, in India’s unlisted market,” Khanna stated.
According to Khanna, the cost band is well listed below earlier expectations, however the contrast ought to not be restricted to the unlisted cost versus the IPO cost.
“Even a financier who purchased in at Rs 2,100 is paying approximately an 18% premium to the IPO’s upper band, not always unreasonable for a company with NSE’s amazing market position,” he stated.
NSE’s market position stays strong this year. As of June 2026, the exchange commanded more than 93% of India’s cash-market turnover, almost 100% of equity-futures turnover and about 75% of equity-options turnover.
The bigger point, according to Khanna, is that financier returns can not be evaluated just by comparing the unlisted cost with the IPO cost. “IPO allotment size, noting premium and the business’s reasonable worth likewise matter.”
The NSE case likewise highlights the dangers of purchasing unlisted shares. Unlike noted stocks, unlisted shares do not have a transparent market value on a screen. Liquidity is restricted, disclosures are not as regular, and the exit path depends greatly on whether the business ultimately notes or whether another purchaser is readily available.
For financiers, the crucial threat is that the cost paid in the unlisted market might show buzz, deficiency and anticipated IPO gains instead of the appraisal at which organizations want to purchase in the IPO.
In the NSE case, the business’s principles stay strong, however IPO prices has actually still come listed below the level at which some unlisted trades occurred. That is the caution for financiers.
The public problem might still see strong need since of NSE’s market position. But for financiers who got in the unlisted market at greater costs, the IPO cost band reveals that pre-IPO investing is not a one-way trade.
Disclosure: This post has actually been composed by Podishetti Akash, who is not a SEBI-registered Research Analyst or anInvestment Adviser Podishetti Akash and her ‘relative( s)’ (as specified under Section 2( 77) of the Companies Act, 2013) do not hold any monetary interest in the business pointed out in this post since the date of publication. The views/recommendations pointed out in this post, any place appropriate, are those of the particular SEBI-registered Research Analyst/ brokerage and have actually been reproduced/reported with due attribution. They need to not be interpreted as the views or suggestions of The Economic Times Digital or the reporter. Readers are recommended to think about the initial research study report and make their financial investment choices based upon their own evaluation. Brokerage disclaimers here.